
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| EMF Shielding Devices for Cell Phones Market Size 2024 | USD 1500 Million |
| EMF Shielding Devices for Cell Phones Market, CAGR | 14.6% |
| EMF Shielding Devices for Cell Phones Market Size 2032 | USD 4462.4 Million |
Market Overview:
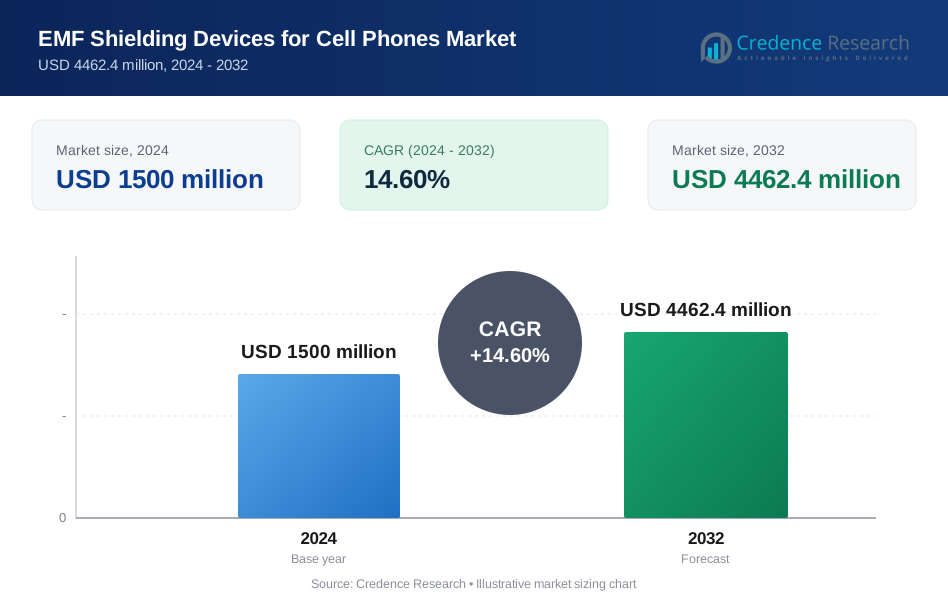
EMF Shielding Devices for Cell Phones Market size was valued at USD 1500 million in 2024 and is anticipated to reach USD 4462.4 million by 2032, at a CAGR of 14.6% during the forecast period (2024-2032).
The EMF Shielding Devices for Cell Phones Market is primarily driven by growing consumer awareness of the health risks associated with prolonged exposure to electromagnetic fields (EMF). As concerns over mobile phone radiation increase, particularly in regions with high mobile usage, consumers are increasingly seeking protective solutions. The expansion of the mobile phone industry, coupled with advancements in technology such as 5G, has raised concerns about higher levels of radiation exposure, leading to greater demand for shielding technologies. Regulatory bodies and health organizations have further emphasized the potential health impacts of EMF radiation, leading to heightened demand for EMF shielding devices. Additionally, innovations in shielding materials, such as graphene and advanced composites, are enhancing the effectiveness of these devices, making them more efficient, affordable, and appealing to consumers. This combination of awareness, regulatory pressure, and technological advancements is accelerating the market’s growth.
Regionally, North America holds a significant market share, driven by strong awareness in the United States and Canada, where research and media coverage have spurred demand for EMF shielding solutions. These regions also benefit from increasing regulatory frameworks around mobile radiation, which further supports market growth. Europe is another key market, with stringent health regulations and a growing number of mobile users seeking protection. Meanwhile, the Asia Pacific region is experiencing rapid growth due to increased mobile phone usage in countries like India and China. As mobile penetration rises in these markets, consumer concerns about EMF radiation also grow, boosting the demand for shielding devices. The rise in smartphone usage across these emerging markets is likely to drive sustained growth in the coming years.
Market Insights:
- The EMF Shielding Devices for Cell Phones Market was valued at USD 1500 million in 2024 and is projected to reach USD 4462.4 million by 2032, with a CAGR of 14.6%.
- Increasing consumer awareness of the health risks associated with prolonged exposure to electromagnetic fields (EMF) is a key driver, prompting greater demand for protective solutions.
- The expansion of mobile technology, particularly with the rise of 5G, has intensified concerns over higher levels of radiation exposure, further driving the market for EMF shielding devices.
- Regulatory bodies and health organizations have heightened awareness about the potential impacts of EMF radiation, fueling demand for shielding products.
- Innovations in shielding materials like graphene and advanced composites are improving the effectiveness, affordability, and consumer appeal of EMF shielding devices.
- North America holds the largest market share (35%), driven by strong consumer awareness, media coverage, and regulatory support for mobile radiation protection.
- The Asia Pacific region is experiencing rapid growth, particularly in countries like India and China, where increasing mobile usage and rising health concerns boost demand for EMF shielding devices.
Market Drivers:
Growing Awareness of Health Risks:
A primary driver of the EMF Shielding Devices for Cell Phones market is the increasing awareness of the potential health risks associated with prolonged exposure to electromagnetic fields (EMF). With rising concerns about mobile phone radiation, more consumers are becoming aware of the possible links between EMF exposure and health issues such as headaches, sleep disturbances, and even long-term risks like cancer. This growing awareness has led consumers to seek protective solutions, driving the demand for EMF shielding devices. Educational campaigns by health organizations, media reports, and scientific studies have further increased public concern, encouraging individuals to take preventive measures by using EMF shielding devices.
Expansion of the Mobile Phone Industry:
The rapid growth of the mobile phone industry also plays a critical role in driving the demand for EMF shielding devices. The constant innovation in mobile technology, coupled with the widespread adoption of smartphones, has significantly increased the level of electromagnetic radiation emitted by these devices. As mobile phones evolve, incorporating more features such as 5G connectivity and high-frequency signals, the potential for EMF exposure rises. For instance, according to the GSM Association’s Mobile Economy 2019 report, 5.1 billion people globally subscribed to mobile services, highlighting the widespread integration of mobile phones into daily life. Consequently, consumers are becoming more concerned about the health risks posed by these advanced technologies, pushing them towards EMF shielding products. The demand is particularly strong in countries with high smartphone penetration, where mobile phone usage is an integral part of daily life.
Regulatory Pressure and Health Guidelines:
Regulatory bodies and health organizations worldwide are increasingly addressing the concerns surrounding EMF radiation. Governments and health agencies are becoming more vocal about the potential risks of mobile radiation, and some have even set safety guidelines for mobile phone radiation emissions. For instance, the Government of India implemented stringent EMF radiation standards in 2012, lowering exposure limits for mobile towers to one-tenth of the levels recommended by the International Commission on Non-Ionizing Radiation Protection (ICNIRP) and mandating that all new mobile handsets comply with a Specific Absorption Rate (SAR) value of 1.6 W/kg averaged over 1 gram of tissue. These regulatory measures and health warnings have raised consumer awareness and encouraged individuals to adopt protective measures, including EMF shielding devices. Moreover, as more research is conducted and health concerns become more prominent, it is expected that regulatory frameworks will become stricter, further driving the market for shielding products.
Technological Advancements in Shielding Materials:
Innovation in EMF shielding technologies has also played a pivotal role in the market’s growth. The development of advanced shielding materials, such as graphene and other composites, has improved the effectiveness of EMF shielding devices. These new materials provide enhanced protection against electromagnetic radiation while maintaining the comfort and usability of mobile phones. As shielding devices become more efficient and affordable, they are gaining wider adoption among consumers. Additionally, as technology advances, manufacturers are continuously innovating to develop thinner, more flexible, and aesthetically pleasing shielding products that do not compromise the design and functionality of mobile devices. These innovations are crucial for increasing consumer acceptance and expanding the market.
Market Trends:
Advancements in Shielding Materials:
One key trend in the EMF Shielding Devices for Cell Phones Market is the integration of advanced materials in the design of shielding devices. Innovations in materials such as graphene and carbon nanotubes are enhancing the effectiveness of these products, providing better protection against electromagnetic radiation. These materials allow for thinner, more flexible, and aesthetically pleasing products that do not compromise the design or functionality of mobile phones. As consumer demand shifts toward more compact and stylish solutions, the adoption of advanced materials continues to rise, driving innovation in the market.
Increased Consumer Awareness:
Rising health concerns over mobile phone radiation have led to an increase in consumer awareness, which is fueling demand for EMF shielding products. For instance, a consumer survey conducted by DefenderShield revealed that many users reported feeling safer and more at ease when using EMF shielding phone cases and laptop shields in their daily routines. With scientific studies and media reports highlighting the potential risks of EMF exposure, consumers are becoming more cautious about their mobile phone usage and seeking ways to mitigate potential harm. This trend has resulted in growing demand for products such as EMF shielding cases, screen protectors, and patches, which can be easily incorporated into daily mobile phone usage. Manufacturers are responding by developing user-friendly solutions that seamlessly fit into consumers' lifestyles.
Health and Wellness Sector Influence:
The growing focus on health and wellness has significantly impacted the EMF Shielding Devices for Cell Phones Market. For instance, Belly Armor, a company specializing in EMF protection, has reported increased interest from expectant mothers seeking protective clothing and accessories. As more consumers prioritize their long-term health, the demand for EMF shielding products in this sector has increased. This trend is especially prominent in markets where consumer awareness of potential health risks is higher. The wellness trend has led to higher sales of EMF protection devices, which are now seen as essential accessories for those looking to protect themselves from mobile phone radiation. As awareness spreads, the demand for these devices is expected to continue growing.
Emerging Markets Growth:
The EMF Shielding Devices for Cell Phones Market is also seeing significant growth in emerging markets, particularly in regions like Asia Pacific. As mobile phone penetration increases in countries like India and China, the demand for EMF protection products is rising as well. In these markets, consumer attitudes are shifting toward increased awareness of radiation risks, and there is a growing preference for high-quality EMF shielding devices. This shift, combined with the rapid growth of mobile phone usage, is expected to further drive the global market's expansion in the coming years.
Market Challenges Analysis:
High Cost of Advanced Shielding Materials:
One of the key challenges facing the EMF Shielding Devices for Cell Phones Market is the high cost of advanced shielding materials, such as graphene and carbon nanotubes. While these materials offer superior protection and are integral to the development of more efficient and compact shielding devices, they are often expensive to produce. For instance, research published by a government-backed team demonstrated that carbon nanotube film (CNTF) embedded in composite prepregs can deliver exceptional electromagnetic interference (EMI) shielding effectiveness, along with properties like high thermal stability, hydrophobicity, and corrosion resistance, all achieved through an efficient electric heating method that streamlines production and enhances multifunctionality. The high manufacturing costs can make these devices more expensive for consumers, limiting their widespread adoption, particularly in price-sensitive markets. As a result, some consumers may opt for less effective, lower-cost alternatives, hindering the market's potential growth. Manufacturers must focus on reducing production costs through innovation and economies of scale to make these protective devices more accessible to a broader audience. Additionally, as demand for these advanced materials increases, supply chain constraints could further exacerbate cost-related challenges.
Lack of Standardization and Regulatory Hurdles:
Another significant challenge in the market is the lack of standardized regulations and certifications for EMF shielding devices. Although health concerns over mobile phone radiation are growing, the lack of universal industry standards for EMF shielding effectiveness makes it difficult for consumers to determine which products offer the best protection. This regulatory gap can lead to confusion and mistrust among consumers, potentially slowing market adoption. Moreover, varying regulations across different regions further complicate the global market landscape, making it challenging for manufacturers to ensure compliance in diverse markets. To overcome these challenges, industry stakeholders must collaborate to develop consistent standards and certifications that can ensure the quality and reliability of EMF shielding products, ultimately driving consumer confidence and market growth. Establishing clear guidelines would also help to accelerate the adoption of these devices in emerging markets.
Market Opportunities:
The EMF Shielding Devices for Cell Phones Market presents significant opportunities driven by the growing consumer concern over health risks associated with mobile phone radiation. As scientific studies and media coverage continue to highlight the potential dangers of prolonged exposure to electromagnetic fields (EMF), there is an increasing demand for protective solutions. This growing awareness opens opportunities for manufacturers to introduce a wide range of innovative, user-friendly EMF shielding devices. With advancements in materials like graphene and carbon nanotubes, manufacturers have the potential to create more effective, lightweight, and aesthetically appealing products, attracting a broader consumer base. Additionally, as mobile phone usage continues to rise globally, especially in emerging markets, the demand for EMF protection devices is expected to increase, creating new avenues for growth in these regions.
There is also an opportunity to expand the market through strategic partnerships and collaborations between manufacturers of mobile phones and EMF shielding device providers. As mobile phone companies are increasingly focusing on consumer health and safety, they can integrate EMF shielding solutions into their product offerings, either as add-ons or integrated features in phone cases and accessories. Furthermore, regulatory developments and health guidelines promoting radiation protection could drive widespread adoption of shielding devices, particularly in regions with stringent health and safety standards. These regulatory shifts, coupled with the growing focus on wellness, present an opportunity for the market to expand rapidly, especially in North America and Europe, where consumer awareness is already high.
Market Segmentation Analysis:
By Type
The EMF Shielding Devices for Cell Phones Market can be segmented by type into products such as cases, screen protectors, patches, and others. Among these, EMF shielding cases dominate the market due to their practicality and ease of use. They are widely adopted by consumers looking for all-in-one protection for their devices. Screen protectors and patches, while gaining popularity, are primarily targeted at consumers looking for more affordable, discreet options. The demand for each type is driven by varying consumer preferences for protection, convenience, and cost.
By Material Type
The market can also be segmented by material type into conductive materials, non-conductive materials, and composites. Conductive materials, including metals like aluminum and copper, are commonly used for their high shielding effectiveness. Non-conductive materials, such as ceramics and plastics, offer lighter, more flexible alternatives. The growing interest in advanced materials such as graphene and carbon nanotubes is driving the shift towards composite materials, which combine the benefits of both conductive and non-conductive materials, offering superior performance and versatility.
By Application
The primary application of EMF shielding devices is in mobile phones, as consumers are most concerned about radiation exposure from their handheld devices. However, the market is expanding to include other electronic devices, such as tablets and laptops, as awareness of EMF risks spreads across various technology platforms. As mobile phone penetration continues to rise globally, demand in this application segment is expected to dominate the market, with increasing adoption in both consumer and business environments.
Segmentations:
By Type
- Cases
- Screen Protectors
- Patches
- Other Products
By Material Type
- Conductive Materials
- Aluminum
- Copper
- Non-Conductive Materials
- Ceramics
- Plastics
- Composites
- Graphene
- Carbon Nanotubes
By Application
- Mobile Phones
- Tablets
- Laptops
- Other Electronic Devices
By Region
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- Asia Pacific
- China
- India
- Latin America
- Brazil
- Mexico
- Middle East & Africa
- United Arab Emirates
- South Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for 35% of the global EMF Shielding Devices for Cell Phones Market. The region is driven by heightened consumer awareness regarding health risks associated with electromagnetic radiation from mobile phones. In the United States and Canada, the growing concerns over mobile phone radiation and regulatory support for protective measures have led to an increase in demand for EMF shielding devices. The presence of key market players and continuous advancements in shielding materials such as graphene and carbon nanotubes further boost the market growth in this region. Additionally, rising adoption of mobile phones, coupled with the increasing focus on health and wellness, reinforces the demand for effective EMF shielding solutions. The increasing number of health-conscious consumers who prioritize radiation protection further solidifies North America's dominant position in the market.
Europe
Europe holds a 30% share of the global EMF Shielding Devices for Cell Phones Market, driven by stringent regulatory frameworks and a strong consumer base that prioritizes health protection. Countries such as Germany and the United Kingdom are seeing increased adoption of EMF shielding devices as part of the growing awareness of radiation risks from mobile phones. European regulations regarding EMF exposure and consumer safety have encouraged manufacturers to focus on creating certified products that comply with safety standards. The European market also benefits from a higher number of mobile phone users seeking protective measures, which is fostering the growth of the EMF shielding devices market. The combination of regulatory support and rising demand for safer technology solutions continues to fuel the market's growth trajectory in this region.
Asia Pacific
The Asia Pacific region is witnessing the fastest growth in the EMF shielding devices market, with a market share of 25%. This growth is largely attributed to the rapid increase in mobile phone usage and the expanding consumer base in countries like China and India. As mobile penetration rises, so does the awareness of potential health risks posed by mobile phone radiation. Emerging economies in the Asia Pacific, where mobile phone adoption is growing at a rapid pace, are becoming key markets for EMF shielding devices. Additionally, the increasing focus on consumer health and safety in these regions, combined with improving disposable income, is fueling the demand for mobile phone protective solutions. The region’s rapid adoption of 5G technology also contributes to the expected increase in demand for effective EMF shielding solutions. As mobile phone usage continues to rise, so does the need for enhanced protective devices.
Key Player Analysis:
- Shield Your Body (SYB)
- RadiArmor
- DefenderShield
- SafeSleeve
- WaveWall
- EMF Harmony
- Hedron Life Source
- Aulterra
- Lifewin
- Silent Pocket
- BlocSock
- GIA Wellness
Competitive Analysis:
The EMF Shielding Devices for Cell Phones Market is highly competitive, with key players focusing on innovation, product effectiveness, and consumer awareness to differentiate themselves. Companies like DefenderShield and SafeSleeve dominate the market, offering a range of high-quality products that combine effective shielding with consumer convenience. These companies invest heavily in research and development, utilizing advanced materials such as graphene and carbon nanotubes to enhance product performance. Shield Your Body (SYB) and RadiArmor also stand out for their high-performance EMF protection solutions, targeting health-conscious consumers with a strong focus on certification and compliance with regulatory standards. Smaller players such as WaveWall and Silent Pocket emphasize affordability and portability, attracting budget-conscious consumers while maintaining product efficacy. Overall, the competitive landscape is shaped by a constant drive for innovation, improved shielding technologies, and meeting the growing demand for health and wellness-focused solutions.
Recent Developments:
- In February 2025, SafeSleeve introduced the SafeSleeve RF Blocking Blanket, a versatile anti-radiation blanket that blocks over 99% of RF radiation (including Wi-Fi, 5G, and cellular), made with OEKO-TEX-certified fabric for skin safety.
- In February 2025, SafeSleeve released new phone and tablet cases supporting the latest iPhone, Samsung, and Pixel models, all featuring built-in EMF-blocking layers that block 99% of RF and 92% of ELF radiation, with RFID-blocking wallets and drop protection.
- In February 2025, SafeSleeve continued to offer the Anti-Radiation Headset with air tube technology for reduced EMF exposure to the head, compatible with all phones and tablets.
Market Concentration & Characteristics:
The EMF Shielding Devices for Cell Phones Market exhibits moderate market concentration, with a mix of established brands and smaller, niche players competing for market share. Leading companies like DefenderShield, SafeSleeve, and Shield Your Body (SYB) dominate the market, thanks to their strong brand recognition, high-quality products, and significant investments in research and development. These players focus on innovation, particularly through advanced materials such as graphene, to enhance shielding effectiveness. Smaller companies, including WaveWall and Silent Pocket, contribute to the market by offering affordable and portable options that cater to budget-conscious consumers. The market is characterized by increasing consumer awareness of the health risks associated with mobile phone radiation, driving demand for protective solutions. Additionally, the market is seeing a growing emphasis on regulatory compliance, certifications, and product differentiation, with companies striving to offer certified, high-performance solutions to meet evolving consumer expectations.
Report Coverage:
The research report offers an in-depth analysis based on Type, Material Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is anticipated to experience steady growth, driven by increasing consumer awareness of potential health risks associated with mobile phone radiation.
- Advancements in shielding technologies, such as the integration of graphene and carbon nanotubes, are expected to enhance the effectiveness and appeal of EMF protection devices.
- The proliferation of 5G networks is likely to intensify concerns over electromagnetic exposure, thereby boosting demand for protective solutions.
- Consumers are showing a preference for stylish and discreet EMF shielding products, prompting manufacturers to focus on design and functionality.
- The availability of online retail platforms is expanding market reach, making EMF shielding devices more accessible to a global audience.
- Regulatory bodies in various regions are anticipated to implement stricter guidelines on EMF exposure, influencing product development and market dynamics.
- The rise in mobile device usage among younger demographics is expected to drive demand for EMF protection products tailored to this group.
- Collaborations between mobile device manufacturers and EMF shielding companies may lead to integrated solutions, offering enhanced protection to consumers.
- Emerging markets, particularly in Asia Pacific, present significant growth opportunities due to increasing smartphone penetration and rising health consciousness.
- Ongoing research and consumer education initiatives are likely to further elevate the importance of EMF protection, contributing to sustained market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Awareness of Health Risks
Increasing public concern about the potential health impacts of electromagnetic field (EMF) exposure from mobile phones is prompting consumers to seek protective solutions, driving demand for EMF shielding devices.
Expansion of Mobile Phone Industry and 5G Rollout
The rapid growth in mobile phone adoption and the introduction of 5G technology have heightened concerns about higher levels of radiation exposure, leading to greater demand for effective EMF shielding products.
Regulatory Pressure and Health Guidelines
Stricter regulations and guidelines from governments and health organizations regarding EMF exposure are raising consumer awareness and encouraging the adoption of certified EMF shielding devices.
Technological Advancements in Shielding Materials
Innovations in advanced materials such as graphene and carbon nanotubes are making EMF shielding devices more effective, lightweight, and appealing, thus expanding their market adoption.
Rising Health and Wellness Trends
A growing focus on personal health and wellness, especially among health-conscious consumers and vulnerable groups like expectant mothers, is increasing the uptake of EMF shielding accessories for mobile devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of EMF Shielding Devices for Cell Phones in 2024?
What is the projected market size of EMF Shielding Devices for Cell Phones by 2032?
What is driving the growth of the EMF Shielding Devices for Cell Phones Market?
How is technological advancement influencing the EMF Shielding Devices Market?
Which regions are leading in the EMF Shielding Devices Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Cases
- 1.2.2 Screen Protectors
- 1.2.3 Patches
- 1.2.4 Other Products
- 1.3 By Application
- 1.3.1 Mobile Phones
- 1.3.2 Tablets
- 1.3.3 Laptops
- 1.3.4 Other Electronic Devices
- 1.4 By Material Type
- 1.4.1 Conductive Materials
- 1.4.2 Non-Conductive Materials
- 1.4.3 Composites
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1500 million → 2032: USD 4462.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global EMF Shielding Devices for Cell Phones Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global EMF Shielding Devices for Cell Phones Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global EMF Shielding Devices for Cell Phones Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global EMF Shielding Devices for Cell Phones Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global EMF Shielding Devices for Cell Phones Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global EMF Shielding Devices for Cell Phones Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global EMF Shielding Devices for Cell Phones Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global EMF Shielding Devices for Cell Phones Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1500 million → 2032: USD 4462.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global EMF Shielding Devices for Cell Phones Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cases
- 12.3.7.2 Screen Protectors
- 12.3.7.3 Patches
- 12.3.7.4 Other Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mobile Phones
- 12.4.7.2 Tablets
- 12.4.7.3 Laptops
- 12.4.7.4 Other Electronic Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conductive Materials
- 12.5.7.2 Non-Conductive Materials
- 12.5.7.3 Composites
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global EMF Shielding Devices for Cell Phones End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global EMF Shielding Devices for Cell Phones Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global EMF Shielding Devices for Cell Phones Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global EMF Shielding Devices for Cell Phones Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DefenderShield
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SafeSleeve
- 18.4 Shield Your Body (SYB)
- 18.5 RadiArmor
- 18.6 WaveWall
- 18.7 EMF Harmony
- 18.8 Silent Pocket
- 18.9 BlocSock
- 18.10 Aulterra
- 18.11 GIA Wellness
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

