
Market Overview:
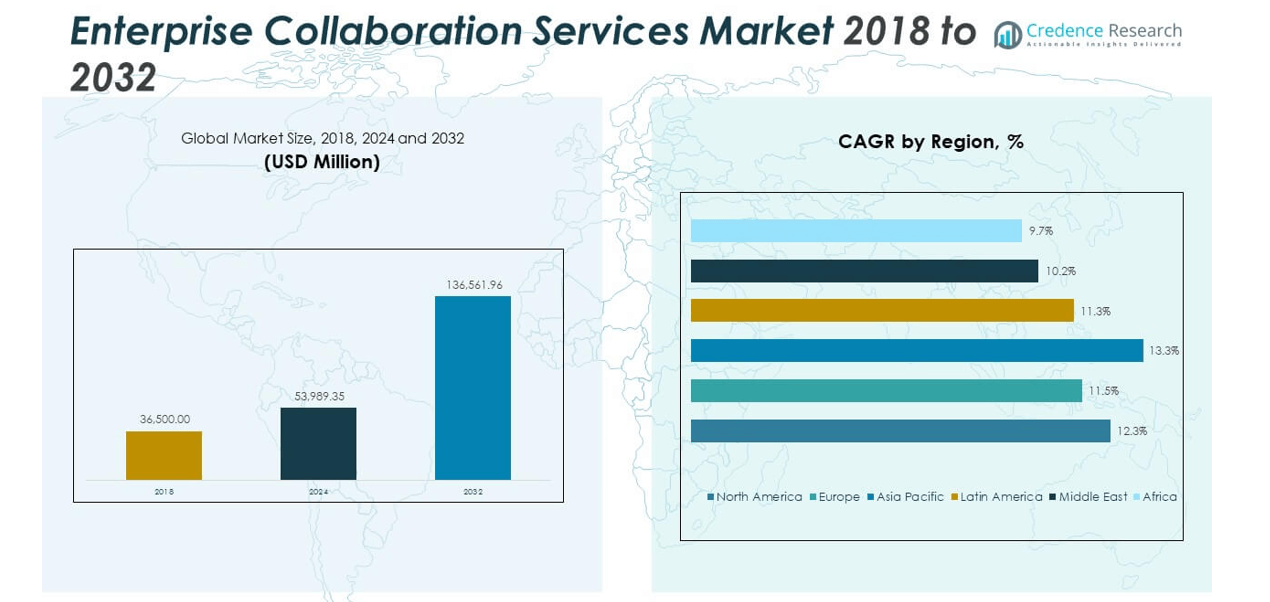
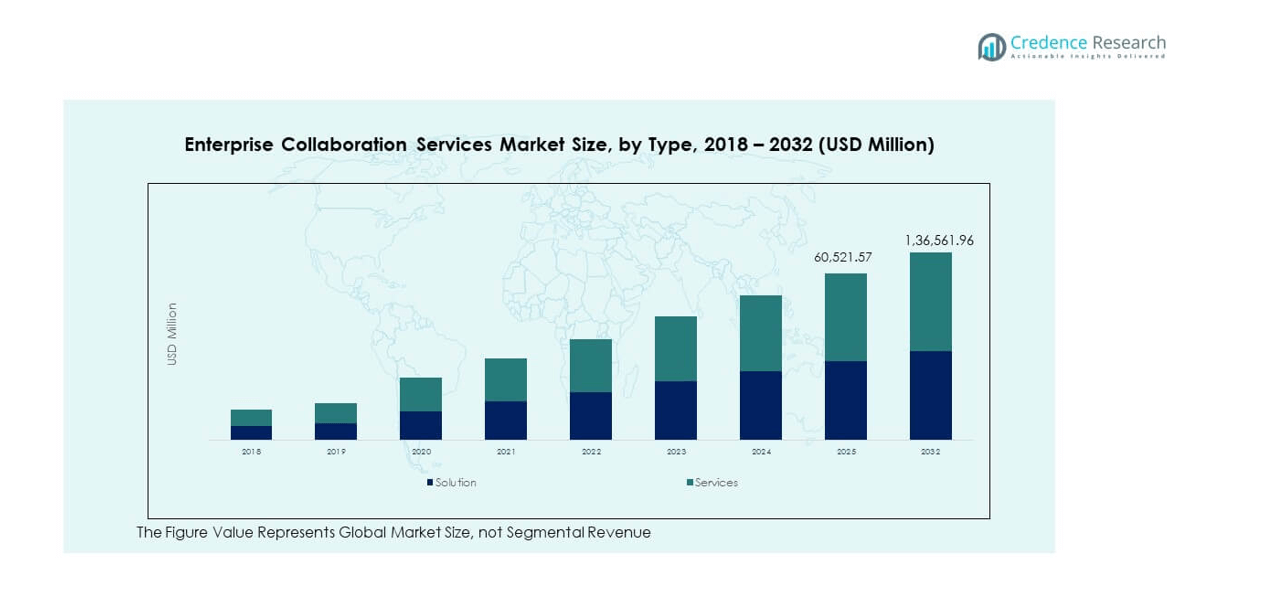
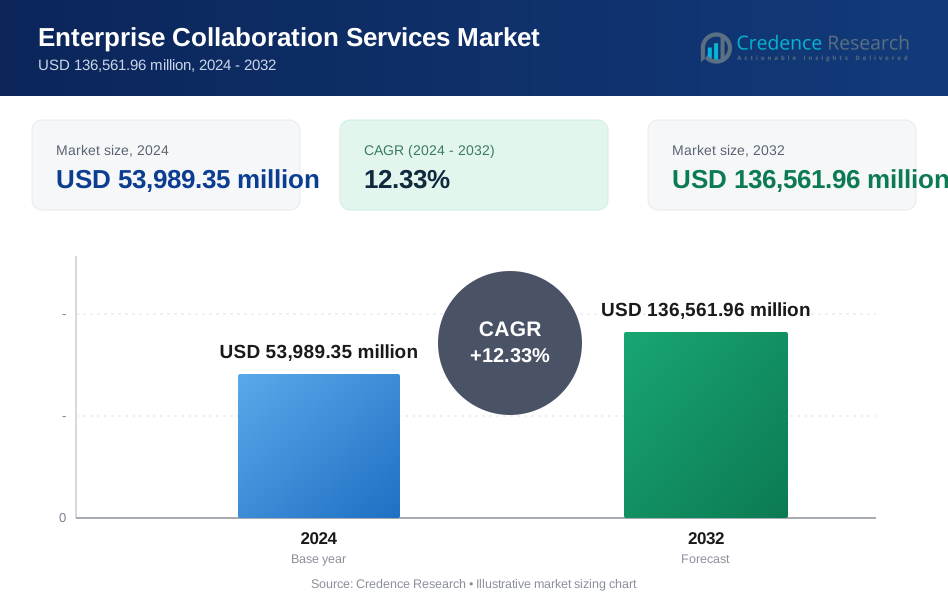
The Enterprise Collaboration Services Market size was valued at USD 36,500.00 million in 2018 to USD 53,989.35 million in 2024 and is anticipated to reach USD 136,561.96 million by 2032, at a CAGR of 12.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Enterprise Collaboration Services Market Size 2024 | USD 53,989.35 million |
| Enterprise Collaboration Services Market, CAGR | 12.33% |
| Enterprise Collaboration Services Market Size 2032 | USD 136,561.96 million |
Growth in the Enterprise Collaboration Services Market is driven by the rising adoption of cloud-based platforms, remote work expansion, and digital transformation initiatives. Organizations implement unified communication tools integrating chat, video conferencing, and project management functions. It helps enterprises improve workflow efficiency, enhance decision-making speed, and maintain secure communication networks. Demand for AI-powered collaboration software grows as companies automate scheduling, document management, and data analysis. Strong focus on workplace flexibility, employee engagement, and cybersecurity further supports rapid adoption across industries worldwide.
North America leads the Enterprise Collaboration Services Market due to strong IT infrastructure and widespread use of digital workplace solutions. Europe follows with high compliance standards and growing enterprise modernization efforts. Asia Pacific emerges as the fastest-growing region, supported by large-scale cloud adoption in China, India, and Japan. Latin America shows increasing acceptance among SMEs aiming to digitalize operations. The Middle East and Africa experience steady progress driven by smart city projects and improving internet accessibility. Each region reflects distinct enterprise collaboration maturity influenced by economic scale and digital readiness.
Market Insights:
- The Enterprise Collaboration Services Market was valued at USD 36,500.00 million in 2018, grew to USD 53,989.35 million in 2024, and is expected to reach USD 136,561.96 million by 2032, registering a CAGR of 12.33% during the forecast period.
- North America (28.4%), Asia Pacific (36.8%), and Europe (24.3%) hold the top three regional shares. Their dominance is driven by advanced cloud infrastructure, strong enterprise digitalization, and large-scale IT investments supporting collaboration technologies.
- Asia Pacific, the fastest-growing region with 8% share, leads due to rapid digital transformation, SME cloud adoption, and government-backed smart workplace initiatives in countries like China, India, and Japan.
- By type, solutions account for approximately 55–57% of the global market share, supported by high demand for unified communication and workflow management platforms among large organizations.
- The services segment holds around 43–45% share, gaining momentum from growing demand for system integration, cloud migration, and managed collaboration support across diverse enterprise environments.
Market Drivers
Rising Need for Seamless Remote and Hybrid Work Communication
The Enterprise Collaboration Services Market expands due to the widespread shift toward remote and hybrid work models. Enterprises prioritize platforms that integrate chat, video, and document-sharing features. Businesses rely on cloud-based communication suites to maintain productivity across distributed teams. It helps organizations connect securely and efficiently regardless of physical location. Demand rises for tools that enable real-time decision-making and transparent communication. Companies adopt unified collaboration systems to replace fragmented software solutions. Rapid cloud migration strengthens operational flexibility across global enterprises. This shift enhances team connectivity and drives consistent market expansion.
- For instance, Microsoft Teams reported over 320 million monthly active users globally as of early 2024, reflecting its strong position in enterprise collaboration. This milestone underscores the platform’s continued expansion across hybrid and remote work environments.
Increasing Integration of Artificial Intelligence and Automation in Collaboration Platforms
AI-powered automation drives efficiency across modern enterprise communication systems. The Enterprise Collaboration Services Market benefits from tools that automate meeting summaries, task tracking, and translation. It enables employees to focus on creative and strategic work. Smart assistants improve workflows by analyzing user behavior and suggesting context-based actions. Predictive tools help managers prioritize communication and monitor engagement patterns. Firms adopt AI-driven collaboration suites for faster data insights and improved productivity. Automation simplifies repetitive tasks and reduces operational strain. Growing investment in intelligent collaboration technology sustains steady market growth worldwide.
Growing Cloud Adoption and Shift Toward Unified Digital Workspaces
Cloud deployment accelerates collaboration across departments and external partners. The Enterprise Collaboration Services Market grows as companies migrate legacy systems to scalable cloud models. It supports better data storage, scalability, and accessibility from any device. Organizations integrate communication apps, project management tools, and analytics into single dashboards. This digital unification improves transparency and decision-making across teams. Hybrid cloud solutions address security concerns while offering flexibility for large enterprises. Businesses value real-time synchronization between tools, reducing delays and communication errors. Expanding cloud infrastructure strengthens market adoption across small and mid-sized firms.
Strong Focus on Employee Productivity and Cross-Department Collaboration
Firms invest in collaboration tools that enhance employee performance and engagement. The Enterprise Collaboration Services Market experiences demand for systems that streamline workflow management. It helps enterprises minimize time lost between communication channels. Managers use analytics to track employee interactions and improve knowledge sharing. Real-time updates promote accountability and project clarity across departments. Enhanced internal communication reduces misalignment between teams and boosts overall efficiency. Businesses favor platforms that combine productivity, creativity, and data security. Growing awareness of collaboration’s impact on performance accelerates product adoption globally.
- For instance, Zoom introduced new self-service quoting and simplified pricing tools for partners in May 2025, aiming to boost channel-driven license sales and streamline partner operations.
Market Trends
Emergence of Advanced Virtual Collaboration Tools for Hybrid Workforce Management
The Enterprise Collaboration Services Market evolves with next-generation virtual tools that mimic real office interactions. Digital whiteboards, virtual workspaces, and immersive video environments become standard features. It helps hybrid teams maintain cohesion and creativity despite distance. Companies deploy virtual environments to conduct brainstorming sessions and workshops. These solutions enhance participation and reduce fatigue associated with long video calls. Developers focus on 3D collaboration interfaces and mixed-reality features. Global firms adopt immersive collaboration to replace traditional conferencing tools. The trend pushes technology providers to merge VR, AR, and AI functionalities.
- For instance, Microsoft Teams supports webinars that can host up to 1,000 interactive participants and up to 10,000 attendees in view-only mode, providing moderation features and live engagement tools to enhance virtual collaboration for hybrid teams.
Growing Popularity of Mobile-First Collaboration Platforms Among Distributed Teams
Mobile-optimized collaboration tools dominate modern enterprise ecosystems. The Enterprise Collaboration Services Market gains from mobile-first strategies that improve accessibility for remote users. It allows workers to communicate and manage projects on smartphones or tablets. Enterprises focus on applications with offline access and high-level security. Mobile integration ensures continuity during travel and field operations. Startups and SMBs prefer mobile-first platforms due to lower infrastructure costs. Developers enhance app interfaces to support intuitive multitasking. The expanding mobile workforce strengthens long-term adoption of mobile collaboration technologies.
- For instance, Slack’s mobile app supports real-time messaging and voice or video huddles for up to 50 participants, enabling teams to collaborate seamlessly across iOS and Android devices. Its canvas feature further enhances workspace coordination and content sharing for hybrid teams.
Rising Adoption of Data-Driven Collaboration Analytics and Performance Insights
Organizations leverage analytics to evaluate communication efficiency and employee engagement. The Enterprise Collaboration Services Market witnesses growth from tools offering detailed collaboration metrics. It enables firms to optimize workflows and identify communication bottlenecks. Predictive analytics improves decision-making by highlighting team strengths and weaknesses. Enterprises use insights to refine policies and project allocation. Integration of AI-powered dashboards supports real-time performance monitoring. Managers adopt these analytics tools to build more productive digital workplaces. Increasing demand for measurable collaboration outcomes accelerates the adoption of analytics-integrated systems.
Integration of Enterprise Collaboration with Cybersecurity and Compliance Frameworks
Companies prioritize compliance and data protection in digital communication platforms. The Enterprise Collaboration Services Market aligns with regulations such as GDPR and CCPA. It ensures safe information sharing across global operations. End-to-end encryption and multi-factor authentication become mandatory standards. Vendors integrate threat detection and access control features into collaboration software. Enterprises prefer platforms certified under global cybersecurity norms. This trend boosts confidence among financial, healthcare, and government sectors. The convergence of security and collaboration technologies defines a new growth direction for the market.
Market Challenges Analysis
Data Security Risks and Regulatory Compliance Complexities Across Global Operations
The Enterprise Collaboration Services Market faces growing scrutiny over data privacy and compliance. It must manage large volumes of sensitive information exchanged daily. Different regions enforce strict data protection rules, increasing legal complexity. Enterprises struggle to ensure consistent security standards across cloud environments. Unsecured file sharing and device vulnerabilities raise cyberattack risks. Vendors need continuous software updates and compliance certifications. These requirements increase operational costs and implementation delays. Companies demand transparent data governance frameworks to maintain trust and regulatory alignment.
Integration Barriers and User Adoption Difficulties Across Diverse Systems
Organizations encounter challenges when merging new collaboration tools with legacy infrastructure. The Enterprise Collaboration Services Market experiences slow adoption among firms with limited digital maturity. It requires extensive training and change management to ensure smooth transition. Compatibility issues arise when integrating with existing CRMs, ERPs, and communication networks. Users resist change due to steep learning curves and interface differences. Downtime during migration impacts productivity and business continuity. High implementation costs discourage smaller firms from large-scale deployment. Vendors need customizable, user-friendly platforms to reduce adoption friction.
Market Opportunities
Expansion Potential Through AI-Enhanced and Industry-Specific Collaboration Platforms
Artificial intelligence creates new opportunities for innovation within the Enterprise Collaboration Services Market. It supports personalized communication experiences and adaptive workflows. Industry-specific tools designed for healthcare, education, or finance deliver tailored collaboration functions. AI chatbots streamline customer communication and automate repetitive work. Intelligent search and contextual recommendations improve knowledge management. Vendors expanding into niche sectors gain a competitive advantage. Firms investing in specialized AI-driven platforms achieve higher retention and engagement levels.
Growth Scope in Emerging Economies and SMB Digital Transformation Initiatives
Developing nations offer vast potential for collaboration service providers. The Enterprise Collaboration Services Market benefits from rapid digital infrastructure development. It supports small and mid-sized businesses adopting low-cost cloud tools. Affordable internet and smartphone access drive market penetration in Asia and Africa. Governments promote digital workplaces under national innovation agendas. Localized pricing and language support expand user bases. Vendors providing scalable and secure cloud collaboration solutions capture strong regional growth.
Market Segmentation Analysis:
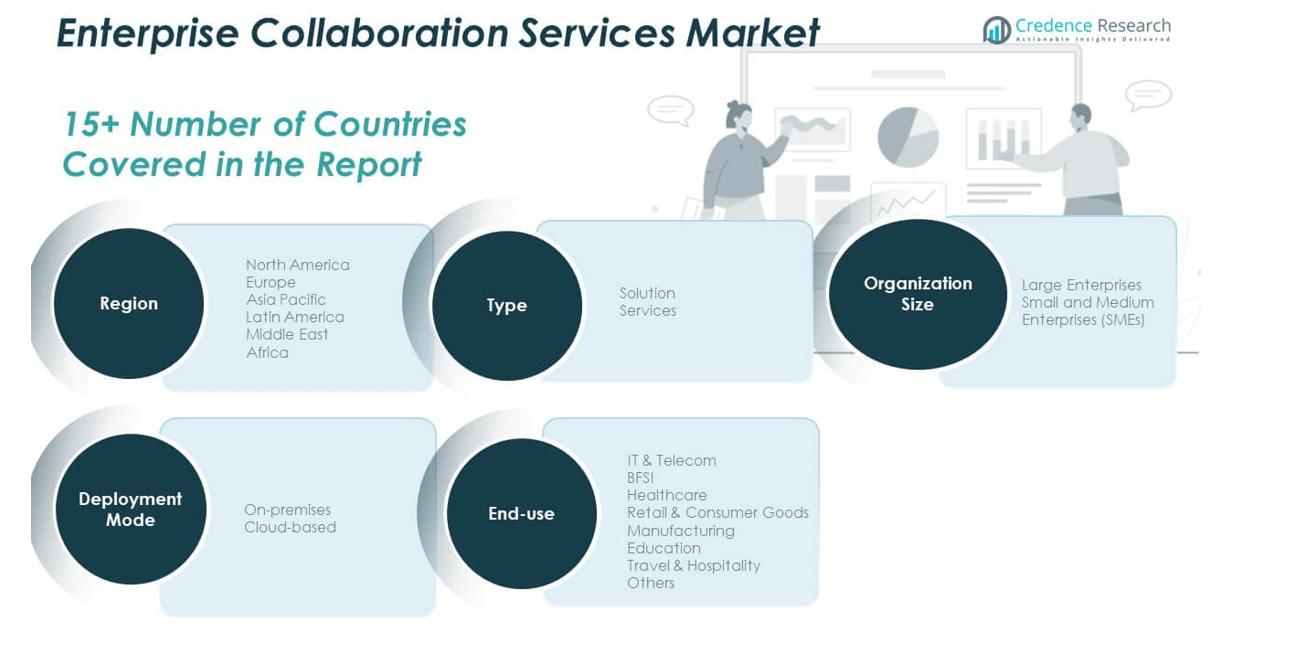
The Enterprise Collaboration Services Market is segmented by type, organization size, deployment mode, and end-use, reflecting diverse enterprise needs.
By type, solutions dominate due to growing demand for integrated platforms offering video conferencing, messaging, and file-sharing tools. Businesses focus on end-to-end systems that improve operational coordination and communication flow. Services follow with rising demand for consulting, integration, and managed support that ensure seamless platform adoption and security compliance. It supports enterprises in customizing collaboration environments aligned with business goals.
By organization size, large enterprises account for a significant share due to extensive use of advanced collaboration infrastructure across global operations. These firms invest in secure, scalable tools that connect teams across regions. Small and medium enterprises (SMEs) show rapid growth as affordable cloud-based platforms enable flexible and remote collaboration without heavy IT investment. It allows SMEs to remain agile and enhance productivity in cost-effective ways.
- For instance, Google Workspace offers 9% uptime backed by a global infrastructure and is widely used by millions of business users for secure, real-time collaboration across Docs, Sheets, and Meet. It enables seamless teamwork and efficient communication across distributed enterprise environments.
By deployment mode, the cloud-based segment leads due to scalability, cost efficiency, and remote access convenience. Businesses prefer cloud deployment for its integration capability with existing enterprise systems. On-premises models maintain steady demand among organizations prioritizing data control and regulatory compliance. Hybrid models gain traction for balancing flexibility with enhanced data security.
- For instance, Amazon Web Services (AWS) offers elastic cloud infrastructure with multiple global availability zones designed for high reliability and scalability. Its platform supports collaboration tools such as Amazon Chime, enabling secure, real-time communication and enterprise-grade performance for distributed teams.
By end-use, key adopters include IT & Telecom, BFSI, Healthcare, and Retail & Consumer Goods industries, driven by high data exchange needs and remote team coordination. Manufacturing, Education, and Travel & Hospitality also expand usage for internal communication, training, and customer engagement. It strengthens collaboration efficiency and accelerates digital transformation across industries.
Segmentation:
By Type
- Solution
- Services
By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
By Deployment Mode
- On-premises
- Cloud-based
By End-Use
- IT & Telecom
- BFSI
- Healthcare
- Retail & Consumer Goods
- Manufacturing
- Education
- Travel & Hospitality
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Enterprise Collaboration Services Market size was valued at USD 10,548.50 million in 2018 to USD 15,365.05 million in 2024 and is anticipated to reach USD 38,797.50 million by 2032, at a CAGR of 12.3% during the forecast period. North America holds nearly 28.4% of the global share due to advanced ICT infrastructure and high enterprise digitization. The region benefits from widespread adoption of cloud communication tools among major corporations. It shows strong integration of AI-based collaboration platforms that improve workflow automation. Demand grows across IT, telecom, and BFSI sectors for secure, data-driven communication. The presence of key vendors such as Microsoft, Cisco, and Zoom strengthens the ecosystem. Organizations emphasize compliance and security standards for remote operations. Rapid expansion of hybrid work culture across industries drives continuous software innovation.
Europe
The Europe Enterprise Collaboration Services Market size was valued at USD 9,234.50 million in 2018 to USD 13,107.14 million in 2024 and is anticipated to reach USD 31,238.91 million by 2032, at a CAGR of 11.5% during the forecast period. Europe accounts for 24.3% of the global market share. The region witnesses strong uptake driven by digital workplace transformation and remote workforce management. Governments promote secure data sharing under GDPR compliance, encouraging adoption of reliable platforms. Enterprises in Germany, France, and the UK lead demand for collaboration software integrated with cloud and AI. BFSI and manufacturing sectors adopt digital communication tools to enhance coordination. Vendors focus on data sovereignty and regional hosting capabilities. Growing preference for open-source and customizable solutions supports adoption across small firms.
Asia Pacific
The Asia Pacific Enterprise Collaboration Services Market size was valued at USD 12,738.50 million in 2018 to USD 19,427.84 million in 2024 and is anticipated to reach USD 52,753.99 million by 2032, at a CAGR of 13.3% during the forecast period. Asia Pacific leads with 36.8% of the global share, emerging as the fastest-growing region. The region’s rapid digital transformation and strong cloud infrastructure drive collaboration service adoption. Enterprises in China, India, Japan, and South Korea deploy digital platforms to support distributed teams. It experiences expansion across technology, education, and manufacturing sectors. Startups and SMEs adopt affordable cloud-based systems to enhance operational connectivity. Government initiatives promoting smart workplaces accelerate digital adoption. Rising mobile workforce and remote learning trends reinforce market strength.
Latin America
The Latin America Enterprise Collaboration Services Market size was valued at USD 2,226.50 million in 2018 to USD 3,260.42 million in 2024 and is anticipated to reach USD 7,629.72 million by 2032, at a CAGR of 11.3% during the forecast period. Latin America captures 5.3% of the total market share. The region witnesses increasing demand from mid-sized companies seeking affordable digital collaboration tools. Brazil and Mexico dominate usage due to strong enterprise digitalization and expanding cloud networks. It gains momentum from government programs supporting remote business communication. Local vendors provide region-specific collaboration suites adapted to language and infrastructure needs. Businesses integrate collaboration platforms for employee training and remote client servicing. Slow digital infrastructure development remains a challenge, yet cloud expansion offsets limitations.
Middle East
The Middle East Enterprise Collaboration Services Market size was valued at USD 985.50 million in 2018 to USD 1,327.79 million in 2024 and is anticipated to reach USD 2,882.21 million by 2032, at a CAGR of 10.2% during the forecast period. The Middle East accounts for 2.0% of the global share, reflecting steady digital transition. Governments promote collaboration technology to enhance business resilience and workforce efficiency. GCC countries lead adoption with heavy investment in digital workplace modernization. The region’s focus on smart city projects supports demand for connected enterprise solutions. It sees growth in sectors such as banking, education, and healthcare. Vendors introduce secure cloud models compliant with local data regulations. Businesses adopt hybrid work tools to balance productivity and security.
Africa
The Africa Enterprise Collaboration Services Market size was valued at USD 766.50 million in 2018 to USD 1,501.12 million in 2024 and is anticipated to reach USD 3,259.63 million by 2032, at a CAGR of 9.7% during the forecast period. Africa holds 3.0% of the total market share, showing consistent improvement in digital maturity. It experiences growing collaboration adoption across small enterprises and public sectors. South Africa and Egypt dominate usage, supported by expanding broadband and cloud accessibility. Businesses implement digital tools to manage remote operations and workforce communication. It faces infrastructure constraints, but low-cost cloud offerings drive steady progress. Global vendors enter partnerships to localize solutions and improve accessibility. Adoption strengthens in education and service industries that prioritize communication agility.
Key Player Analysis:
- Microsoft Corporation
- Cisco Systems, Inc.
- Zoom Communications, Inc.
- Google LLC
- Salesforce, Inc.
- SAP SE
- Cloud Software Group, Inc.
- Atlassian Corporation Plc
- Igloo Software
- Zoho Corporation Pvt. Ltd.
Competitive Analysis:
The Enterprise Collaboration Services Market sees intense competition among vendors offering integrated communication platforms, cloud services and managed collaboration tools. Large incumbents deliver feature-rich suites that combine messaging, video conferencing, document sharing and analytics. Niche providers target SMEs or vertical markets such as healthcare, education or manufacturing with tailored offerings. It drives continuous product improvement and frequent release cycles. Providers invest heavily in security, compliance and data governance to meet the demands of regulated industries. It forces price competition, compelling vendors to provide flexible subscription plans and modular pricing models. Consolidation proceeds through mergers, acquisitions or strategic alliances aimed at expanding geographic reach and capabilities. It raises entry barriers for smaller players lacking scale or compliance infrastructure. Buyers gain broader options, while vendors differentiate through AI-enabled workflows, localized language support and superior customer service. The competitive pressure will shape future market structure and innovation pace.
Recent Developments:
- In November 2025 Cisco Systems, Inc. announced its intent to acquire two firms: EzDubs and NeuralFabric. The move aims to add real-time AI-driven speech translation and enterprise AI platform capabilities to Cisco’s collaboration solutions.
- In October 2025, Zoho Corporation Pvt. Ltd. launched Vani, a visual collaboration platform with an infinite canvas, smart templates, and built-in video conferencing to boost team workflows in remote and hybrid settings.
Report Coverage:
The research report offers an in-depth analysis based on type, organization size, deployment mode, and end-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Enterprise Collaboration Services Market will expand with growing hybrid and remote work adoption.
- AI and automation will transform collaboration efficiency through intelligent assistants and real-time analytics.
- Cloud-based deployment will continue to dominate, offering scalable and cost-effective solutions for all enterprise sizes.
- Integration with advanced cybersecurity frameworks will become essential to maintain data privacy and compliance.
- Mobile-first collaboration tools will gain popularity due to increasing remote workforce mobility.
- Demand for industry-specific collaboration platforms will rise, driven by customized workflow needs in sectors like healthcare and BFSI.
- Analytics-enabled collaboration will empower businesses with deeper insights into team performance and communication trends.
- SMEs will emerge as key adopters due to accessible subscription models and minimal infrastructure needs.
- Partnerships between software vendors and telecom providers will accelerate the development of unified communication ecosystems.
- Continuous innovation in AR and VR collaboration tools will enhance immersive team experiences and redefine enterprise engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Enterprise Collaboration Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Enterprise Collaboration Services Market projected to grow between 2024 and 2032?
How do cloud-based collaboration tools differ from on-premise solutions?
What are the main benefits of using AI in collaboration tools?
Which industries are benefiting the most from enterprise collaboration services?
What factors should businesses consider when choosing a collaboration tool?
Who are the leading companies in the Enterprise Collaboration Services Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Enterprise Collaboration Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Enterprise Collaboration Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 53,989.35 million → 2032: USD 136,561.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Enterprise Collaboration Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Enterprise Collaboration Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Enterprise Collaboration Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Enterprise Collaboration Services Market Drivers
- 3.3 Enterprise Collaboration Services Market Restraints & Challenges
- 3.4 Enterprise Collaboration Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Enterprise Collaboration Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Enterprise Collaboration Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Enterprise Collaboration Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Enterprise Collaboration Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Enterprise Collaboration Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Enterprise Collaboration Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Enterprise Collaboration Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Enterprise Collaboration Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Enterprise Collaboration Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Enterprise Collaboration Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Enterprise Collaboration Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Enterprise Collaboration Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Enterprise Collaboration Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Enterprise Collaboration Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Enterprise Collaboration Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Enterprise Collaboration Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Enterprise Collaboration Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Enterprise Collaboration Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Enterprise Collaboration Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
