
Market Overview:
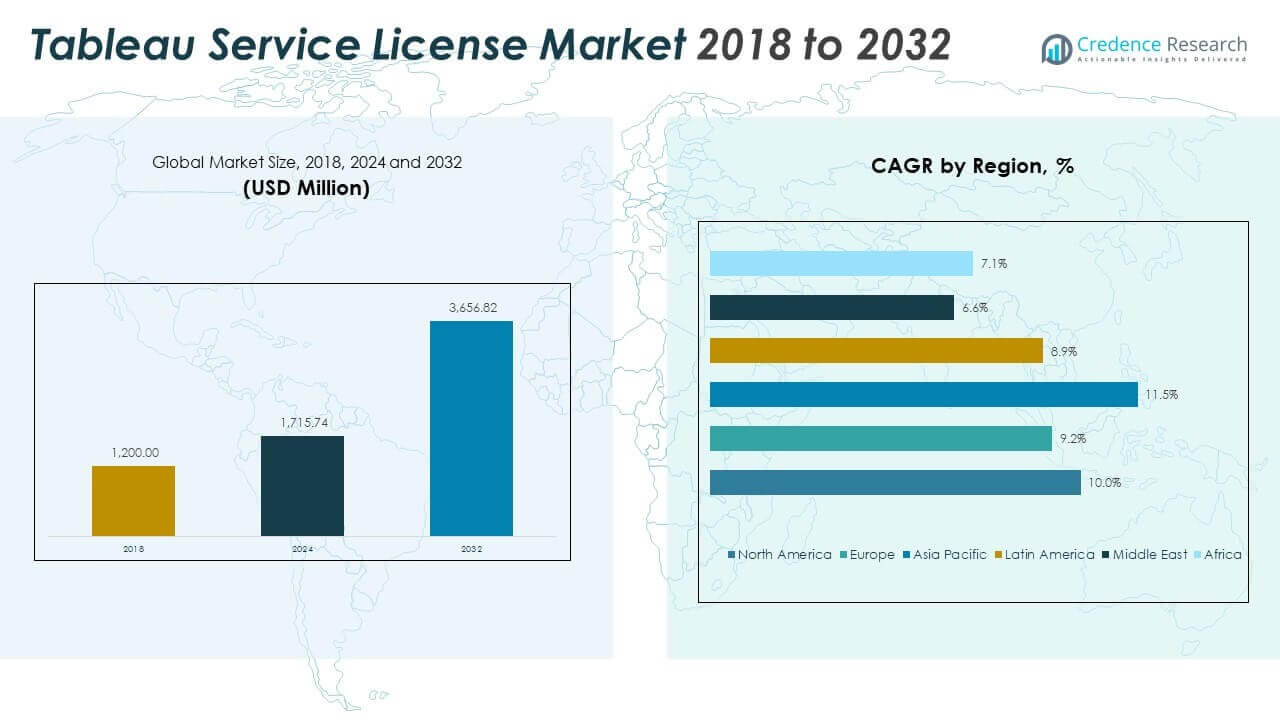
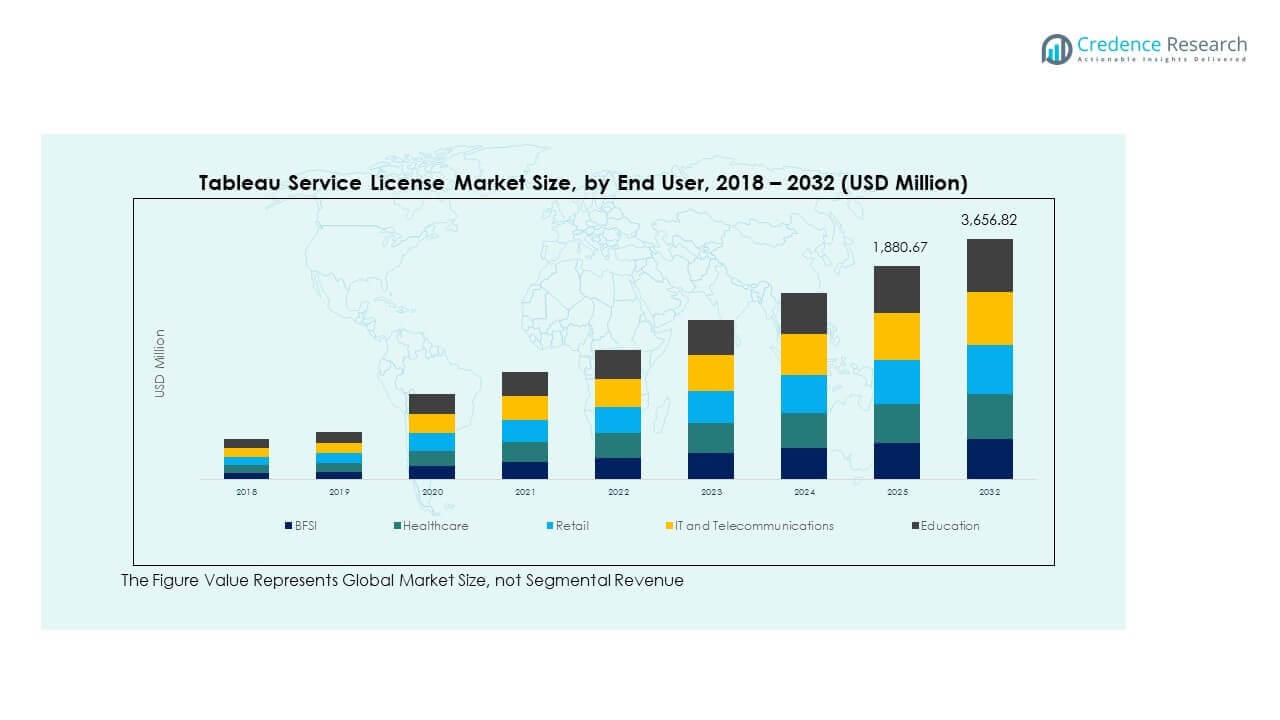
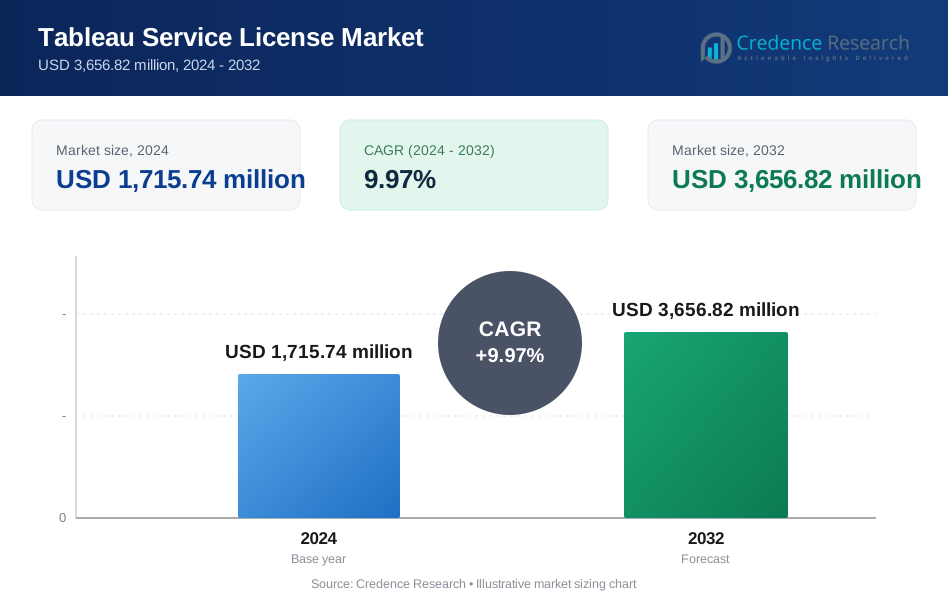
The Tableau Service License Market size was valued at USD 1,200.00 million in 2018 to USD 1,715.74 million in 2024 and is anticipated to reach USD 3,656.82 million by 2032, at a CAGR of 9.97% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tableau Service License Market Size 2024 | USD 1,715.74 Million |
| Tableau Service License Market, CAGR | 12.8% |
| Tableau Service License Market Size 2032 | USD 3,656.82 Million |
The market continues to grow due to increasing enterprise focus on real-time insights, data visualization, and user-friendly analytics tools. Organizations prioritize self-service BI, allowing non-technical users to access and act on data. Tableau's integration with CRM, cloud platforms, and AI tools strengthens its utility across business functions. Businesses prefer license models that scale with usage across departments. Growing emphasis on governed analytics, predictive modeling, and automation features fuels upgrades to premium license tiers.
North America leads the market due to strong enterprise digitization and early Tableau adoption. Europe follows with widespread use across regulated industries like BFSI and healthcare. Asia Pacific is emerging as the fastest-growing region, driven by rapid cloud adoption and digital transformation across mid-sized firms. Latin America, the Middle East, and Africa show gradual growth supported by public sector analytics initiatives and rising SME interest in scalable BI tools. Regional demand patterns reflect maturity of digital infrastructure, regulatory environments, and enterprise size distribution.
Market Insights:
- The Tableau Service License Market was valued at USD 1,200.00 million in 2018, reached USD 1,715.74 million in 2024, and is projected to hit USD 3,656.82 million by 2032, registering a CAGR of 9.97% during the forecast period.
- North America led the market with a 42.35% share in 2024, followed by Europe at 25.29% and Asia Pacific at 22.16%, driven by strong enterprise BI adoption, robust cloud infrastructure, and digital transformation across large organizations.
- Asia Pacific is the fastest-growing region with a CAGR of 11.5%, supported by high demand from SMEs, expanding tech ecosystems, and rapid digitalization in India, China, and Southeast Asia.
- The Creator license segment contributed the largest revenue share due to its comprehensive features supporting dashboard creation, analysis, and collaboration.
- Cloud deployment dominated the market segment share in 2024, driven by the shift toward scalable, low-maintenance, and remote-access analytics platforms.
Market Drivers
Growing Demand for Self-Service Business Intelligence Tools Across Departments
Organizations want faster, easier access to insights without depending on IT teams. Tableau enables non-technical users to explore and visualize data independently. This shift toward self-service analytics boosts license demand across business functions. Marketing, finance, HR, and operations increasingly rely on Tableau dashboards for routine decision-making. Companies prefer license models that scale with department needs. The Tableau Service License Market benefits from this decentralization of data access. Flexible deployment options further support department-level rollouts. User-friendly interfaces reduce training time and speed up adoption. License upgrades align with expanding user roles.
- For instance, JPMorgan Chase deployed Tableau to over 30,000 users across 500 teams, enabling enterprise-wide adoption of self-service analytics. This implementation helped streamline reporting and expanded dashboard access across departments with diverse data needs.
Expansion of Data Ecosystems Across Enterprises and Cloud Platforms
Enterprise data volumes continue to grow from CRM, ERP, and IoT platforms. Tableau integrates smoothly with multiple databases, cloud storage, and big data tools. Its connectors allow seamless access to data across hybrid environments. Companies rely on licenses to connect Tableau with AWS, Azure, and Google Cloud. Strong compatibility with Salesforce fuels demand for enterprise licenses. The Tableau Service License Market gains from such widespread ecosystem integration. Businesses want licenses that support varied data sources without customization. Pre-built templates and APIs support operational scale. License renewals grow with continued infrastructure expansion.
- For instance, Red Hat embraced Tableau Blueprint and Tableau Cloud to deepen its data culture across 4,500+ staff in under a year, showing broad ecosystem integration across cloud and hybrid environments.
Emphasis on Real-Time Analytics and Faster Decision-Making Frameworks
Companies need faster decision-making based on live data insights. Tableau enables real-time dashboards that help monitor KPIs, customer trends, and operational issues. Manufacturing, logistics, and retail sectors depend on live dashboards for operational continuity. Organizations prefer licenses that support real-time connectors and refresh cycles. Licensing includes governance controls for managing real-time access and updates. The Tableau Service License Market grows as firms adopt agile data-driven strategies. Interactive features like drill-down and filters add business value. Real-time alerts help preempt risks and improve response times. Business continuity goals drive long-term license contracts.
Integration with AI-Driven Analytics and Predictive Modeling Platforms
Tableau increasingly supports advanced analytics through integration with Python, R, and Einstein AI. Users employ predictive models and AI-driven forecasting within Tableau dashboards. This encourages analytics teams to upgrade to advanced service licenses. Businesses aim to combine data visualization with prescriptive analytics. The Tableau Service License Market expands with rising demand for AI-powered insights. Licenses offer access to advanced features like data prep and model deployment. Organizations choose higher-tier plans to unlock such functionality. AI integration increases renewal value and long-term subscriptions. This driver supports premium pricing for enterprise licenses.
Market Trends
Transition Toward Subscription-Based Licensing Across Global Enterprises
Traditional one-time software purchases are shifting to annual or multi-year subscription models. Organizations prefer predictable costs and regular feature updates through subscription plans. Tableau offers flexible Creator, Explorer, and Viewer license tiers under a subscription framework. This model reduces upfront cost and improves accessibility for smaller businesses. Global rollout of cloud-first strategies aligns with subscription preference. The Tableau Service License Market reflects this trend through increased recurring revenue streams. Vendors focus on customer retention and value-added services. License bundling with consulting and training is rising. This model supports account expansion and renewals.
Rising Focus on Embedded Analytics Within Enterprise Applications
Businesses embed Tableau dashboards within their internal and client-facing applications. This allows users to interact with visualizations without switching platforms. Demand for Tableau Embedded Analytics grows in sectors like healthcare, finance, and logistics. Companies use embedded capabilities to improve client experience and operational reporting. The Tableau Service License Market gains from license types supporting OEM and API integration. Tableau’s extensibility drives growth in vertical-specific solutions. Vendors offer tailored licensing for ISVs and platform developers. This trend accelerates license expansion in B2B SaaS platforms. Embedded dashboards increase user engagement and stickiness.
- For instance, Charles Schwab embedded Tableau dashboards into its client reporting platform so financial advisors could interact with analytics directly within the tools they use daily, helping thousands of advisors deliver insights without switching systems.
Adoption of Role-Based Licensing to Streamline Access and Governance
Organizations deploy Tableau licenses by role-Creators build dashboards, Explorers interact with data, and Viewers consume insights. Role-based licenses optimize cost, control access, and support compliance. Enterprises value this model for its flexibility in managing large user bases. The Tableau Service License Market benefits from segmentation of usage rights. IT teams can monitor license use and adjust roles based on activity. License tiers align with business unit needs and budget controls. This model supports secure sharing of insights across departments. Adoption grows in regulated industries requiring strict data governance. Role clarity also boosts user productivity.
Growth of Tableau Public and Community-Led Learning Ecosystems
Wider Tableau adoption is supported by its active online community and public dashboard gallery. Free learning resources, forums, and certification programs improve product familiarity. Tableau Public acts as a showcase platform for developers and analysts. Enterprises gain confidence from the ecosystem’s scale and maturity. The Tableau Service License Market sees benefits from user-led promotion. Community-driven training reduces onboarding costs for organizations. Public dashboard examples inspire new use cases across sectors. Certification boosts professional adoption and enterprise trust. Market growth is supported by this strong ecosystem engagement.
- For instance, researchers Yifan Wu, Yifan Zhou, and Zhicheng Liu analyzed a dataset of 25,620 dashboards curated from Tableau Public to identify design patterns and common visualization practices, highlighting the depth of user-generated content and the strength of the Tableau community ecosystem.
Market Challenges Analysis
High Cost of Licensing for Large-Scale or Long-Term Enterprise Deployments
Enterprises managing large-scale deployments face high recurring licensing costs. Organizations with thousands of users often struggle to justify per-user pricing. Budget constraints limit adoption across smaller departments or public sector units. The Tableau Service License Market contends with procurement pushback during expansion plans. CFOs evaluate license cost per active user to reduce overspending. Complexity in managing multiple license types adds to cost management issues. Vendors must balance feature updates with pricing transparency. Resistance to long-term contracts can impact revenue forecasts. This cost sensitivity limits market penetration in price-conscious industries.
Integration Complexity with Legacy IT Systems and On-Premise Architecture
Not all enterprises operate in modern cloud-first environments. Older IT systems often lack compatibility with Tableau’s integration frameworks. Connecting Tableau to legacy databases or on-premise software can be technically challenging. The Tableau Service License Market faces delays in adoption due to integration hurdles. In-house teams may lack the expertise to configure and optimize Tableau services. Custom connectors or middleware raise project complexity and costs. Security policies in government and banking further complicate deployment. These challenges slow conversion from pilot to full-scale licensing. Vendors address this through onboarding support and migration tools.
Market Opportunities
Increasing Demand from SMEs Seeking Scalable and Affordable Analytics Solutions
Small and medium enterprises want analytics tools without investing in full data science teams. Tableau offers scalable licenses that fit their growing data needs. Cloud-based delivery removes the need for complex IT infrastructure. The Tableau Service License Market sees rising adoption in SMEs through tiered licensing. Pricing flexibility and user-based access support this trend. Vendors can expand footprint by offering bundled services to startups and mid-size firms. Licensing tailored for smaller teams increases accessibility. The SME segment offers strong multi-year growth potential.
Rising Public Sector Digitization and Data Transparency Initiatives
Governments and public institutions are embracing data transparency and digital dashboards. Tableau supports open data platforms and citizen-focused analytics. Licensing gains traction through central government and municipal contracts. The Tableau Service License Market benefits from public sector tenders and multi-department adoption. Projects in healthcare, education, and urban governance drive license volume. Vendors partner with public agencies to offer long-term scalable packages. This segment provides stable demand and high renewal rates.
Market Segmentation Analysis:
The Tableau Service License Market is segmented by license type, deployment mode, enterprise size, and end-user industry.
By license type, the Creator segment dominates due to its full functionality that allows users to build dashboards and perform deep analytics. Explorer licenses hold a strong mid-tier presence, enabling users to interact with existing dashboards and conduct basic analysis. Viewer licenses remain the most cost-effective tier, appealing to organizations looking to scale insights without high per-user costs. This segmentation supports flexible deployment across diverse business functions.
By deployment mode, the cloud segment leads the market with rising demand for scalability, real-time collaboration, and remote access. Cloud deployment is preferred by businesses undergoing digital transformation. The on-premises segment maintains relevance among large enterprises with strict data governance requirements or legacy infrastructure. Licensing preferences shift toward hybrid environments where both modes coexist. This flexibility supports broader Tableau adoption across industries.
By enterprise size, large enterprises hold a majority share, driven by complex data environments and higher analytics maturity. However, small and medium enterprises are adopting Tableau at a faster rate. Flexible licensing and cloud deployment lower the entry barrier for SMEs. The Tableau Service License Market benefits from growing demand across both segments. Tiered licensing allows companies to scale as they grow.
- For instance, the Indiana Management Performance Hub uses Tableau to drive statewide analytics, creating dashboards that support more than 150 calculations for 41 performance metrics across all 92 counties and reducing visualization rendering times significantly while improving data agility and user interaction.
By end-user industries, BFSI, IT & telecommunications, and healthcare dominate due to their heavy reliance on data. Retail and education sectors also show strong adoption. Others include manufacturing, logistics, and public sector, where Tableau use cases continue to expand. Each industry segment contributes to stable license demand across global markets.
- For instance, Charles Schwab has used Tableau to enhance internal analytics and visualization capabilities, enabling its teams to derive insights more efficiently from complex financial data. This supports more informed decision-making across its wealth and investment operations.
Segmentation:
By License Type
- Creator
- Explorer
- Viewer
By Deployment Mode
- On-Premises
- Cloud
By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
By End-User Industry
- BFSI
- Healthcare
- Retail
- IT and Telecommunications
- Education
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Tableau Service License Market size was valued at USD 513.60 million in 2018 to USD 726.78 million in 2024 and is anticipated to reach USD 1,547.21 million by 2032, at a CAGR of 10.0% during the forecast period. North America holds the largest share in the Tableau Service License Market at 42.35% in 2024. Strong enterprise digitization, cloud adoption, and early self-service BI adoption drive market growth. The U.S. leads due to its large corporate user base, advanced IT infrastructure, and widespread Salesforce ecosystem. Most enterprises in the region use role-based Tableau licensing for cross-functional teams. Subscription models gain traction across finance, healthcare, and tech industries. Deployment on AWS and Azure increases cloud license demand. Canada and Mexico show steady adoption, especially among SMEs. Strong regional demand ensures high license renewal and upgrade rates.
Europe
The Europe Tableau Service License Market size was valued at USD 315.84 million in 2018 to USD 434.04 million in 2024 and is anticipated to reach USD 873.81 million by 2032, at a CAGR of 9.2% during the forecast period. Europe accounts for 25.29% of the 2024 market share. Businesses across Germany, the UK, and France drive demand for advanced analytics and dashboarding. GDPR compliance influences deployment mode selection, with many firms choosing hybrid or on-premise models. BFSI, manufacturing, and public sector lead Tableau adoption in the region. Governments invest in data transparency and reporting tools, boosting license volume. European companies value customization and integration flexibility. Tableau’s multilingual support aligns well with regional diversity. Innovation hubs in Western Europe contribute to steady product expansion.
Asia Pacific
The Asia Pacific Tableau Service License Market size was valued at USD 253.20 million in 2018 to USD 380.63 million in 2024 and is anticipated to reach USD 907.99 million by 2032, at a CAGR of 11.5% during the forecast period. Asia Pacific holds a 22.16% market share in 2024 and shows the fastest regional growth. Emerging economies like India, China, and Vietnam drive demand for scalable, cost-effective analytics solutions. SMEs adopt cloud-based Tableau licenses due to lower infrastructure requirements. Rapid digital transformation across BFSI, retail, and telecom sectors accelerates adoption. Governments push for data modernization and visualization tools in public services. Japan and South Korea support adoption in large enterprises. Cloud-first strategies across Southeast Asia contribute to rising subscription volume. The regional market sees strong vendor partnerships and training ecosystem expansion.
Latin America
The Latin America Tableau Service License Market size was valued at USD 74.40 million in 2018 to USD 105.33 million in 2024 and is anticipated to reach USD 207.96 million by 2032, at a CAGR of 8.9% during the forecast period. Latin America represents 6.13% of the 2024 market share. Brazil leads market activity with rising investments in business analytics and enterprise cloud platforms. Companies adopt Tableau to improve operational reporting, sales performance, and financial tracking. Mexico shows strong uptake in retail and telecom sectors. Regional economic reforms support enterprise IT expansion, favoring subscription-based models. Public sector demand grows with focus on digital governance. On-premise deployments remain relevant for compliance in banking. Language localization and local partner networks support growth. Data-driven culture adoption is slower but steadily increasing.
Middle East
The Middle East Tableau Service License Market size was valued at USD 21.60 million in 2018 to USD 26.75 million in 2024 and is anticipated to reach USD 44.27 million by 2032, at a CAGR of 6.6% during the forecast period. The region holds a 1.56% share of the 2024 market. Government-led digitization in the UAE and Saudi Arabia drives enterprise BI demand. Oil & gas, telecom, and banking sectors lead Tableau license adoption. Smart city projects support real-time dashboards and citizen service analytics. Enterprises prefer hybrid deployment models due to data residency requirements. Tableau’s integration with CRM and ERP platforms enhances use case relevance. Cloud adoption accelerates in Qatar and Bahrain. Localized training and reseller support enable market penetration. Budget constraints and skill gaps remain key barriers in broader regional uptake.
Africa
The Africa Tableau Service License Market size was valued at USD 21.36 million in 2018 to USD 42.21 million in 2024 and is anticipated to reach USD 75.58 million by 2032, at a CAGR of 7.1% during the forecast period. Africa contributes 2.46% to the global market in 2024. South Africa leads adoption, followed by Egypt and Kenya. Businesses invest in dashboard solutions for finance, logistics, and telecom. Government programs support digital public service platforms using BI tools. SMEs drive demand for cloud-based licenses due to low entry barriers. Regional training hubs and partnerships support user onboarding. Tableau supports multilingual needs in education and healthcare analytics. Infrastructure limitations slow deployment in rural and underdeveloped zones. The market expands with international aid-driven data transparency projects.
Key Player Analysis:
- Salesforce, Inc.
- Microsoft Corporation
- IBM Corporation
- Oracle Corporation
- SAP SE
- Amazon Web Services, Inc.
- QlikTech International AB
- TIBCO Software Inc.
- Sisense Inc.
- MicroStrategy Incorporated
- Domo, Inc.
- Looker Data Sciences, Inc.
- Alteryx, Inc.
- SAS Institute Inc.
- Zoho Corporation Pvt. Ltd.
- Infor, Inc.
- Yellowfin International Pty Ltd
- GoodData Corporation
- Board International S.A.
- Birst, Inc.
Competitive Analysis:
The Tableau Service License Market remains highly competitive, shaped by a mix of global software leaders and specialized analytics vendors. Salesforce, as the parent company of Tableau, leads with deep integration into its CRM ecosystem and continuous feature updates. Microsoft, with Power BI, offers strong competition due to its bundled Office ecosystem and aggressive pricing. IBM, Oracle, SAP, and AWS expand market pressure through enterprise BI platforms targeting regulated sectors. It sees further rivalry from Qlik, Sisense, and MicroStrategy, which cater to niche use cases and industries. Vendors focus on differentiating through deployment flexibility, embedded analytics, and role-based licensing. Cloud-native platforms gain edge in fast-growing SME and APAC markets. Market players invest in training, customer success programs, and industry-specific use cases to retain clients. Strategic acquisitions and AI integration strengthen competitive positions. The landscape favors firms that offer scalable licensing and seamless data integration across enterprise systems.
Recent Developments:
- In November 2025, Tableau launched its latest release featuring MCP Server and improved Published Data Sources for faster analytics workflows.
- In April 2025, Salesforce launched Tableau Next, a new analytics platform built with agentic AI features to transform how organizations use data within dashboards and workflows. The company introduced this platform to accelerate data‑to‑action processes, combining AI‑powered semantic understanding with automation that guides users from insights to recommended actions.
Report Coverage:
The research report offers an in-depth analysis based on license type, deployment mode, enterprise size, and end-user industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Enterprise demand will rise as organizations expand self-service analytics across business units and reduce dependence on centralized IT teams.
- Cloud-first strategies will strengthen subscription-based licensing adoption across both mature and emerging enterprise environments.
- Integration with CRM, ERP, and data lake platforms will remain a key factor shaping long-term license renewal decisions.
- AI-assisted analytics features will push enterprises toward higher-tier licenses with advanced modeling and automation capabilities.
- Role-based licensing will gain importance as companies seek tighter governance and optimized per-user analytics spending.
- SME adoption will accelerate through flexible cloud deployment and scalable license structures tailored for smaller teams.
- Embedded analytics use cases will grow as software vendors integrate Tableau dashboards into customer-facing applications.
- Public sector digitization programs will support steady license demand for transparency and performance monitoring initiatives.
- Regional growth will stay strongest in Asia Pacific due to rapid digital transformation and cloud adoption momentum.
- Vendor competition will intensify around pricing flexibility, ecosystem integration, and customer success programs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Self-Service Business Intelligence Tools Across Departments
Organizations are increasingly empowering non-technical users to access and analyze data independently, driving widespread adoption of Tableau licenses across business functions. This decentralization of analytics boosts license demand as companies seek scalable, user-friendly solutions for routine decision-making.
Expansion of Data Ecosystems Across Enterprises and Cloud Platforms
The proliferation of enterprise data from CRM, ERP, and IoT systems, along with the need for seamless integration with cloud platforms like AWS, Azure, and Google Cloud, is fueling demand for Tableau licenses that support diverse data sources and hybrid environments.
Emphasis on Real-Time Analytics and Faster Decision-Making Frameworks
Businesses require real-time dashboards and live data insights to monitor KPIs and respond quickly to operational issues, making Tableau's real-time analytics capabilities a key driver for license upgrades and long-term contracts.
Integration with AI-Driven Analytics and Predictive Modeling Platforms
The integration of Tableau with advanced analytics tools such as Python, R, and Einstein AI enables organizations to leverage predictive modeling and AI-powered insights, encouraging upgrades to premium license tiers and supporting higher renewal rates.
Transition Toward Subscription-Based Licensing Across Global Enterprises
The shift from perpetual licenses to subscription-based models aligns with enterprise preferences for predictable costs and regular feature updates, increasing recurring revenue streams and making Tableau licenses more accessible to a broader range of organizations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Tableau Service License Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Tableau Service License Market projected to grow between 2024 and 2032?
Which Tableau Service License Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Tableau Service License Market?
Who are the leading companies in the Tableau Service License Market?
Which region commanded the largest share of the Tableau Service License Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By License Type
- 1.2.1 Creator
- 1.2.2 Explorer
- 1.2.3 Viewer
- 1.3 By Deployment Mode
- 1.3.1 On-Premises
- 1.3.2 Cloud
- 1.4 By Enterprise Size
- 1.4.1 Small and Medium Enterprises
- 1.4.2 Large Enterprises
- 1.5 By End-User Industry
- 1.5.1 BFSI
- 1.5.2 Healthcare
- 1.5.3 Retail
- 1.5.4 IT and Telecommunications
- 1.5.5 Education
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,715.74 million → 2032: USD 3,656.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tableau Service License Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tableau Service License Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Tableau Service License Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Tableau Service License Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tableau Service License Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tableau Service License Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tableau Service License Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tableau Service License Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,715.74 million → 2032: USD 3,656.82 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tableau Service License Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By License Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Creator
- 12.3.7.2 Explorer
- 12.3.7.3 Viewer
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-Premises
- 12.4.7.2 Cloud
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Small and Medium Enterprises
- 12.5.7.2 Large Enterprises
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 BFSI
- 12.6.7.2 Healthcare
- 12.6.7.3 Retail
- 12.6.7.4 IT and Telecommunications
- 12.6.7.5 Education
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tableau Service License End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Tableau Service License Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Tableau Service License Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Tableau Service License Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Salesforce, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 IBM Corporation
- 18.5 Oracle Corporation
- 18.6 SAP SE
- 18.7 Amazon Web Services, Inc.
- 18.8 QlikTech International AB
- 18.9 TIBCO Software Inc.
- 18.10 MicroStrategy Incorporated
- 18.11 Sisense Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

