
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Environmentally Acceptable Lubricants Market Size 2024 | USD 3200 million |
| Environmentally Acceptable Lubricants Market, CAGR | 6.1% |
| Environmentally Acceptable Lubricants Market Size 2032 | USD 5138.93 million |
Market Overview:
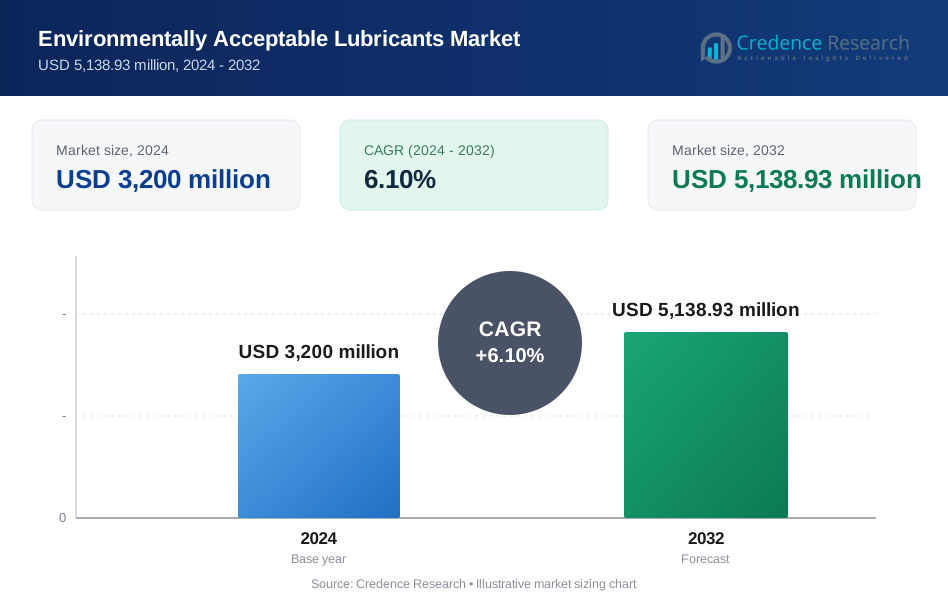
Environmentally Acceptable Lubricants Market size was valued at USD 3200 million in 2024 and is anticipated to reach USD 5138.93 million by 2032, at a CAGR of 6.1% during the forecast period (2024-2032).
The primary drivers of the Environmentally Acceptable Lubricants market include rising environmental concerns and regulatory measures pushing industries to adopt more sustainable solutions. Governments across the globe are imposing stricter environmental regulations, particularly in marine, automotive, and industrial applications, compelling businesses to switch to lubricants that have minimal impact on ecosystems. This is further amplified by international organizations advocating for sustainable practices. The growing trend toward renewable energy sources, alongside heightened consumer awareness of environmental impact, further accelerates demand for EALs. Moreover, advancements in bio-based materials and innovations in lubricant formulations are enabling the production of more efficient, high-performance EALs that cater to a wider range of applications. These developments offer an opportunity to improve performance while ensuring environmental protection.
Geographically, North America and Europe dominate the market due to stringent environmental regulations, high adoption rates of environmentally friendly products, and a strong industrial base. North America, in particular, benefits from the growing demand for EALs in marine and industrial sectors, driven by regulatory bodies such as the EPA (Environmental Protection Agency) that mandate the use of such lubricants in sensitive environments. Additionally, the growing number of companies in these regions are actively investing in sustainable technologies to comply with regulations. The Asia Pacific region is also expected to experience significant growth during the forecast period, driven by increasing industrialization, rising environmental awareness, and government initiatives aimed at reducing industrial pollution. As industries in this region shift towards more sustainable practices, the demand for EALs is anticipated to increase significantly, opening up new opportunities for market expansion.
Market Insights:
- The EALs market was valued at USD 3200 million in 2024 and is projected to reach USD 93 million by 2032, growing at a CAGR of 6.1%.
- Increasing environmental regulations, such as the U.S. EPA's Vessel General Permit and the EU's REACH regulations, are driving the adoption of EALs in marine, automotive, and industrial sectors.
- Consumer demand for eco-friendly products is influencing industries to develop and implement more sustainable lubrication solutions.
- Technological advancements in bio-based materials and lubricant formulations are enhancing the performance and efficiency of EALs.
- North America and Europe lead the market due to stringent environmental regulations and high adoption rates of environmentally friendly products.
- The Asia-Pacific region is experiencing significant growth, driven by industrialization and increasing environmental awareness.
- EALs are increasingly used in marine, automotive, and industrial applications, particularly in regions with stringent environmental regulations.
Market Drivers:
Environmental Regulations and Sustainability Initiatives:
One of the key drivers of the Environmentally Acceptable Lubricants (EAL) market is the growing emphasis on environmental regulations and sustainability. Governments worldwide are enforcing stricter environmental laws that demand businesses, especially in marine, automotive, and industrial sectors, to adopt eco-friendly alternatives. Regulations such as the U.S. Environmental Protection Agency’s (EPA) Vessel General Permit (VGP) and the European Union’s REACH regulations are pushing industries to switch to lubricants that minimize environmental risks. These regulations help reduce the environmental impact of lubricants in sensitive ecosystems, particularly in marine environments, where traditional lubricants often cause harm. The growing push for sustainability and environmentally responsible practices is compelling industries to shift toward more sustainable options.
Rising Consumer Demand for Eco-friendly Products:
Consumer awareness and demand for eco-friendly products are increasingly influencing the market for Environmentally Acceptable Lubricants. Today’s consumers are more conscious of their environmental footprint, and this shift in values is driving industries to develop and adopt more sustainable solutions. As public awareness grows, companies are responding by embracing EALs to align with consumer preferences for greener alternatives. For instance, the Environmental Protection Agency (EPA) has highlighted the adoption of biodegradable lubricants by marine and agricultural sectors to reduce ecological harm. In addition, many companies are now using environmentally acceptable lubricants as a way to enhance their brand reputation, catering to eco-conscious customers who prefer to support companies with sustainable practices.
Technological Advancements and Innovation:
Another significant driver is the continuous advancement in technology that has made the production of high-performance EALs possible. Innovations in bio-based materials and lubricant formulations have led to the creation of lubricants that are not only environmentally friendly but also offer improved performance, longer lifespan, and greater efficiency. For instance, research funded by the Organization for Economic Cooperation and Development (OECD) has led to advancements in synthetic esters and biodegradable additives, enabling the development of lubricants with superior oxidative stability and low-temperature fluidity. These innovations have expanded the potential applications of EALs in various sectors, including manufacturing, agriculture, and automotive, further boosting market demand.
Growing Industrialization and Focus on Green Manufacturing:
The ongoing industrialization in emerging economies, particularly in the Asia Pacific region, is also driving the demand for Environmentally Acceptable Lubricants. With rapid industrial growth, there is an increasing focus on adopting green manufacturing practices to minimize environmental impact. As industries in these regions become more aware of the importance of sustainability, the demand for EALs is expected to rise. This shift towards sustainable practices is supported by government policies and incentives encouraging the use of eco-friendly materials and processes, further fueling the adoption of EALs in manufacturing and heavy industries.
Market Trends:
Advancements in Biobased and Synthetic EALs:
The Environmentally Acceptable Lubricants (EALs) market is experiencing significant advancements in biobased and synthetic formulations. Innovations in additive chemistry and base oils, such as synthetic esters and vegetable oils, are enhancing the performance and biodegradability of EALs. These developments are crucial for meeting stringent environmental regulations and improving the efficiency of lubricants in various applications. Manufacturers are focusing on creating lubricants that not only meet environmental standards but also offer superior performance, longer service life, and better compatibility with modern machinery.
Integration of Digital Technologies:
The integration of digital technologies, including Internet of Things (IoT) sensors and artificial intelligence (AI), is transforming the EALs market. For instance, Rolls-Royce has implemented AIoT applications to reduce equipment downtime and improve operational efficiency, demonstrating how real-time monitoring and predictive maintenance can optimize lubricant performance and extend equipment life. These technologies enable real-time monitoring and predictive maintenance, leading to optimized lubricant performance and extended equipment life. AI-driven analytics are facilitating the development of high-performance EALs tailored to specific industrial needs, allowing for smarter, data-driven lubricant management. This trend is improving the operational efficiency of machinery, reducing downtime, and enhancing the environmental benefits of using EALs.
Expansion in Emerging Markets:
Emerging markets, particularly in the Asia-Pacific region, are experiencing rapid industrialization and increased environmental awareness, driving the demand for EALs. For instance, China is developing even more stringent legislation regarding emission norms and lubricant specifications than the U.S. and European Union, prompting industries to transition to eco-friendly lubricants. Countries like China and India are adopting stricter environmental regulations, prompting industries to transition to eco-friendly lubricants. As industrialization grows in these regions, there is a strong push toward sustainable practices, which in turn is creating significant growth opportunities for EAL manufacturers. The rising demand for environmentally responsible products is expected to propel the market expansion in these regions.
Growth in Marine and Agricultural Applications:
The marine and agricultural sectors are increasingly adopting EALs due to their environmental benefits and compliance with regulations. In the marine industry, EALs help prevent pollution in sensitive aquatic ecosystems, while in agriculture, they enhance equipment performance and reduce environmental impact. These sectors are key drivers in the adoption of EALs, as they align with global sustainability goals and environmental protection measures. The growth in these applications is contributing to the expanding use of EALs across various industries.
Market Challenges Analysis:
Regulatory Challenges:
The Environmentally Acceptable Lubricants (EALs) market faces significant regulatory hurdles as industries are required to comply with varying environmental standards across different regions. These regulations often involve complex testing protocols, product approval processes, and varying levels of scrutiny depending on the application. The evolving nature of environmental regulations, especially in marine, automotive, and industrial sectors, presents a challenge for manufacturers to ensure their products meet the required compliance while keeping production costs under control. As governments continue to implement stricter laws, companies must stay ahead of these changes and invest in continuous innovation to meet compliance demands. For instance, BioMax™ EALs are engineered with high-performance biodegradable base oils and eco-friendly additives to not only meet but exceed regulatory requirements, supporting companies in achieving both compliance and sustainability goals. Moreover, global trade barriers and differing regulatory environments can complicate the export of EALs to international markets. Companies need to navigate these regulatory differences to maintain competitiveness.
Cost and Performance Trade-offs:
While the demand for EALs is growing, the cost of producing these lubricants remains a significant challenge. Bio-based and synthetic lubricants often incur higher production costs compared to traditional petroleum-based products. Additionally, the performance characteristics of some EALs may not always match the high standards required for specific applications, such as heavy-duty machinery or extreme environmental conditions. Manufacturers must balance the need for superior performance with the increased costs of environmentally friendly materials, which can limit the widespread adoption of EALs in certain industries. This cost-performance trade-off may slow down the transition to greener alternatives in price-sensitive markets. Furthermore, the ongoing research and development required to enhance the performance of EALs increases the financial burden on manufacturers, impacting their profitability in the short term.
Market Opportunities:
The Environmentally Acceptable Lubricants (EALs) market presents significant growth opportunities driven by the increasing global focus on sustainability and environmental preservation. As industries face mounting pressure from governments and consumers to reduce their environmental impact, the demand for EALs is expected to rise substantially. This shift is particularly noticeable in sectors such as marine, automotive, and industrial manufacturing, where the use of eco-friendly lubricants is becoming more of a necessity due to stricter regulations. Companies that invest in the development of high-performance, bio-based, and biodegradable lubricants stand to gain a competitive edge by meeting these evolving regulatory requirements. The growing trend toward renewable energy sources and sustainability across the industrial landscape also supports the adoption of EALs as businesses seek to improve their environmental stewardship and align with consumer preferences for greener products.
Additionally, advancements in research and technology present opportunities for further market expansion. Innovations in lubricant formulations, such as the development of synthetic and hybrid EALs, enable manufacturers to offer products that not only meet environmental standards but also enhance performance in high-stress applications. This presents an opportunity for companies to diversify their product offerings and cater to a broader range of industries, including those in the heavy-duty and automotive sectors. As industries become more attuned to environmental concerns, the EALs market has the potential to witness increased adoption, with companies exploring new avenues for sustainable growth and product differentiation. The rising awareness and adoption of corporate social responsibility (CSR) practices further reinforce these market opportunities.
Market Segmentation Analysis:
By Type
The Environmentally Acceptable Lubricants (EALs) market is segmented by type into bio-based lubricants, synthetic lubricants, and semi-synthetic lubricants. Bio-based lubricants are derived from renewable sources like vegetable oils, and they are in high demand due to their biodegradability and low toxicity. Synthetic lubricants, produced using chemical processes, offer superior performance characteristics, such as high thermal stability and extended service life, making them suitable for demanding industrial applications. Semi-synthetic lubricants combine both bio-based and synthetic elements, offering a balanced performance profile with reduced environmental impact. The market's shift towards bio-based lubricants reflects increasing environmental consciousness among industries.
By Channel
The EALs market is primarily distributed through direct sales, distributors, and online channels. Direct sales allow manufacturers to build strong relationships with large industries, while distributors provide extensive reach, especially in regional markets. The online channel, although still emerging, is gaining traction due to the increasing demand for sustainable products and ease of access. E-commerce platforms and direct manufacturer websites have become essential for expanding market penetration and increasing visibility for EAL products.
By Application
EALs are widely used in marine, automotive, industrial, and other applications. In the marine sector, the stringent regulations governing water pollution push the demand for biodegradable lubricants. The automotive sector increasingly adopts EALs to comply with environmental standards and reduce carbon footprints. In industrial applications, EALs are used in machinery and equipment, with a focus on minimizing environmental hazards while maintaining optimal performance.
Segmentations:
By Type
- Bio-based lubricants
- Synthetic lubricants
- Semi-synthetic lubricants
By Channel
- Direct sales
- Distributors
- Online channels
By Application
- Marine
- Automotive
- Industrial
- Other applications
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for 35% of the global market. This dominance is driven by stringent environmental regulations and high industrial activity, particularly in sectors such as automotive, marine, and heavy machinery. The region's robust regulatory framework, coupled with increasing consumer demand for sustainable products, has resulted in a strong shift towards the adoption of bio-based and biodegradable lubricants. Companies in North America are increasingly investing in research and development to enhance the performance of EALs, ensuring compliance with growing environmental standards. Additionally, the presence of major manufacturers and suppliers in this region is contributing to the rapid adoption of EALs across various industries.
Europe
Europe follows closely with a 30% share of the global market. The region has a long-standing commitment to sustainability, reinforced by comprehensive environmental policies and regulations set by the European Union. This has led to the widespread adoption of EALs across various industries, especially in marine and automotive applications. In addition to regulatory drivers, European consumers are highly conscious of environmental impact, pushing manufacturers to adopt greener alternatives. Key players in Europe continue to innovate, offering advanced EAL formulations that meet the highest environmental standards, further strengthening their market position. Furthermore, Europe's investment in green infrastructure and sustainability goals further accelerates the transition to EALs.
Asia Pacific
Asia Pacific accounts for 25% of the EALs market, with rapid industrialization and increasing environmental awareness fueling demand. Countries such as China, Japan, and India are seeing a growing shift towards sustainable practices across industries, including automotive and manufacturing. The region's adoption of EALs is primarily driven by the need to comply with tightening environmental regulations and the rising popularity of renewable resources. As industrial growth continues, particularly in emerging economies, the demand for EALs is expected to expand further. This growth is also supported by the increasing investments in green technologies and the shift toward environmentally responsible business practices, positioning Asia Pacific as a key region for future growth.
Key Player Analysis:
- ExxonMobil
- Enviro Fluid
- Ecovis Lubricants
- Chevron
- BP Plc
- Castrol
- Klüber Lubrication
- Cargill Inc.
- Shell
- TotalEnergies
- Fuchs Petrolub AG
- Biolube
Competitive Analysis:
The Environmentally Acceptable Lubricants (EALs) market is highly competitive, with several key players leading the industry by offering innovative and sustainable solutions. Prominent companies such as ExxonMobil, Shell, and TotalEnergies dominate the global landscape, leveraging their established brand presence and extensive distribution networks. These companies are investing significantly in research and development to enhance the performance of their bio-based and synthetic lubricants, ensuring they meet the stringent regulatory standards required across various industries. Emerging players, particularly in North America and Europe, are focusing on bio-based lubricants, capitalizing on the growing demand for sustainable alternatives. Smaller companies are differentiating themselves by offering customized, niche products tailored to specific applications like marine or heavy-duty industrial machinery. Competitive strategies also include forming strategic partnerships, improving product formulations, and expanding global reach. The market's future growth will depend on continued innovation and the ability to align with environmental and regulatory requirements.
Recent Developments:
- In September 2024, Castrol India achieved a milestone by incorporating 50% recycled content in its HDPE lubricant bottles, aiming to replace 2,600 metric tonnes of virgin plastic by year-end as part of its PATH360 sustainability strategy.
Market Concentration & Characteristics:
The Environmentally Acceptable Lubricants (EALs) market exhibits moderate concentration, with a few key players commanding a significant share while allowing space for emerging companies focused on sustainability. Major multinational corporations such as ExxonMobil, Shell, and TotalEnergies dominate the market due to their extensive research and development capabilities, established distribution networks, and strong brand recognition. However, the increasing demand for eco-friendly solutions has led to a rise in smaller, specialized companies offering innovative bio-based and synthetic lubricants. This market is characterized by continuous innovation, as companies invest in improving product formulations to meet stringent environmental standards and performance requirements. The market’s growth is driven by regulatory pressures and consumer preference for sustainable products, resulting in heightened competition. Furthermore, partnerships and collaborations are becoming common as companies aim to strengthen their position in this evolving and environmentally focused industry.
Report Coverage:
The research report offers an in-depth analysis based on Type, Channel, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Environmentally Acceptable Lubricants (EALs) market is projected to experience robust growth, driven by increasing environmental regulations and a global shift towards sustainability.
- Advancements in biotechnology and material sciences are expected to lead to the development of high-performance, cost-effective EALs, enhancing their adoption across various industries.
- The marine sector is anticipated to remain a significant contributor to the EALs market, propelled by stringent international regulations and a heightened focus on reducing marine pollution.
- The automotive industry's transition towards electric vehicles (EVs) is likely to influence lubricant formulations, with a growing demand for specialized fluids tailored to EV requirements.
- Industrial applications, particularly in sectors like mining and agriculture, are expected to drive demand for EALs, as companies seek to minimize environmental impact while maintaining operational efficiency.
- Geographically, North America and Europe are projected to lead the market, bolstered by established regulatory frameworks and a strong emphasis on environmental sustainability.
- The Asia-Pacific region is anticipated to witness rapid growth, fueled by industrial expansion and increasing environmental awareness in countries like China and India.
- Collaborations between industry leaders and research institutions are likely to accelerate innovation in EAL technologies, fostering the development of next-generation lubricants.
- Consumer awareness and preference for eco-friendly products are expected to influence market dynamics, prompting manufacturers to prioritize sustainability in product offerings.
- Overall, the EALs market is poised for significant expansion, with opportunities arising from regulatory pressures, technological advancements, and shifting consumer preferences towards environmentally responsible solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Governments and international bodies are enforcing stricter environmental standards, particularly in marine, automotive, and industrial sectors, compelling companies to adopt lubricants that minimize ecological harm and comply with mandates such as the EPA's Vessel General Permit and the EU's REACH regulations.
Rising Consumer Preference for Sustainable Products
Growing consumer awareness and demand for eco-friendly products are pushing industries to switch to environmentally acceptable lubricants, both to meet market expectations and to enhance brand reputation through sustainable practices.
Technological Advancements in Lubricant Formulations
Innovations in bio-based materials and synthetic esters are enabling the development of high-performance, biodegradable lubricants that meet both environmental and operational requirements, expanding the range of applications for EALs.
Industrialization and Green Manufacturing Initiatives
Rapid industrial growth, especially in Asia Pacific, is accompanied by a shift toward green manufacturing practices, with governments incentivizing the adoption of eco-friendly lubricants to reduce industrial pollution and environmental impact.
Expansion of Marine and Agricultural Applications
The marine and agricultural sectors are increasingly adopting EALs to comply with regulations and reduce environmental risks, driving significant demand as these industries prioritize sustainability and operational efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Environmentally Acceptable Lubricants (EALs) market?
What is the projected market size for Environmentally Acceptable Lubricants by 2032?
What factors are driving the growth of the Environmentally Acceptable Lubricants market?
Which regions are leading the Environmentally Acceptable Lubricants market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Bio-based lubricants
- 1.2.2 Synthetic lubricants
- 1.2.3 Semi-synthetic lubricants
- 1.3 By Channel
- 1.3.1 Direct sales
- 1.3.2 Distributors
- 1.3.3 Online channels
- 1.4 By Application
- 1.4.1 Marine
- 1.4.2 Automotive
- 1.4.3 Industrial
- 1.4.4 Other applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,200 million → 2032: USD 5,138.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Environmentally Acceptable Lubricants Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Environmentally Acceptable Lubricants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Environmentally Acceptable Lubricants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Environmentally Acceptable Lubricants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Environmentally Acceptable Lubricants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Environmentally Acceptable Lubricants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Environmentally Acceptable Lubricants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Environmentally Acceptable Lubricants Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,200 million → 2032: USD 5,138.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Environmentally Acceptable Lubricants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bio-based lubricants
- 12.3.7.2 Synthetic lubricants
- 12.3.7.3 Semi-synthetic lubricants
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Channel - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Direct sales
- 12.4.7.2 Distributors
- 12.4.7.3 Online channels
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Marine
- 12.5.7.2 Automotive
- 12.5.7.3 Industrial
- 12.5.7.4 Other applications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Environmentally Acceptable Lubricants End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Environmentally Acceptable Lubricants Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Environmentally Acceptable Lubricants Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Environmentally Acceptable Lubricants Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ExxonMobil
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Shell
- 18.4 TotalEnergies
- 18.5 BP Plc
- 18.6 Castrol
- 18.7 Chevron
- 18.8 Klüber Lubrication
- 18.9 Fuchs Petrolub AG
- 18.10 Cargill Inc.
- 18.11 Biolube
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

