
Market Overview
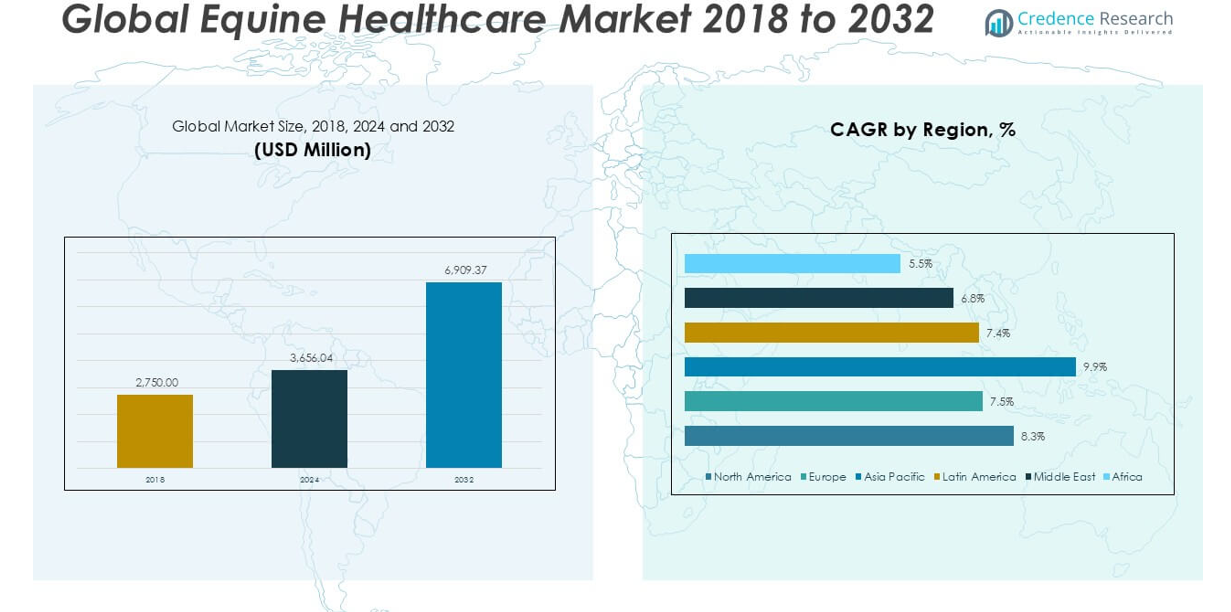
The Equine Healthcare Market size was valued at USD 2,750.00 million in 2018, increased to USD 3,656.04 million in 2024, and is anticipated to reach USD 6,909.37 million by 2032, growing at a CAGR of 8.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Equine Healthcare Market Size 2024 | USD 3,656.04 million |
| Equine Healthcare Market, CAGR | 8.31% |
| Equine Healthcare Market Size 2032 | USD 6,909.37 million |
The Equine Healthcare market is led by prominent players such as Zoetis, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco, IDEXX Laboratories, Inc., Dechra Pharmaceuticals, Ceva Sante Animale, Heska Corporation, Arthrex Inc., Esaote SPA, Covetrus Inc., and Cargill. These companies focus on expanding their product portfolios, advancing diagnostic technologies, and investing in preventive care solutions to strengthen their market position. North America dominates the global equine healthcare market, holding a substantial 39.8% market share in 2024, driven by the region’s robust veterinary infrastructure, high equine sports participation, and increasing adoption of advanced healthcare technologies.
Market Insights
- The Equine Healthcare market was valued at USD 2,750.00 million in 2018, reached USD 3,656.04 million in 2024, and is projected to hit USD 6,909.37 million by 2032, growing at a CAGR of 8.31% during the forecast period.
- The market is driven by the rising prevalence of equine diseases such as musculoskeletal disorders and parasitic infections, along with the growing demand for advanced diagnostics and preventive healthcare solutions.
- Increasing adoption of telehealth software, diagnostic test kits, and orthobiologic treatments are key trends transforming the equine healthcare landscape, particularly among sport and racing horses.
- North America holds the largest regional share at 39.8% in 2024, followed by Europe at 24.3% and Asia Pacific at 22.5%; the pharmaceuticals segment remains the leading product category.
- High treatment costs, limited veterinary access in rural areas, and regulatory complexities may restrain market expansion, particularly in developing regions.
Market Segmentation Analysis:
By Product
In the Equine Healthcare market, the pharmaceuticals segment holds the largest market share, driven by the growing prevalence of parasitic infections and musculoskeletal disorders among horses. Within pharmaceuticals, parasiticides dominate due to their critical role in preventing and managing parasitic infestations that significantly affect equine health and performance. Additionally, the rising demand for anti-infectives and anti-inflammatory drugs supports the segment’s growth. The diagnostics segment, particularly diagnostic test kits, is also witnessing steady expansion owing to increased emphasis on early disease detection. Advancements in telehealth software further contribute to improving equine health monitoring and remote consultations.
- For instance, Zoetis' QUEST PLUS Gel, a widely used equine dewormer, has been proven effective against 51 species and stages of equine parasites, enhancing parasite control protocols globally. Additionally, IDEXX Laboratories’ RealPCR testing platform processes over 2 million equine diagnostic tests annually, significantly contributing to faster and more accurate disease detection.
By Indication
Musculoskeletal disorders represent the dominant sub-segment in the equine healthcare market by indication, accounting for the largest revenue share. This dominance is primarily attributed to the high incidence of joint, tendon, and ligament injuries among sport and racing horses, which require continuous medical attention and preventive care. Additionally, parasitic infections hold a substantial share, driven by the need for regular deworming and parasite control. The growing awareness about equine viral diseases, such as equine herpes virus and equine influenza, further drives the demand for vaccines and diagnostic solutions, supporting the overall growth across multiple indications.
- For instance, Boehringer Ingelheim’s Legend (hyaluronate sodium) has been used in over 5 million joint treatments worldwide, offering effective management of equine joint diseases. Additionally, Merck Animal Health’s EQUINN vaccine provides protection against equine influenza and has been administered to thousands of horses globally, ensuring preventive care in competitive and recreational segments.
By Activity
The sports/racing segment leads the equine healthcare market by activity, holding the largest market share due to the significant healthcare investments required to maintain the performance and well-being of competitive horses. These horses frequently experience injuries and stress-related conditions, driving consistent demand for pharmaceuticals, diagnostics, and orthobiologic treatments. The recreation segment is also expanding, supported by increasing pet ownership and leisure horse-riding activities. However, sports and racing remain the primary drivers of advanced healthcare services and products in the market, as the economic and competitive stakes in this activity necessitate rigorous and ongoing veterinary care.
Market Overview
Rising Incidence of Equine Diseases
The increasing prevalence of equine diseases such as musculoskeletal disorders, parasitic infections, and viral conditions is a major driver for the equine healthcare market. These health issues demand continuous veterinary attention, regular vaccinations, and diagnostic testing to ensure the well-being of horses, especially those involved in racing and sports activities. The need for timely disease management and preventive care is driving the consumption of pharmaceuticals, vaccines, and diagnostic products, thereby accelerating market growth across both developed and emerging regions.
- For instance, Boehringer Ingelheim has distributed over 1.5 million doses of its Vetera vaccines annually to protect horses against equine influenza and West Nile Virus.
Growth in Equine Sports and Recreational Activities
The expansion of equine sports, racing events, and recreational horse-riding activities globally is significantly boosting the demand for advanced healthcare solutions. Competitive horses require rigorous health monitoring, injury management, and routine medical care to maintain peak performance. Rising investments by horse owners and equestrian facilities in preventive healthcare, rehabilitation, and performance enhancement are supporting the growth of pharmaceuticals, orthobiologics, and diagnostic services. This trend is especially prominent in regions with well-established equestrian industries such as North America and Europe.
- For instance, Arthrex Inc. has developed advanced regenerative therapies, including the Arthrex ACP (Autologous Conditioned Plasma) system, which has treated over 100,000 equine musculoskeletal injuries worldwide.
Increasing Adoption of Advanced Veterinary Technologies
Technological advancements in veterinary diagnostics, telehealth software, and practice management solutions are transforming equine healthcare. The availability of portable diagnostic equipment and telemedicine platforms enables timely consultations, accurate disease detection, and improved treatment outcomes. These innovations support better disease management, especially in remote areas with limited access to veterinary clinics. The integration of digital solutions into equine healthcare practices enhances operational efficiency and expands the accessibility of specialized care, further propelling market growth.
Key Trends & Opportunities
Growing Demand for Preventive Healthcare
There is a notable shift towards preventive healthcare among horse owners and veterinary professionals, aiming to reduce long-term treatment costs and improve animal welfare. Regular vaccination programs, routine diagnostics, and parasite control measures are gaining traction, creating opportunities for pharmaceutical companies and diagnostic kit manufacturers. This proactive approach is expected to generate sustained demand for high-quality vaccines, anti-parasitic drugs, and preventive diagnostic services across key markets.
- For instance, Covetrus Inc. supports preventive care programs through its equine wellness plans, servicing over 500,000 horses annually through its integrated veterinary network and digital platforms.
Expansion of E-commerce and Online Veterinary Services
The rising penetration of e-commerce platforms and the growth of online veterinary services present significant opportunities in the equine healthcare market. Horse owners increasingly prefer the convenience of purchasing pharmaceuticals, supplements, and diagnostic kits through digital channels. Additionally, telehealth platforms enable virtual consultations, remote diagnostics, and faster treatment initiation. This shift not only improves product accessibility but also allows veterinary service providers to expand their customer reach, particularly in underserved regions.
- For instance, Chewy’s online veterinary pharmacy has processed over 20,000 equine prescription orders monthly, offering direct-to-doorstep services across the United States. Moreover, Zoetis' Vetscan Imagyst platform, which supports AI-based fecal diagnostics, has been deployed in over 1,500 veterinary clinics globally, with more than 250,000 fecal samples processed through the system since its launch, enhancing rapid and remote diagnostic capabilities.
Key Challenges
High Cost of Equine Healthcare
One of the primary challenges in the equine healthcare market is the high cost associated with veterinary treatments, advanced diagnostics, and specialty pharmaceuticals. Expenses related to surgeries, orthobiologic therapies, and regular medical care can be prohibitive for many horse owners, especially in recreational segments. This financial burden may limit access to timely and comprehensive healthcare services, thereby restraining market growth in certain regions.
Limited Access in Rural and Remote Areas
Access to quality equine healthcare services remains a critical issue in rural and remote regions. Many horse owners in these areas face challenges in obtaining timely veterinary care, diagnostic testing, and pharmaceuticals due to a lack of specialized facilities and professionals. This limited access can lead to delayed treatments and increased disease prevalence, posing a significant barrier to market expansion and effective healthcare delivery.
Regulatory and Product Approval Complexities
Stringent regulatory frameworks governing animal health products, including vaccines and pharmaceuticals, can delay the introduction of new therapies in the equine healthcare market. Compliance with diverse national and international standards adds to the complexity and cost of product development. These regulatory hurdles often result in prolonged approval timelines and may restrict smaller companies from entering the market, thereby limiting product availability and innovation.
Regional Analysis
North America
North America dominates the Equine Healthcare market, holding the largest market share of approximately 39.8% in 2024. The market was valued at USD 1,107.15 million in 2018 and is projected to reach USD 2,747.87 million by 2032, growing at a robust CAGR of 8.3%. This growth is primarily driven by the high prevalence of equine sports and racing, substantial investments in veterinary healthcare, and the widespread adoption of advanced diagnostic and treatment technologies. The region's well-established veterinary infrastructure and increasing awareness about preventive equine care further contribute to North America's market leadership.
Europe
Europe accounts for a significant 24.3% market share in 2024, with its equine healthcare market valued at USD 695.75 million in 2018 and expected to reach USD 1,580.54 million by 2032, growing at a CAGR of 7.5%. The market is driven by a strong equestrian culture, government support for animal welfare, and a growing emphasis on equine disease management. Increased spending on recreational and competitive horse activities further supports market growth. The rising demand for diagnostic solutions and pharmaceuticals is enhancing the regional market's competitiveness, with countries like Germany, France, and the UK leading this expansion.
Asia Pacific
Asia Pacific is emerging as the fastest-growing region in the Equine Healthcare market, holding a 22.5% market share in 2024. The market was valued at USD 588.50 million in 2018 and is anticipated to reach USD 1,744.52 million by 2032, registering a CAGR of 9.9%. Rapid economic growth, increasing horse ownership, and expanding recreational equestrian activities across China, India, and Australia are key growth drivers. Additionally, improving access to veterinary care and growing awareness of preventive healthcare measures are strengthening market potential. The region's dynamic growth presents significant opportunities for healthcare providers and veterinary pharmaceutical companies.
Latin America
Latin America holds a 7.1% market share in 2024 in the Equine Healthcare market. The market size stood at USD 195.80 million in 2018 and is expected to reach USD 456.50 million by 2032, growing at a CAGR of 7.4%. The market is primarily supported by the growing popularity of equestrian sports and recreational activities, especially in countries like Brazil and Argentina. Increasing awareness of animal health, coupled with gradual improvements in veterinary infrastructure, is positively impacting market growth. However, limited access to advanced equine treatments in rural areas continues to present a challenge for the regional market.
Middle East
The Middle East represents a 4.2% market share in 2024 in the Equine Healthcare market. The regional market was valued at USD 94.88 million in 2018 and is projected to reach USD 197.65 million by 2032, expanding at a CAGR of 6.8%. The region’s market growth is primarily driven by the high cultural and economic value placed on horses, particularly in Gulf countries where equestrian sports such as endurance racing are prominent. Increasing investment in veterinary services and infrastructure, along with a growing focus on preventive care and specialized pharmaceuticals, is supporting steady market expansion in the Middle East.
Africa
Africa holds the smallest share of the Equine Healthcare market with 3.1% in 2024. The market was valued at USD 67.93 million in 2018 and is expected to grow to USD 182.30 million by 2032, at a CAGR of 5.5%. The region’s growth is driven by increasing awareness of equine disease management and a gradual improvement in veterinary care access. However, limited availability of advanced healthcare facilities and pharmaceuticals continues to constrain market growth. Despite these challenges, the growing equestrian communities in countries such as South Africa are expected to contribute to the steady development of the equine healthcare sector.
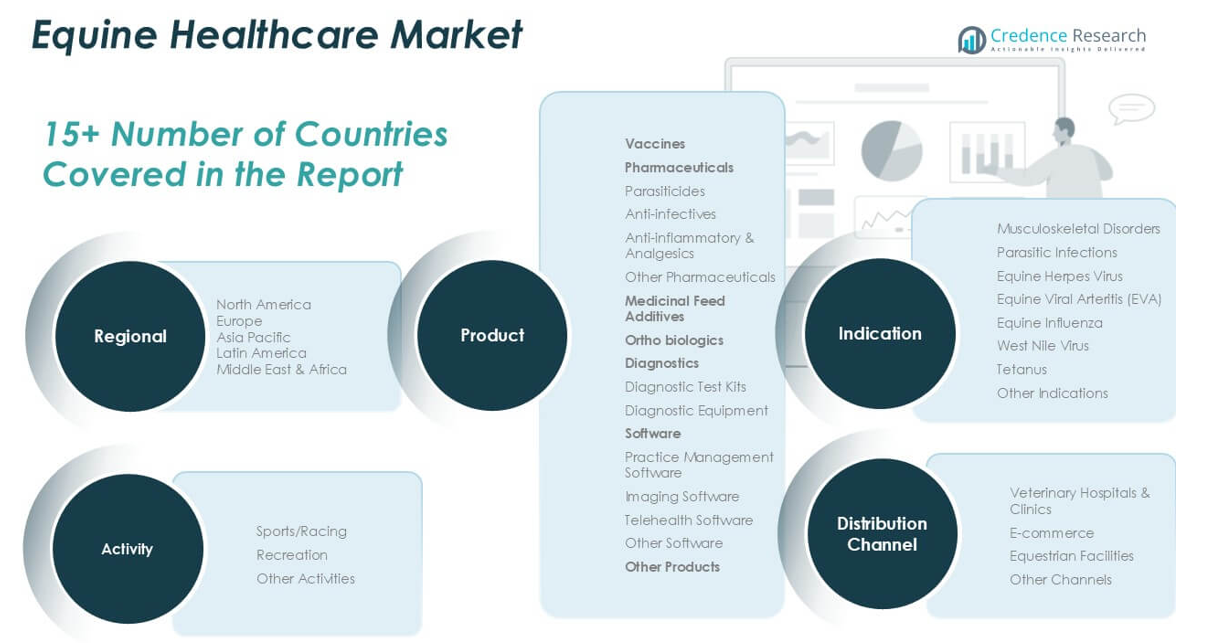
Market Segmentations:
By Product
- Vaccines
- Pharmaceuticals
- Parasiticides
- Anti-infectives
- Anti-inflammatory & Analgesics
- Other Pharmaceuticals
- Medicinal Feed Additives
- Orthobiologics
- Diagnostics
- Diagnostic Test Kits
- Diagnostic Equipment
- Software
- Practice Management Software
- Imaging Software
- Telehealth Software
- Other Software
- Other Products
By Indication
- Musculoskeletal Disorders
- Parasitic Infections
- Equine Herpes Virus
- Equine Viral Arteritis (EVA)
- Equine Influenza
- West Nile Virus
- Tetanus
- Other Indications
By Activity
- Sports/Racing
- Recreation
- Other Activities
By Distribution Channel
- Veterinary Hospitals & Clinics
- E-commerce
- Equestrian Facilities
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The equine healthcare market is highly competitive, with several key players focusing on expanding their product portfolios and strengthening their global presence. Leading companies such as Zoetis, Boehringer Ingelheim, Merck & Co., and Elanco dominate the market, offering a wide range of pharmaceuticals, vaccines, and diagnostic solutions tailored for equine care. These players actively engage in strategic partnerships, acquisitions, and product innovations to maintain their market leadership. Companies like IDEXX Laboratories and Heska Corporation focus on advancing diagnostic technologies, while Arthrex and Ceva Sante Animale emphasize orthopedic and therapeutic solutions. The market also witnesses growing competition from emerging players leveraging e-commerce platforms and telehealth services to improve product accessibility. Continuous investment in research and development, particularly in preventive care and digital veterinary solutions, remains a key competitive strategy across the industry. The presence of both multinational corporations and specialized veterinary companies creates a dynamic and evolving competitive landscape within the equine healthcare sector.
Key Player Analysis
- Zoetis
- Arthrex Inc.
- Dechra Pharmaceuticals
- Boehringer Ingelheim International GmbH
- Ceva Sante Animale
- Heska Corporation
- Merck & Co. Inc
- Esaote SPA
- IDEXX Laboratories, Inc.
- Covetrus Inc.
- Elanco
- Cargill
Recent Developments
- In May 2025, Zoetis announced the opening of its largest U.S. diagnostics reference laboratory in Louisville, Kentucky. This state-of-the-art facility is designed to deliver faster, more precise, and more accessible diagnostic testing for veterinarians, including services relevant to equine health. The lab will be fully operational by the end of 2025, enhancing Zoetis’ capacity for cytology, chemistry, hematology, microbiology, and more.
- In July 2024, San Giovanni Battista Hospital of Rome announced that their equine-assisted therapy program helped in improving motor skills in over 600 neurology patients.
- In June 2024, Hartpury University along with AnimalWeb launched a new research study aimed at mapping the biosecurity practices in the equine industry of UK. This study will help in shaping equine health-related policies in the country.
- In June 2024, Merck Animal Health and US Trotting Association announced installation milestone of over 50,000 Bio-Thermo microchips in race horses. These microchips assist the horse owners in accurately and remotely monitoring health parameters like temperature and also help in recordkeeping.
- In May 2024, Curative Sounds launched a novel product for companion and equine patients, Extracorporeal Shockwave Therapy (ESWT) device. This is considered world’s first portable ESWT device and is applicable in treating musculoskeletal disorders.
- In May 2024, Mixlab acquired NexGen Animal Health. This acquisition was done by Mixlab to expand their existing pharmacy services beyond companion animals and into large animals like horse and cattle.
Market Concentration & Characteristics
The Equine Healthcare Market is moderately concentrated, with a mix of global leaders and regional players actively competing to strengthen their market presence. It demonstrates strong product diversity, covering pharmaceuticals, vaccines, diagnostics, and software solutions tailored for equine care. Leading companies focus on expanding their portfolios and introducing advanced diagnostic technologies to meet the evolving healthcare needs of sport, racing, and recreational horses. The market shows high entry barriers due to strict regulatory frameworks, extensive product approval processes, and significant investment requirements in research and development. North America holds the largest share, supported by established veterinary infrastructure and a well-developed equine sports industry. The market benefits from growing awareness of preventive healthcare and increasing demand for specialized equine treatments. It relies heavily on veterinary hospitals, clinics, and e-commerce platforms to ensure product accessibility. While the market presents growth opportunities through innovation and expanding telehealth solutions, high treatment costs and limited veterinary access in rural areas continue to challenge its full potential.
Report Coverage
The research report offers an in-depth analysis based on Product, Indication, Activity, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The equine healthcare market is expected to experience steady growth driven by increasing investments in equine sports and recreational activities.
- Demand for advanced pharmaceuticals and orthobiologic treatments will continue to rise as owners prioritize the health and performance of their horses.
- The adoption of telehealth software and remote diagnostic technologies is likely to accelerate, improving accessibility to veterinary care.
- Preventive healthcare practices such as regular vaccinations, parasite control, and routine diagnostics will gain wider acceptance among horse owners.
- The pharmaceutical segment, particularly parasiticides and anti-infectives, is projected to maintain its dominance due to their essential role in equine care.
- North America will remain the leading region, supported by strong veterinary infrastructure and high equine healthcare spending.
- The Asia Pacific region is expected to emerge as the fastest-growing market, driven by increasing horse ownership and expanding equestrian activities.
- E-commerce platforms will play a growing role in the distribution of equine healthcare products, improving accessibility and convenience.
- Rising awareness about equine viral diseases will boost the demand for effective vaccines and diagnostic solutions.
- High treatment costs and limited access to specialized care in rural areas may continue to challenge the market's growth potential.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Equine Diseases
The increasing prevalence of musculoskeletal disorders, parasitic infections, and viral diseases among horses necessitates ongoing veterinary care, regular vaccinations, and diagnostic testing, thereby fueling demand for pharmaceuticals and healthcare services.
Growth in Equine Sports and Recreational Activities
Expanding participation in equine sports, racing, and recreational riding globally drives significant investment in advanced healthcare solutions, as competitive and leisure horses require rigorous health monitoring and preventive care.
Technological Advancements in Veterinary Diagnostics and Telehealth
Innovations such as portable diagnostic equipment, telehealth software, and AI-based diagnostic platforms are improving disease detection, treatment outcomes, and access to specialized care, especially in remote or underserved regions.
Shift Toward Preventive Healthcare
Horse owners and veterinarians are increasingly adopting preventive healthcare practices, including routine vaccinations, parasite control, and regular diagnostics, to reduce long-term treatment costs and improve animal welfare, supporting sustained market growth.
Expansion of E-commerce and Online Veterinary Services
The growing use of e-commerce platforms and online veterinary services enhances accessibility to pharmaceuticals, supplements, and diagnostic kits, making it easier for horse owners to obtain necessary healthcare products and services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Equine Healthcare Market?
What factors are driving the growth of the Equine Healthcare Market?
What are some challenges faced by the Equine Healthcare Market?
are the major players in the Equine Healthcare Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Vaccines
- 1.2.2 Pharmaceuticals
- 1.2.3 Medicinal Feed Additives
- 1.2.4 Orthobiologics
- 1.2.5 Diagnostics
- 1.2.6 Software
- 1.3 By Activity
- 1.3.1 Sports/Racing
- 1.3.2 Recreation
- 1.3.3 Other Activities
- 1.4 By Indication
- 1.4.1 Musculoskeletal Disorders
- 1.4.2 Parasitic Infections
- 1.4.3 Equine Herpes Virus
- 1.4.4 Equine Influenza
- 1.4.5 West Nile Virus
- 1.4.6 Other Indications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,656.04 million → 2032: USD 6,909.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Equine Healthcare Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Equine Healthcare Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Equine Healthcare Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Equine Healthcare Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Equine Healthcare Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Equine Healthcare Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Equine Healthcare Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Equine Healthcare Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,656.04 million → 2032: USD 6,909.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Equine Healthcare Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vaccines
- 12.3.7.2 Pharmaceuticals
- 12.3.7.3 Medicinal Feed Additives
- 12.3.7.4 Orthobiologics
- 12.3.7.5 Diagnostics
- 12.3.7.6 Software
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Activity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sports/Racing
- 12.4.7.2 Recreation
- 12.4.7.3 Other Activities
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Musculoskeletal Disorders
- 12.5.7.2 Parasitic Infections
- 12.5.7.3 Equine Herpes Virus
- 12.5.7.4 Equine Influenza
- 12.5.7.5 West Nile Virus
- 12.5.7.6 Other Indications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Equine Healthcare Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Equine Healthcare Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Equine Healthcare Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Zoetis
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Boehringer Ingelheim International GmbH
- 17.4 Merck & Co., Inc.
- 17.5 Elanco
- 17.6 IDEXX Laboratories, Inc.
- 17.7 Dechra Pharmaceuticals
- 17.8 Ceva Sante Animale
- 17.9 Heska Corporation
- 17.10 Arthrex Inc.
- 17.11 Covetrus Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

