
Market Overview:
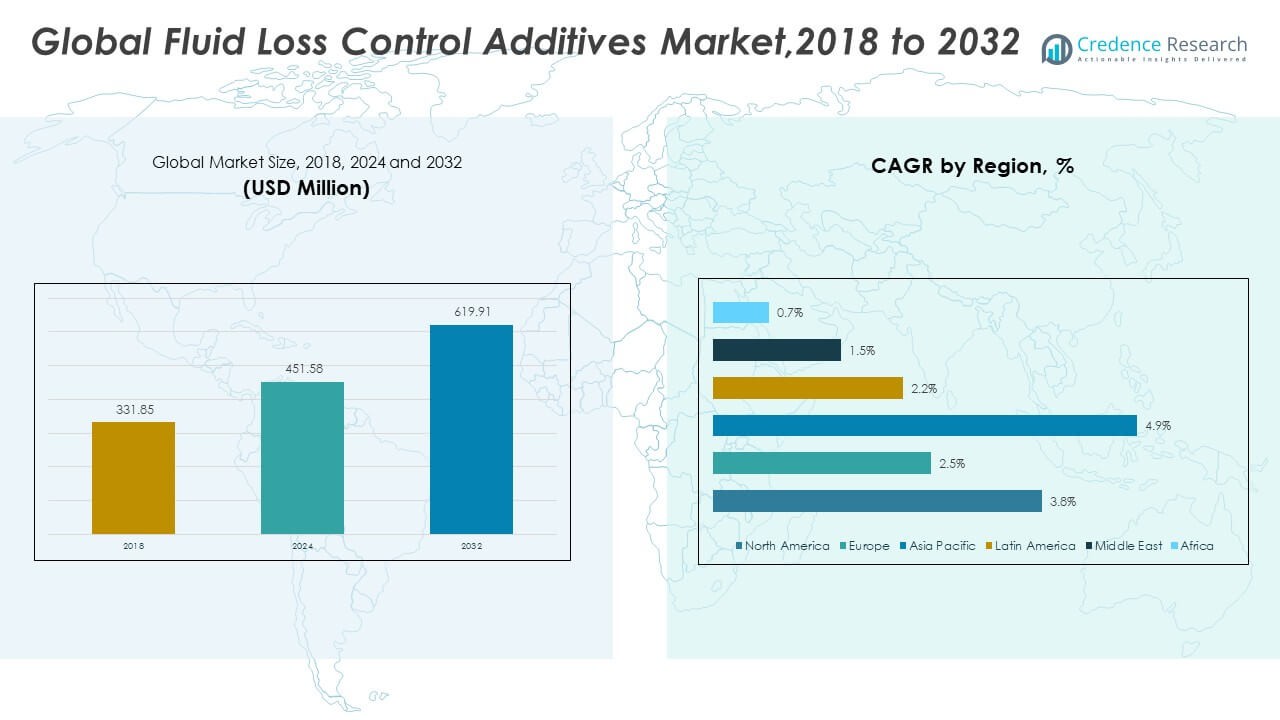
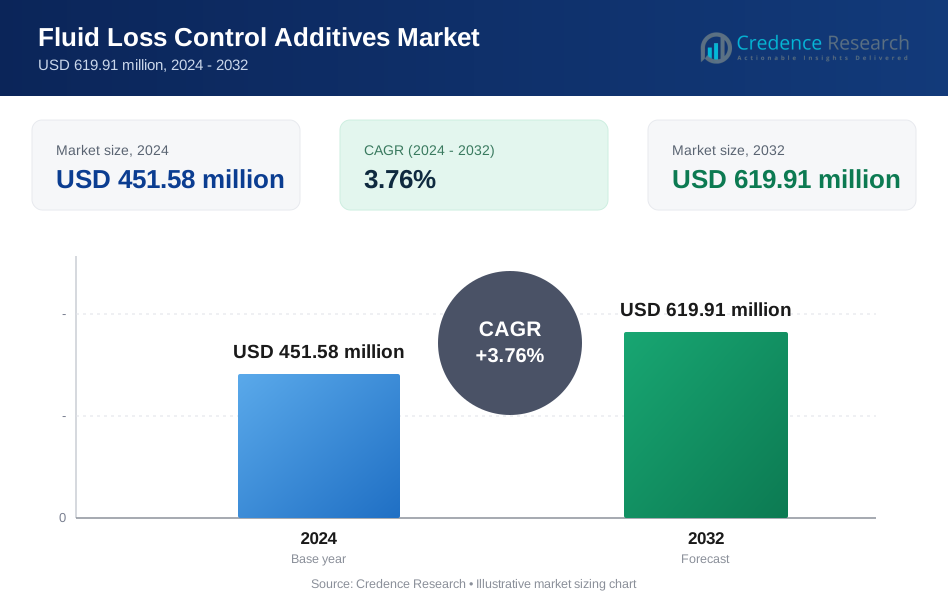
The Global Fluid Loss Control Additives Market size was valued at USD 331.85 million in 2018 to USD 451.58 million in 2024 and is anticipated to reach USD 619.91 million by 2032, at a CAGR of 3.76% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fluid Loss Control Additives Market Size 2024 | USD 451.58 Million |
| Fluid Loss Control Additives Market, CAGR | 3.76% |
| Fluid Loss Control Additives Market Size 2032 | USD 619.91 Million |
Growing drilling activity across conventional and unconventional fields drives steady demand for fluid loss control additives. Operators use these additives to protect wellbore stability and prevent formation damage. Shale development pushes higher use of polymers, specialty blends, and high-temperature formulations. Deeper wells and complex reservoirs lift the need for advanced additives that improve mud performance under pressure. Service companies invest in products that offer better filtration control and higher compatibility with modern drilling fluids. Many oil and gas players adopt performance-focused additives to reduce downtime and safeguard completion quality.
North America leads this market due to strong shale activity, mature service networks, and continuous drilling innovation. The U.S. maintains a dominant role because of its large unconventional reserves and high well counts. The Middle East also holds a key position supported by long-term upstream investment and complex reservoir conditions. Asia Pacific shows rising growth as countries expand offshore programs and national oil firms scale drilling plans. Latin America emerges as another growth zone driven by deep-water exploration and new licensing rounds. Europe advances at a moderate pace due to steady North Sea development and increased focus on drilling efficiency.
Market Insights:
- The Global Fluid Loss Control Additives Market was valued at USD 331.85 million in 2018, reached USD 451.58 million in 2024, and is projected to hit USD 619.91 million by 2032, growing at a CAGR of 3.76% driven by deeper wells and rising shale activity.
- North America (43.3%), Asia Pacific (30.4%), and Europe (17.5%) hold the top regional shares due to strong shale drilling, expanding offshore programs, and steady North Sea redevelopment.
- Asia Pacific, the fastest-growing region with a 4% share, accelerates through offshore expansion, rising national oil company drilling plans, and increased investment in deep-water assets.
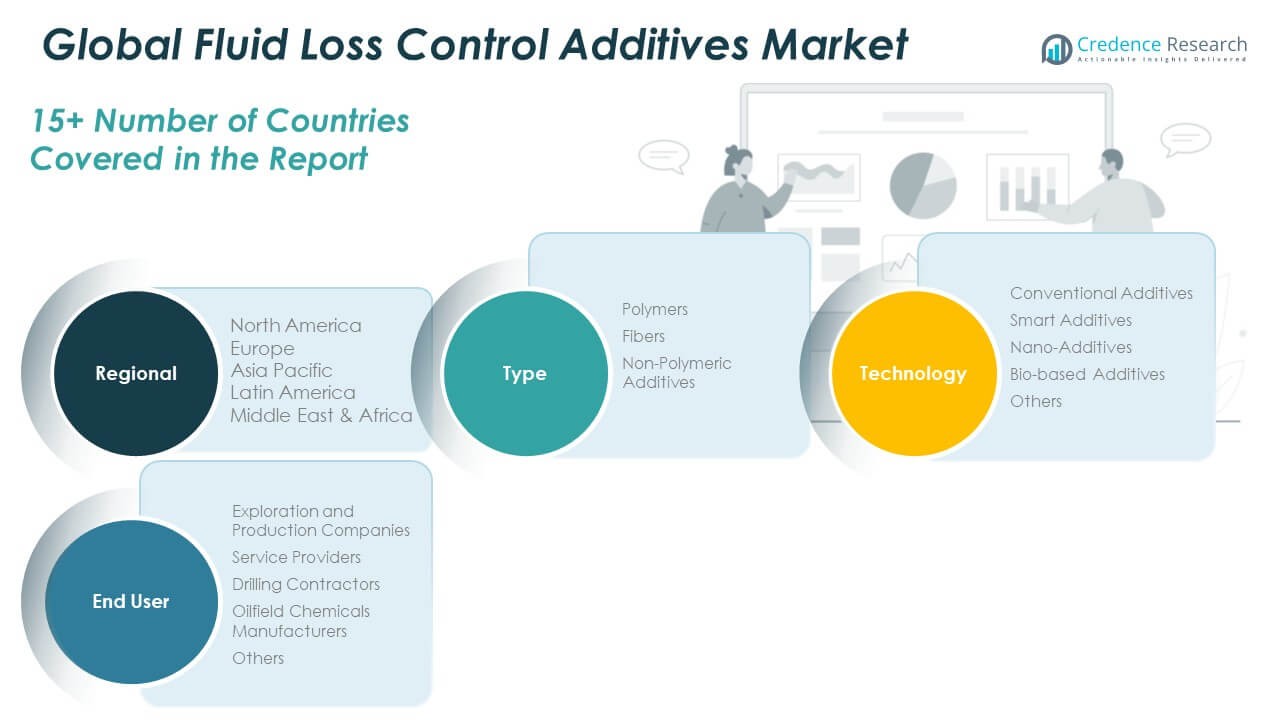
- The chart indicates Polymers dominate with roughly 60% share, supported by high compatibility and stable filtration control across varied drilling fluids.
- Fibers account for about 25–30%, while Non-Polymeric Additives contribute 15%, reflecting their selective use in mechanical plugging and cost-effective drilling requirements.
Market Drivers:
Rising Need For High-Performance Additives In Complex Drilling Programs
The Global Fluid Loss Control Additives Market expands due to higher drilling activity in deeper and hotter zones. Operators depend on engineered additives to maintain mud stability during long drilling cycles. High-pressure wells require blends that protect formation layers without harming permeability. The shift toward unconventional fields lifts demand for polymers that deliver tighter filtration control. Many service companies redesign additive systems to match harsh reservoir conditions. Growing drilling programs across shale zones strengthen the need for robust additives. Many producers invest in R&D to reach better compatibility with new mud chemistries. This wider use of advanced formulations supports steady growth across multiple upstream clusters.
- For instance, Halliburton deployed its “BaraHib® Nano” system which uses nanoparticle-enabled fluid technology to stabilize the wellbore in complex formations. This wider use of advanced formulations supports steady growth across multiple upstream clusters.
Growing Adoption Of Wellbore Stability Tools To Lower Formation Damage
Many operators invest in additives that protect the wellbore from fluid invasion in complex formations. The Global Fluid Loss Control Additives Market gains support through wider interest in solutions that reduce drilling risks. Many fields require blends that keep cuttings transport stable while avoiding unwanted fluid loss. Rising use of synthetic polymers boosts the performance of water-based and oil-based mud systems. Service groups focus on blends that help reduce downtime during drilling operations. Growth in high-angle and extended-reach wells drives adoption of stronger filtration tools. Many regions push for stable well integrity to support faster completion cycles. This driver strengthens adoption of premium-grade additives across global drilling activity.
- For instance, Halliburton’s BaraFLC® Nano-1 sealant delivered very low filtration rates and reduced pressure transmission in shale formations, enabling efficient drilling and protection of wellbore stability under challenging downhole stresses.
Expansion Of Unconventional Oil And Gas Fields Boosting Additive Demand
Unconventional fields push operators to adopt fluid loss control additives that maintain mud quality under stress. The Global Fluid Loss Control Additives Market benefits from this steady shift toward shale and tight reservoirs. Many drilling teams adopt advanced systems that support longer horizontal sections. Higher well counts in shale zones lift consumption of thermal-resistant and salt-tolerant additives. Operators require stable filtration agents that maintain viscosity for longer periods. New well designs increase the pressure on producers to deliver additives with stronger performance metrics. Service firms introduce blends that match local geological needs. Unconventional development continues to raise additive use across major basins.
Increased Investment In Advanced Drilling Technologies And Automation
Growing digitization in drilling operations fuels demand for additives that align with automated mud systems. The Global Fluid Loss Control Additives Market benefits from this move toward integrated drilling platforms. Automated units need stable additives that hold performance across dynamic circulation cycles. Many producers design blends that work well with digital flow-control tools. Rising use of real-time data pushes drilling teams to pick additives with predictable behavior. New rigs adopt monitoring tools that assess fluid behavior more closely. Many operators target improved operational efficiency through advanced mud engineering. This driver strengthens long-term interest in innovative additive chemistries.
Market Trends:
Shift Toward Eco-Friendly And Low-Toxicity Additive Formulations
Sustainability initiatives shift industry interest toward greener additive solutions. The Global Fluid Loss Control Additives Market aligns with a growing preference for low-toxicity polymer systems. Many producers redesign formulations to match strict regional environmental rules. Demand increases for additives that support safer disposal and lower ecological impact. Operators choose materials that limit harmful residue during drilling. Many companies test biodegradable components that hold stable performance under pressure. Rising environmental audits influence product selection during major drilling campaigns. This trend reshapes development strategies across leading chemical suppliers.
- For instance, a 2022 peer-reviewed study formulated a nanobiodegradable drilling fluid using plant-based waste materials and nanoparticles, achieving stable fluid loss control while reducing environmental footprint relative to conventional additives.
Expansion Of High-Temperature And High-Pressure Additive Portfolios
Modern wells require additives that perform in extreme thermal and pressure conditions. The Global Fluid Loss Control Additives Market shifts toward advanced blends that remain stable in deep reservoirs. Many chemical firms invest in products that handle unpredictable formation behavior. Operators need systems that provide consistent filtration control in harsh zones. High-temperature polymers gain traction across deep-water and geothermal wells. Many developers build tailored solutions for complex rock structures. New projects target stronger resistance to degradation under pressure. This trend drives innovation across several drilling regions.
- For instance, Halliburton’s BaraXcel™ non-aqueous fluid system enabled safe drilling in a 315 °F reservoir, prevented stuck-pipe incidents, and saved 55 rig-hours during high-overbalance operations.
Growing Integration Of Digital Tools To Evaluate Additive Performance
Digital monitoring tools shape how operators select additives for drilling programs. The Global Fluid Loss Control Additives Market adapts to real-time analytics that help optimize fluid behavior. Many rigs use sensors that track mud parameters during drilling. Producers use this data to improve additive design and strengthen predictive accuracy. Automated control systems assess fluid loss performance across cycles. Many firms use machine learning to identify the best additives for each geological profile. Real-time dashboards help operators fine-tune additive concentration. This trend brings higher precision to drilling operations.
Rising Demand For Multi-Functional Additives With Broad Compatibility
Operators request additives that deliver multiple functions across varied mud systems. The Global Fluid Loss Control Additives Market sees demand for blends that offer both filtration control and rheology support. Many service firms design materials that work across fresh water, brines, and synthetic fluids. Producers develop solutions that streamline inventory and lower operational complexity. Many wells require additives that sustain stability across wide temperature ranges. New systems improve bonding at the wellbore face for stronger protection. Multi-functional designs help cut additive consumption. This trend improves cost control for drilling teams.
Market Challenges Analysis:
Performance Limitations Under Harsh Conditions And Complex Geological Formations
Many wells face harsh temperature and pressure zones that limit additive efficiency. The Global Fluid Loss Control Additives Market deals with gaps in performance when drilling shifts into deeper or more unstable formations. Additives may degrade under extreme thermal stress, which weakens mud quality. Operators face issues when formation properties vary across drilling stages. Many products require frequent adjustments to keep filtration stable. Some blends create compatibility gaps in mixed mud systems. Unpredictable downhole behavior increases project risk. These constraints push service firms to upgrade additive chemistry.
Regulatory Pressure, Cost Volatility, And Supply Chain Instability
Strict regional rules raise pressure on producers to redesign additive compositions. The Global Fluid Loss Control Additives Market reaches supply chain hurdles when raw material availability shifts. Price swings in chemicals disrupt production schedules for many suppliers. Some producers face delays due to global transport issues. Compliance processes increase operational costs during product qualification. Many operators seek cheaper alternatives when budgets tighten. Supply inconsistency lowers confidence in long-term additive planning. These challenges push companies to improve sourcing resilience.
Market Opportunities:
Rising Investment In Unconventional And Deep-Water Exploration Programs
Unconventional drilling zones bring strong opportunities for advanced additive suppliers. The Global Fluid Loss Control Additives Market gains attractive openings as operators plan more horizontal wells. Many deep-water fields require high-performance additives that withstand severe downhole conditions. Growth in long-lateral well programs lifts interest in polymer blends with stronger thermal resistance. Producers can expand through tailored solutions for complex reservoirs. New regional licensing rounds create more pathways for market entry. This opportunity encourages chemical firms to accelerate product development.
Growing Demand For Eco-Safe Additives And Digital-Enabled Drilling Solutions
Sustainability goals push operators toward cleaner formulations with lower toxicity. The Global Fluid Loss Control Additives Market benefits from this shift toward greener drilling practices. Many companies seek biodegradable additives that keep filtration stable. Digital drilling tools create openings for additives that support automated fluid control. Firms can build solutions with predictable behavior for sensor-guided systems. More producers move into hybrid additive technologies that offer multi-functional performance. This opportunity strengthens long-term growth potential for innovation-focused suppliers.
Market Segmentation Analysis:
By Type
The Global Fluid Loss Control Additives Market expands across three core material categories that support diverse drilling needs. Polymers lead the segment due to strong filtration control and wide compatibility with drilling fluids. Fibers gain traction where mechanical plugging strength improves wellbore protection in unstable zones. Non-polymeric additives hold steady demand with applications in mature fields that require cost-effective control solutions. Each type supports field operators through targeted performance benefits that align with complex drilling conditions.
- For instance, industry research on nano-additives demonstrated that adding nanoparticles at 0.6 parts per billion (ppb) to water-based drilling fluids reduced filtrate loss by ~60% while increasing yield stress and plastic viscosity significantly—highlighting how nanotechnology enhances performance over traditional base materials.
By Technology
Technology-driven segmentation highlights rising interest in advanced additive systems. Conventional additives maintain broad industry use due to predictable performance in standard wells. Smart additives grow as drilling teams adopt solutions that adjust behavior under shifting downhole conditions. Nano-additives gain attention through higher surface activity and improved dispersion. Bio-based additives offer value for operators pursuing sustainability goals without lowering efficiency. Other emerging technologies provide niche support for specialized drilling programs across various geologies.
- For instance, recent lab trials combining nanoparticles with bio-organic materials achieved stable fluid loss control and improved rheology under high-salinity and temperature conditions, pointing to scalable alternatives for environmentally sensitive drilling sites.
By End User
End-user segmentation reflects demand patterns across upstream operations. Exploration and production companies rely on these additives to protect well integrity during challenging drilling cycles. Service providers integrate engineered blends into customized fluid systems for field deployment. Drilling contractors use stable additive packages to maintain operational efficiency across rigs. Oilfield chemical manufacturers expand portfolios to match evolving reservoir needs. Other end users adopt selective solutions that enhance fluid performance in targeted operating environments.
Segmentation:
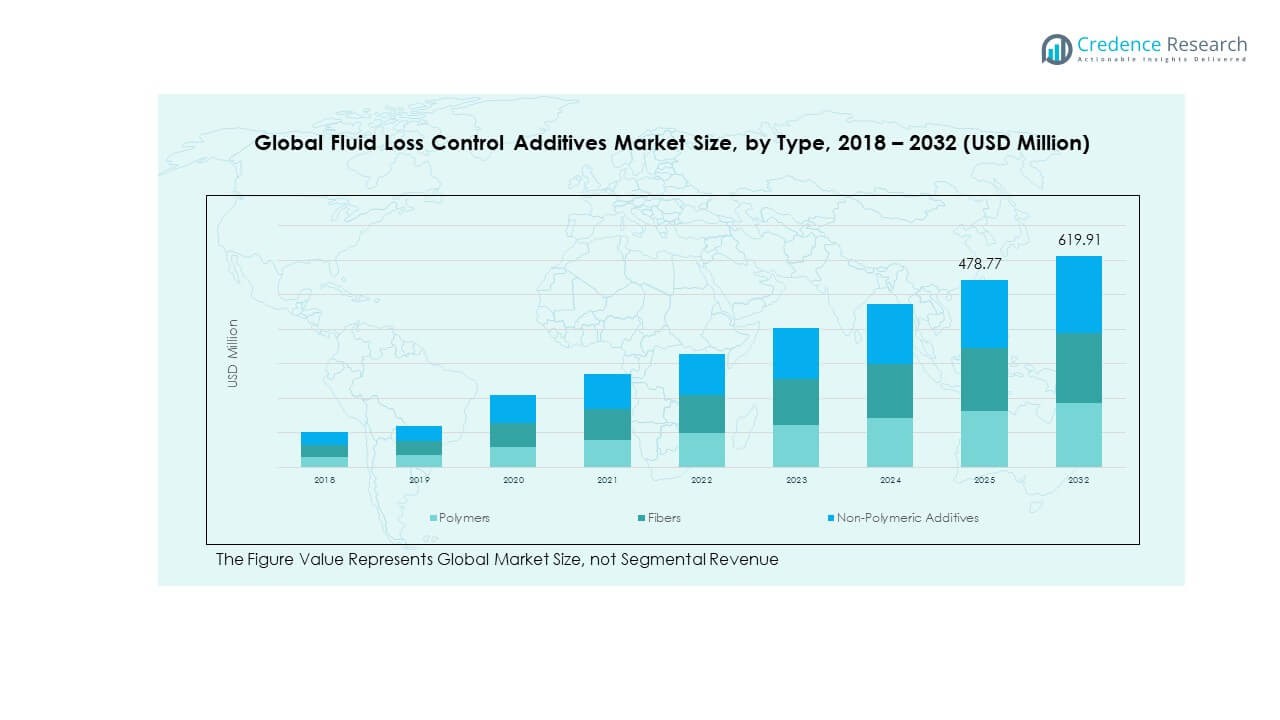
By Type- Polymers
- Fibers
- Non-Polymeric Additives
By Technology
- Conventional Additives
- Smart Additives
- Nano-Additives
- Bio-based Additives
- Others
By End User
- Exploration and Production Companies
- Service Providers
- Drilling Contractors
- Oilfield Chemicals Manufacturers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherland
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Fluid Loss Control Additives Market size was valued at USD 145.19 million in 2018 to USD 195.52 million in 2024 and is anticipated to reach USD 269.14 million by 2032, at a CAGR of 3.8% during the forecast period. North America holds the largest regional market share at 43.3%. The Global Fluid Loss Control Additives Market grows in this region due to strong shale drilling programs and steady investment in advanced mud systems. The U.S. leads activity with high well counts across major basins. Canada supports growth through conventional developments and workover activity. Service companies expand product portfolios to match deeper and more complex wells. Many operators adopt high-efficiency polymers to support drilling stability. Rising interest in digital drilling tools lifts demand for predictable additive performance. The region strengthens its position through constant field upgrades and strong service infrastructure.
Europe
The Europe Global Fluid Loss Control Additives Market size was valued at USD 61.54 million in 2018 to USD 79.12 million in 2024 and is anticipated to reach USD 98.69 million by 2032, at a CAGR of 2.5% during the forecast period. Europe holds a regional market share of 17.5%. The Global Fluid Loss Control Additives Market advances here due to steady North Sea activity and ongoing redevelopment projects. The UK and Norway drive adoption through mature basin operations needing efficient fluid systems. Many operators rely on specialty additives for harsh offshore conditions. Growing interest in geothermal wells also supports new product use. Chemical suppliers provide tailored solutions for narrow drilling windows. Europe’s strict environmental rules influence the shift toward cleaner additive systems. The region maintains stable demand supported by continued investment in offshore assets.
Asia Pacific
The Asia Pacific Global Fluid Loss Control Additives Market size was valued at USD 95.44 million in 2018 to USD 137.16 million in 2024 and is anticipated to reach USD 205.42 million by 2032, at a CAGR of 4.9% during the forecast period. Asia Pacific holds a strong market share of 30.4%. The Global Fluid Loss Control Additives Market benefits from extensive drilling programs in China, India, and Southeast Asia. Offshore exploration boosts interest in advanced filtration additives. National oil companies expand drilling to support energy security goals. Many wells require thermal-resistant additives due to varied geological conditions. Service groups grow regional capacity to support rising deep-water activity. Local chemical manufacturers introduce cost-effective formulations to meet field needs. Asia Pacific continues to build momentum through diverse upstream projects and expanding offshore licensing.
Latin America
The Latin America Global Fluid Loss Control Additives Market size was valued at USD 15.78 million in 2018 to USD 21.20 million in 2024 and is anticipated to reach USD 25.78 million by 2032, at a CAGR of 2.2% during the forecast period. Latin America accounts for 4.7% of the global market. The Global Fluid Loss Control Additives Market gains support from deep-water projects in Brazil and emerging developments in Argentina. Pre-salt fields encourage the use of advanced additives with stable high-pressure performance. Mexico’s offshore sector contributes steady activity. Many operators focus on improving drilling efficiency to reduce operational delays. Service companies strengthen supply chains to support remote field locations. National firms invest in technology upgrades to match complex reservoir demands. The region shows steady growth across offshore and unconventional targets.
Middle East
The Middle East Global Fluid Loss Control Additives Market size was valued at USD 9.04 million in 2018 to USD 11.21 million in 2024 and is anticipated to reach USD 12.91 million by 2032, at a CAGR of 1.5% during the forecast period. The Middle East holds 2.5% of the global share. The Global Fluid Loss Control Additives Market expands slowly here due to stable yet mature drilling activity. Large national oil companies maintain steady consumption tied to long-term production plans. Many wells require high-performing additives for carbonate formations. Service providers supply blends that sustain consistency in high-temperature zones. Operators focus on cost control while securing reliable mud additives. Regional drilling programs emphasize quality and field reliability. Growth remains gradual but supported by continuous upstream investment.
Africa
The Africa Global Fluid Loss Control Additives Market size was valued at USD 4.88 million in 2018 to USD 7.37 million in 2024 and is anticipated to reach USD 7.96 million by 2032, at a CAGR of 0.7% during the forecast period. Africa holds a regional share of 1.6%. The Global Fluid Loss Control Additives Market grows here through offshore developments in West Africa and emerging exploration in East Africa. Many basins require additive systems that improve drilling fluid resilience. Operators use these additives to protect wellbore integrity in complex geologies. Local supply constraints push companies to improve sourcing networks. Several national oil firms invest in enhanced drilling technologies. Environmental rules increase interest in safer additive formulations. The region experiences slow but stable growth supported by selective offshore investments.
Key Player Analysis:
- Halliburton
- Newpark Resources Inc.
- Schlumberger Limited
- Solvay
- Clariant
- BASF SE
- Global Drilling Fluids and Chemicals Limited
Competitive Analysis:
The Global Fluid Loss Control Additives Market reflects strong competition driven by chemical innovators, oilfield service leaders, and regional additive suppliers. Major firms strengthen their positions through advanced polymer technologies and customized drilling fluid solutions. Companies invest in high-temperature and high-pressure additive systems to support more complex wells. It demands consistent product quality, strong field support, and broad compatibility with drilling fluids. Global players focus on R&D to deliver blends that meet environmental and operational rules. Regional firms compete through pricing strategies and localized supply chains. Service providers integrate additives into complete mud systems to support field performance. The competitive landscape evolves through technology upgrades, targeted partnerships, and stronger global sourcing.
Recent Developments:
- In January 2025, Halliburton and Coterra Energy Inc. launched the Octiv Auto Frac service, a fully automated hydraulic fracturing technology that is part of the ZEUS platform and automates stage delivery execution with the push of a button, achieving a 17 percent boost in stage efficiency during initial rollout in the Permian Basin.
- In May 2024, Halliburton secured a major contract from Petrobras to deliver integrated drilling services for deep-water wells, utilizing advanced fluid-loss control additives and innovative cementing technologies to enhance well integrity. This contract, announced in January 2025 and expected to commence in 2025, represents Halliburton's largest service contract with Petrobras and significantly expands the company's drilling services footprint in the pre-salt and post-salt areas across Brazil's offshore fields for both development and exploration wells. The company deployed its BaraLogix real-time service, which addresses the technical limits of drilling fluids in offshore areas through advanced hydraulic software, surface measurement automation, and predictive analytics to reduce lost time.
- In September 2024, SCF Partners, Inc. announced its acquisition of the Newpark Fluids Systems business from Newpark Resources Inc. . The transaction, completed on September 13, 2024, involved the acquisition of Newpark Fluids Systems, a leading global pure-play oil and gas and geothermal fluids solution provider. Newpark Fluids Systems provides a full range of drilling and completion products and related technical services supported by an innovative digital modeling software suite, global supply chain, and infrastructure to enhance the efficiency and productivity of customer performance over its 25-year operational history maintaining a leading position in the drilling and completions fluids space worldwide.
- In April 2024, Schlumberger Limited (SLB) announced a definitive agreement to acquire ChampionX Corporation in an all-stock transaction for $40.59 per share. This strategic acquisition strengthens Schlumberger as a leader in the production space with world-class production chemicals and artificial lift technologies. The combined portfolios are expected to drive customer value through deep industry expertise and digital integration, as well as enhanced equipment life and production optimization. The acquisition is anticipated to generate annual pre-tax synergies of approximately $400 million within the first three years post-closing through revenue growth and cost savings. ChampionX's production chemicals division provides oil and natural gas production and midstream markets with solutions to manage and control corrosion, oil and water separation, flow assurance, sour gas treatment, and various water-related issues, including fluid loss control additives.
Report Coverage:
The research report offers an in-depth analysis based on Type and Technology segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise for advanced additives suited for deeper and hotter drilling zones.
- Eco-friendly additive formulations will gain wider acceptance in regulated regions.
- Smart and nano-enabled additives will expand through improved performance benefits.
- Service companies will integrate more digital tools to assess additive behavior.
- High-pressure offshore wells will push suppliers to develop stronger blends.
- Regional manufacturers will grow through cost-effective and localized production.
- Investment in R&D will increase to address new reservoir challenges.
- Additive portfolios will diversify to support automated drilling systems.
- Partnerships between operators and chemical firms will shape new solutions.
- Long-term demand will remain linked to global drilling activity and energy security plans.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Fluid Loss Control Additives Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Fluid Loss Control Additives Market projected to grow between 2025 and 2032?
Which Global Fluid Loss Control Additives Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Fluid Loss Control Additives Market?
Who are the leading companies in the Global Fluid Loss Control Additives Market?
Which region commanded the largest share of the Global Fluid Loss Control Additives Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fluid Loss Control Additives Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fluid Loss Control Additives Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 451.58 million → 2032: USD 619.91 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fluid Loss Control Additives Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fluid Loss Control Additives Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fluid Loss Control Additives Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fluid Loss Control Additives Market Drivers
- 3.3 Fluid Loss Control Additives Market Restraints & Challenges
- 3.4 Fluid Loss Control Additives Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fluid Loss Control Additives Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fluid Loss Control Additives Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fluid Loss Control Additives category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fluid Loss Control Additives Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fluid Loss Control Additives Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fluid Loss Control Additives market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fluid Loss Control Additives Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fluid Loss Control Additives Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fluid Loss Control Additives Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fluid Loss Control Additives (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fluid Loss Control Additives Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fluid Loss Control Additives Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fluid Loss Control Additives Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fluid Loss Control Additives Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fluid Loss Control Additives Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fluid Loss Control Additives Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fluid Loss Control Additives Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fluid Loss Control Additives Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fluid Loss Control Additives Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
