
Market Overview
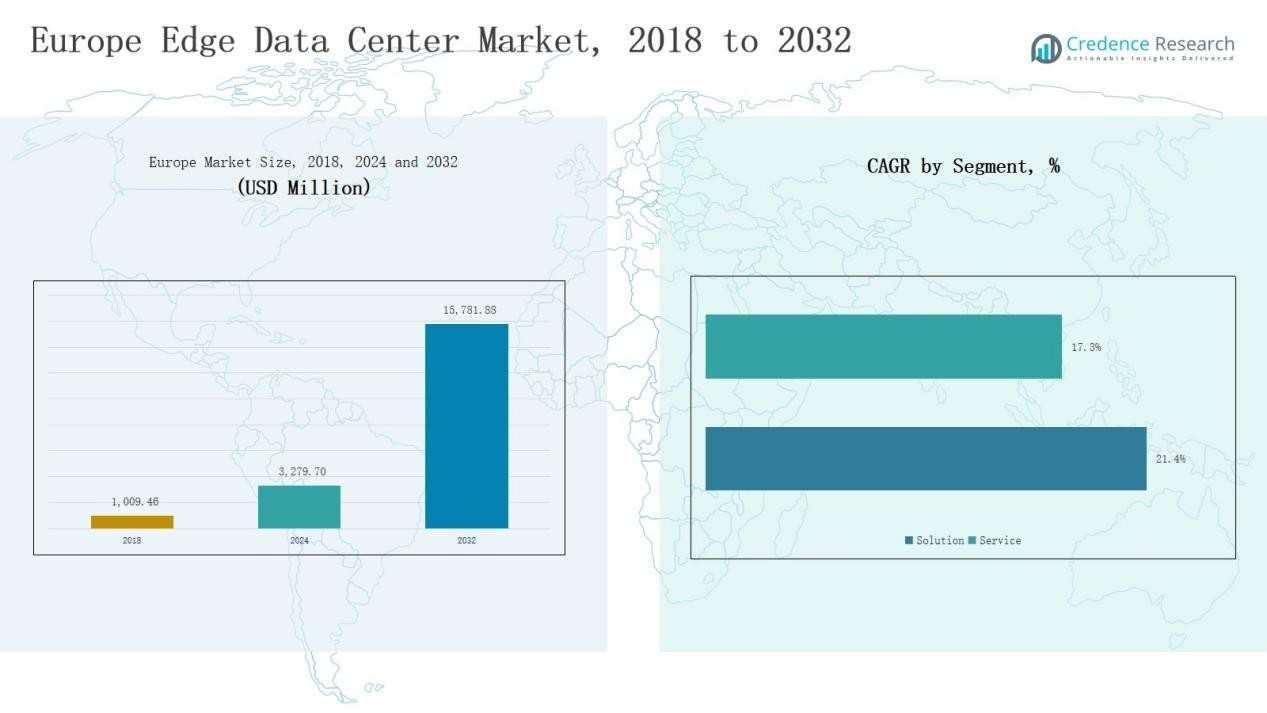
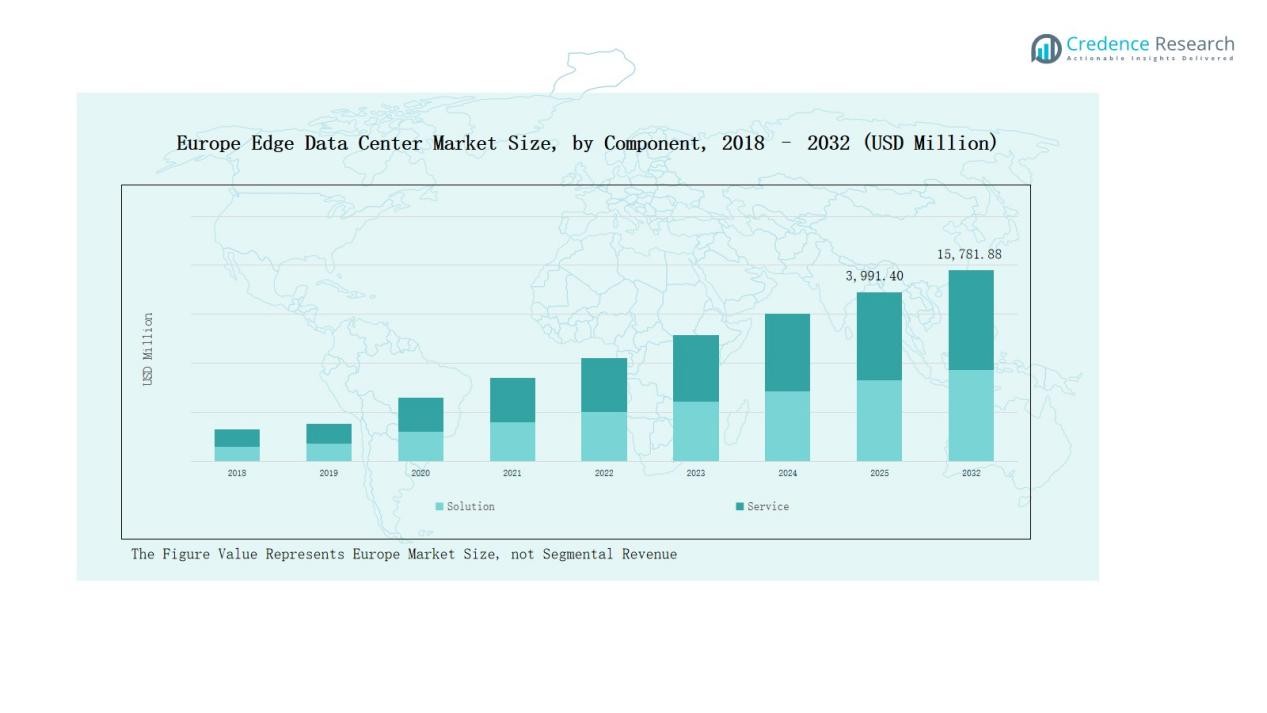
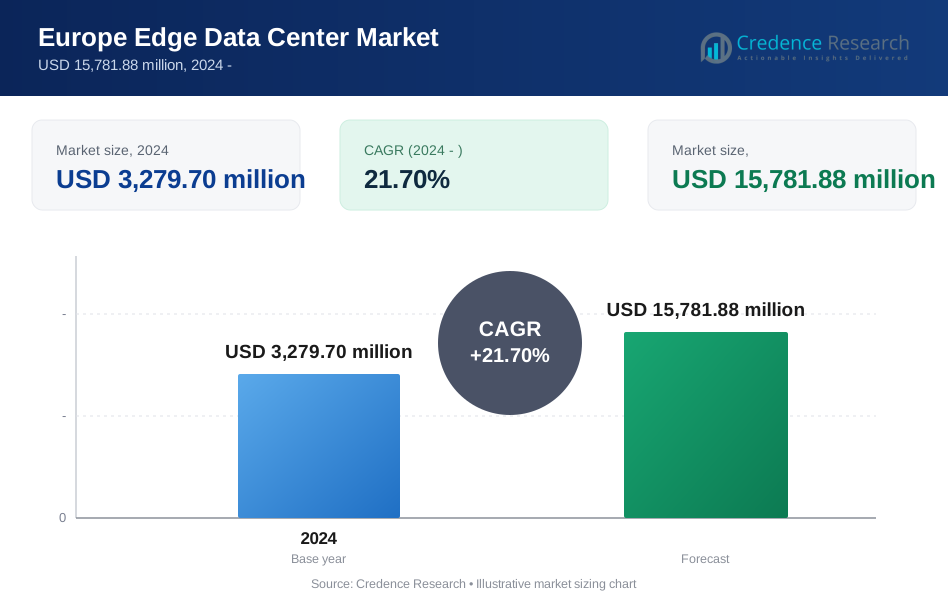
Europe Edge Data Center Market size was valued at USD 1,009.46 million in 2018, reached USD 3,279.70 million in 2024, and is anticipated to reach USD 15,781.88 million by 2032, growing at a CAGR of 21.70% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Edge Data Center Market Size 2024 | USD 3,279.70 Million |
| Europe Edge Data Center Market, CAGR | 21.70% |
| Europe Edge Data Center Market Size 2032 | USD 15,781.88 Million |
The Europe Edge Data Center Market is shaped by prominent players including Cisco Systems Inc., Dell Inc., IBM, Fujitsu, Eaton, EdgeConneX Inc., and ATC IP LLC, each strengthening their presence with advanced hardware, software, and service offerings tailored to European compliance and data sovereignty requirements. These companies focus on expanding localized infrastructure, partnering with telecom providers, and integrating AI-driven and energy-efficient solutions to support 5G, IoT, and cloud workloads. Regionally, the UK led the market in 2024 with a 22% share, supported by strong 5G rollout, robust cloud adoption, and favorable regulatory and investment conditions.
Market Insights
- The Europe Edge Data Center Market grew from USD 1,009.46 million in 2018 to USD 3,279.70 million in 2024 and will reach USD 15,781.88 million by 2032.
- Solutions led the component segment with 62% share in 2024, with hardware accounting for 41% and software 21%, driven by 5G, IoT, and GDPR compliance.
- Large facilities dominated with 68% share in 2024, favored by hyperscalers and telecom providers, while small and medium facilities held 32% supporting localized Industry 4.0 and smart city applications.
- IT and telecom was the largest end-use industry with 39% share in 2024, followed by BFSI at 18%, healthcare at 15%, and gaming and entertainment at 14%.
- The UK led the regional market with 22% share in 2024, followed by Germany at 20% and France at 15%, reflecting strong 5G rollout, industrial digitization, and AI adoption.
Market Segment Insights
By Component
Solutions dominated the Europe edge data center market in 2024, holding nearly 62% share. Hardware led this segment with around 41%, driven by demand for high-performance servers, storage, and power systems to support 5G and IoT workloads. Software followed with 21%, supported by virtualization, orchestration, and compliance with GDPR. Services remained smaller, with professional services at 10% and managed services at 7%, but both segments are expanding as enterprises seek expert deployment and outsourced operations.
- For instance, in the software segment, VMware enhanced its edge virtualization suite to help European operators achieve GDPR compliance and streamline orchestration across distributed data centers.
By Facility Size
Large facilities accounted for about 68% share in 2024, reflecting their scalability and ability to host AI, IoT, and telecom workloads. Hyperscalers and telecom providers favor these hubs for regional aggregation, redundancy, and advanced cooling systems. Small and medium facilities held 32%, serving localized needs such as smart factories, retail outlets, and municipal projects. Their agility, cost efficiency, and role in complementing larger hubs ensure steady adoption, particularly across Industry 4.0 and smart city initiatives.
- For instance, Microsoft launched a new data center region in Poland to support cloud workloads for businesses across Central Europe with enhanced energy-efficient cooling.
By End Use Industry
The IT and telecom sector led with 39% share in 2024, driven by 5G rollouts, cloud-edge integration, and broadband expansion. BFSI followed with 18%, supported by low-latency payment systems and regulatory compliance. Healthcare and lifesciences captured 15%, with edge facilities enabling telemedicine, genomic research, and secure health data management. Gaming and entertainment accounted for 14%, fueled by cloud gaming and streaming demand. Other industries, including retail, manufacturing, and energy, collectively contributed 14%, leveraging edge nodes for digital transformation.
Key Growth Drivers
Rising Adoption of 5G and IoT
The rollout of 5G networks and rapid IoT adoption are fueling demand for edge data centers in Europe. Telecom operators and enterprises require localized infrastructure to deliver low-latency services for connected devices, autonomous systems, and real-time analytics. Edge facilities enhance user experience by processing data closer to the source, reducing reliance on distant cloud servers. Governments and telecom providers across the UK, Germany, and France are heavily investing in 5G infrastructure, directly supporting strong deployment of edge data centers.
- For instance, in 2024, Vodafone Germany partnered with AWS Wavelength to expand edge computing services for industries such as automotive and manufacturing, enabling faster data processing at 5G network edges.
Increasing Demand for Data Sovereignty and Compliance
Strict regulations such as GDPR make data sovereignty a critical driver in Europe’s edge data center market. Enterprises must process and store sensitive data within national or regional boundaries, fueling adoption of localized infrastructure. BFSI, healthcare, and public sector organizations prioritize compliant edge deployments to manage customer information securely. Rising cybersecurity concerns further strengthen this shift, as edge facilities enable controlled environments with greater compliance oversight. The regulatory framework ensures sustainable growth, particularly in industries handling confidential and personal data.
- For instance, Equinix expanded its edge data center footprint in Frankfurt to provide localized infrastructure services aligned with GDPR compliance for financial institutions.
Expansion of Cloud and Digital Services
The surge in cloud computing, streaming services, and digital platforms drives investment in edge data centers across Europe. Hyperscalers and cloud providers deploy localized infrastructure to meet rising demand for low-latency digital experiences. Gaming, entertainment, and e-commerce platforms increasingly rely on edge capacity to support high traffic and seamless performance. Hybrid and multi-cloud adoption also creates opportunities, as enterprises need distributed architectures integrating edge with central cloud hubs. This expansion continues to strengthen demand for scalable, regionally distributed facilities.
Key Trends & Opportunities
Growth of Smart Cities and Industry 4.0
The development of smart cities and Industry 4.0 projects presents significant opportunities for edge data centers. Manufacturing firms adopt localized infrastructure to enable predictive maintenance, robotics, and real-time monitoring, while urban projects leverage edge for traffic control, energy management, and surveillance. European governments fund digital transformation initiatives, boosting adoption across industrial and public sectors. As cities integrate connected solutions and industries digitize operations, demand for edge infrastructure is expected to grow, making it central to Europe’s future economic landscape.
- For instance, Schneider Electric launched its EcoStruxure Micro Data Center solutions in Europe, designed to support smart city and industrial applications requiring low-latency processing at the edge.
Rising Role of AI and Automation
Artificial intelligence and automation are transforming the demand profile for edge data centers in Europe. AI-driven applications such as predictive analytics, healthcare diagnostics, and autonomous vehicles require high-speed data processing close to the user. Edge infrastructure supports these workloads by reducing latency and enabling real-time decision-making. Automated orchestration and workload management platforms further optimize edge deployment. Enterprises across Europe increasingly integrate AI tools with edge infrastructure, positioning AI as both a key trend and a growth opportunity for the market.
- For instance, Siemens partnered with NVIDIA to integrate AI-enabled industrial edge solutions, allowing manufacturers in Europe to process sensor data locally for faster operational insights.
Key Challenges
High Initial Capital Expenditure
Building and deploying edge data centers require significant capital investment, making it a key challenge in Europe. The need for advanced servers, cooling systems, and secure facilities increases upfront costs. Smaller enterprises and regional operators often struggle to finance deployments, slowing adoption. While large hyperscalers and telecom providers can manage these expenses, the high entry barrier limits wider penetration. This challenge highlights the importance of innovative financing models, partnerships, and modular deployments to reduce cost burdens and accelerate growth.
Fragmented Infrastructure and Scalability Issues
Europe’s diverse regulatory and infrastructure environment poses challenges for scaling edge data centers uniformly. Fragmented energy grids, varying regional compliance requirements, and inconsistent connectivity create deployment barriers. Scaling distributed facilities across multiple countries often requires significant customization, delaying expansion. Integration with existing cloud and IT infrastructure further complicates growth. These fragmentation issues can slow the pace of large-scale adoption and increase operational complexity, pushing providers to adapt strategies for local conditions while ensuring consistent service delivery across regions.
Rising Cybersecurity and Data Privacy Concerns
Cybersecurity and privacy risks remain critical challenges for Europe’s edge data center market. Processing data across multiple distributed facilities increases vulnerabilities, making them attractive targets for cyberattacks. Ensuring compliance with GDPR and other national data protection laws adds complexity for operators. Industries such as BFSI and healthcare, handling sensitive information, face heightened risks if infrastructure is not fully secured. Providers must invest in advanced encryption, monitoring, and threat detection systems to safeguard data, but these measures add cost and complexity.
Regional Analysis
UK
The UK held 22% share in 2024, driven by rapid 5G rollout and strong cloud adoption. London remains the central hub, supported by high-density urban infrastructure and demand for low-latency services. Enterprises across BFSI and healthcare sectors prioritize edge deployments to comply with GDPR and improve customer experience. The gaming and streaming industries also fuel demand for localized infrastructure. Government-backed smart city initiatives enhance growth prospects. The Europe Edge Data Center Market in the UK benefits from its advanced digital ecosystem and investment-friendly environment.
Germany
Germany accounted for 20% share in 2024, led by strong industrial digitization and Industry 4.0 adoption. Its manufacturing sector relies on edge data centers to enable predictive maintenance, robotics, and real-time monitoring. Telecom providers continue expanding 5G coverage, supporting broader adoption. Frankfurt acts as a major data hub due to its financial sector and strategic location. Compliance-driven sectors such as healthcare and automotive are accelerating deployments. It remains a critical market for both hyperscalers and domestic service providers.
France
France captured 15% share in 2024, supported by rising investments in smart city infrastructure and public sector digitalization. Paris dominates due to its role as a commercial and cultural hub. Telecom operators and entertainment platforms drive localized edge facilities to improve connectivity and streaming performance. Healthcare providers adopt edge infrastructure to manage sensitive patient data within national boundaries. Strong government support for AI initiatives further accelerates adoption. It continues to attract global providers expanding their European presence.
Italy
Italy held 10% share in 2024, with growth centered on telecom expansion and increasing digital service consumption. Milan leads as the main data hub, supported by banking, fashion, and retail industries. Gaming and entertainment platforms are driving new deployments, alongside growing adoption in healthcare. Edge facilities also support emerging smart city projects across northern regions. Enterprises seek localized infrastructure to enhance compliance with European regulations. It represents a steadily growing market segment within the region.
Spain
Spain represented 9% share in 2024, driven by expanding telecom services and growing consumer demand for digital platforms. Madrid and Barcelona serve as key hubs, supporting adoption in BFSI, gaming, and retail. The country’s strong tourism sector increases reliance on real-time connectivity solutions. Edge infrastructure supports government efforts in smart city projects, particularly in urban transportation and energy management. Healthcare facilities adopt edge solutions for digital health records and telemedicine. It shows consistent growth momentum in Southern Europe.
Russia
Russia accounted for 12% share in 2024, supported by large-scale telecom projects and state-led digital infrastructure investments. Moscow and St. Petersburg dominate, serving as major technology and commercial hubs. Growing adoption in manufacturing and energy sectors further strengthens demand. The regulatory focus on data sovereignty drives localized deployments. Gaming and streaming platforms expand edge presence to cater to a large digital consumer base. It is emerging as a strategic market with strong growth potential despite geopolitical complexities.
Rest of Europe
The Rest of Europe contributed 12% share in 2024, including countries such as the Netherlands, Belgium, and Nordic nations. The Netherlands serves as a connectivity hub due to its strategic port and strong IT ecosystem. Nordic countries focus on sustainable data centers powered by renewable energy, aligning with regional climate goals. Edge adoption is supported by retail and logistics sectors. Smaller Eastern European economies are adopting edge gradually, driven by telecom expansion. It provides balanced growth opportunities across diverse markets.
Market Segmentations:
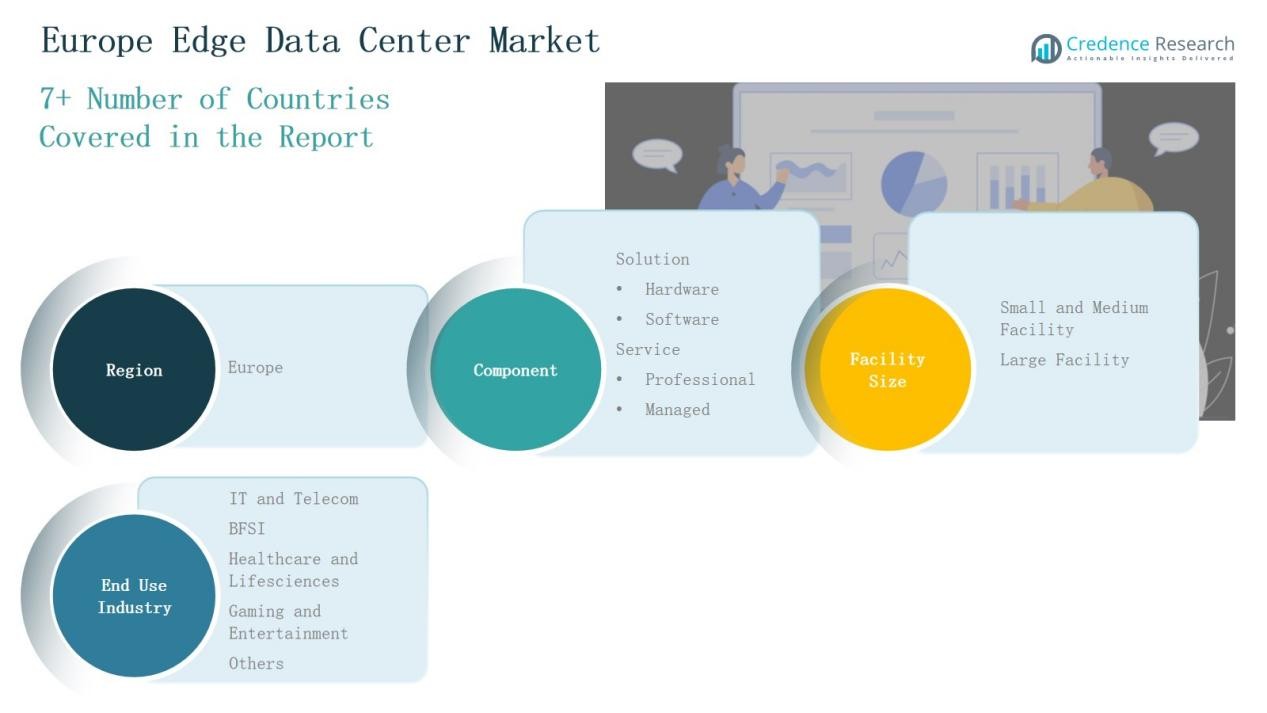
By Component
Solution
- Hardware
- Software
Service
- Professional
- Managed
By Facility Size
- Small and Medium Facility
- Large Facility
By End Use Industry
- IT and Telecom
- BFSI
- Healthcare and Lifesciences
- Gaming and Entertainment
- Others
By Region
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The Europe Edge Data Center Market is characterized by intense competition among global technology leaders, telecom operators, and regional service providers. Key players such as Cisco Systems Inc., Dell Inc., IBM, Fujitsu, Eaton, EdgeConneX Inc., and ATC IP LLC strengthen their presence through advanced hardware, software, and service portfolios tailored to European regulations. They emphasize localized infrastructure to address GDPR compliance, data sovereignty, and rising demand for low-latency solutions. Partnerships with telecom operators and cloud providers play a central role, supporting large-scale 5G rollouts and digital service expansion. Companies also invest in AI-driven automation, energy-efficient infrastructure, and modular deployments to enhance scalability and reduce operational costs. Regional players, particularly in the UK, Germany, and France, complement global firms by offering tailored solutions to SMEs and niche sectors. Competition continues to intensify as new entrants leverage innovative models, while established firms expand footprints through mergers, acquisitions, and strategic alliances.
Key Players
- ATC IP LLC
- Cisco Systems Inc.
- Dell Inc.
- Eaton
- EdgeConneX Inc.
- IBM
- Fujitsu
Recent Developments
- In June 2025, Smart Campus and Schneider Electric partnered to develop a 26 MW data center in Sines, Portugal.
- In September 2025, Digital Gravity Partners (via JV with BlackRock, “Gravity Edge”) acquired a data centre in Camberley, UK.
- In September 2025, Hochtief announced plans for a 2 MW timber-frame edge data center in Herne, Germany.
- In 2025, Edgnex acquired Finnish data center developer Hyperco and formed a strategic partnership.
Report Coverage
The research report offers an in-depth analysis based on Component, Facility Type, End Use Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Edge facilities will expand further to support 5G networks and low-latency applications.
- Hardware demand will remain strong as enterprises invest in scalable infrastructure.
- Software adoption will increase with growth in AI-enabled orchestration and automation tools.
- Managed services will gain traction as firms outsource monitoring and maintenance.
- Large facilities will dominate deployments, while smaller sites will grow for localized needs.
- IT and telecom will continue to lead adoption across major European markets.
- BFSI and healthcare sectors will strengthen usage due to regulatory and security needs.
- Gaming and entertainment will accelerate growth with rising cloud gaming and streaming services.
- Investments will rise in sustainable and energy-efficient infrastructure to meet climate goals.
- Strategic partnerships among cloud providers, telecom operators, and technology vendors will intensify.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of 5G and IoT
The rollout of 5G networks and rapid IoT adoption in Europe are driving demand for edge data centers, as telecom operators and enterprises require localized infrastructure to deliver low-latency services for connected devices and real-time analytics.
Increasing Demand for Data Sovereignty and Compliance
Strict regulations such as GDPR make data sovereignty a critical driver, pushing enterprises to process and store sensitive data within national or regional boundaries, thus fueling adoption of localized edge data centers.
Expansion of Cloud and Digital Services
The surge in cloud computing, streaming, and digital platforms is prompting hyperscalers and cloud providers to invest in edge data centers to meet the need for low-latency digital experiences and support hybrid and multi-cloud architectures.
Growth of Smart Cities and Industry 4.0
Smart city initiatives and Industry 4.0 projects across Europe are increasing the need for edge data centers to enable real-time monitoring, predictive maintenance, and connected urban infrastructure, supported by government funding and industrial digitization.
Rising Role of AI and Automation
The proliferation of AI-driven applications and automation in sectors like manufacturing and healthcare is boosting demand for edge data centers, as these workloads require high-speed, local data processing and real-time decision-making capabilities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Edge Data Center Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Edge Data Center Market projected to grow between 2025 and 2032?
Which Europe Edge Data Center Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Edge Data Center Market?
Who are the leading companies in the Europe Edge Data Center Market?
Which region commanded the largest share of the Europe Edge Data Center Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Professional Services
- 1.2.4 Managed Services
- 1.3 By Facility Size
- 1.3.1 Small and Medium Facility
- 1.3.2 Large Facility
- 1.4 By End Use Industry
- 1.4.1 IT and Telecom
- 1.4.2 BFSI
- 1.4.3 Healthcare and Lifesciences
- 1.4.4 Gaming and Entertainment
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,279.70 million → 2032: USD 15,781.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Edge Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Edge Data Center Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Edge Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Edge Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Edge Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Edge Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Edge Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Edge Data Center Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,279.70 million → 2032: USD 15,781.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Edge Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Professional Services
- 12.3.7.4 Managed Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Facility Size - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small and Medium Facility
- 12.4.7.2 Large Facility
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 IT and Telecom
- 12.5.7.2 BFSI
- 12.5.7.3 Healthcare and Lifesciences
- 12.5.7.4 Gaming and Entertainment
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Edge Data Center End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Edge Data Center Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Edge Data Center Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Edge Data Center Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cisco Systems Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dell Inc.
- 18.4 IBM
- 18.5 Fujitsu
- 18.6 Eaton
- 18.7 EdgeConneX Inc.
- 18.8 ATC IP LLC
- 18.9 Schneider Electric
- 18.10 Equinix
- 18.11 Microsoft
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

