
Market Overview:
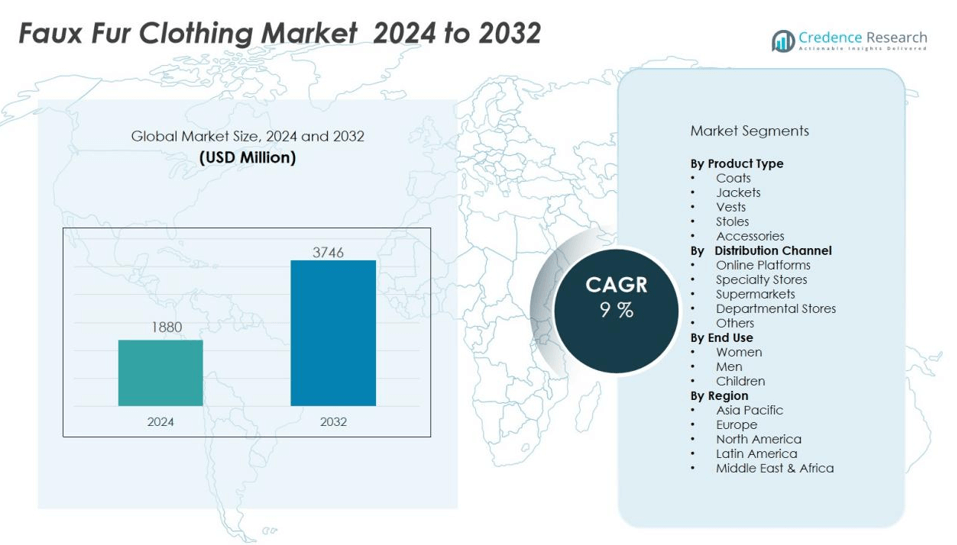
The Faux fur clothing market size was valued at USD 1880 million in 2024 and is anticipated to reach USD 3746 million by 2032, at a CAGR of 9 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Faux Fur Clothing Market Size 2024 | USD 1880 million |
| Faux Fur Clothing Market, CAGR | 9% |
| Faux Fur Clothing Market Size 2032 | USD 3746 million |
Market growth is strongly driven by shifting consumer preferences toward sustainable and animal-friendly fashion, supported by regulatory restrictions on animal fur in key regions such as Europe and North America. Increasing innovation in fabric technology, which enhances the look, feel, and durability of faux fur, is improving consumer acceptance. In addition, rising disposable incomes and demand for fashionable outerwear, coupled with the influence of celebrity endorsements and fashion influencers, are accelerating the adoption of faux fur clothing across both premium and affordable categories.
Regionally, Europe dominates the faux fur clothing market, backed by strict bans on animal fur products and high penetration of luxury brands. North America follows closely, driven by growing consumer awareness and fashion-forward demand in the U.S. and Canada. Asia-Pacific represents the fastest-growing region, supported by expanding middle-class populations in China, Japan, and South Korea, where rising disposable incomes and adoption of global fashion trends are propelling significant growth opportunities.
Market Insights:
- The faux fur clothing market was valued at USD 1880 million in 2024 and is expected to reach USD 3746 million by 2032, growing at a CAGR of 9 percent during the forecast period.
- Rising ethical consumerism and regulatory bans on animal fur in Europe and North America are accelerating demand for cruelty-free alternatives.
- Advancements in textile innovation are improving the softness, durability, and appeal of faux fur, increasing acceptance across premium and affordable fashion.
- Environmental concerns tied to synthetic fibers remain a challenge, prompting brands to explore recycled and bio-based materials to address sustainability gaps.
- Europe holds 40 percent share, North America 30 percent, and Asia-Pacific 20 percent, with Asia-Pacific projected as the fastest-growing region due to rising disposable incomes and fashion adoption.
Market Drivers:
Rising Ethical Consumerism and Animal Welfare Concerns:
The faux fur clothing market is expanding as consumers increasingly adopt cruelty-free fashion alternatives. Heightened awareness of animal welfare and global campaigns against the use of real fur have reshaped consumer preferences. It reflects a strong shift toward products that align with ethical values while still meeting style expectations. Luxury and mainstream brands are responding by replacing real fur with sustainable faux options to retain consumer loyalty.
- For instance, LVMH achieved €84.7 billion in revenue for 2024, with their Fashion & Leather Goods division generating €41 billion, demonstrating strong consumer demand for luxury alternatives including faux fur products.
Advancements in Fabric Innovation and Product Quality:
Technological progress in textiles is a key driver for the faux fur clothing market. Manufacturers are introducing high-quality synthetic fibers that replicate the softness, warmth, and texture of real fur. It enhances consumer perception by offering products that are both durable and fashionable. These innovations are improving product acceptance across diverse price ranges, widening the consumer base.
Regulatory Support and Industry Commitments to Sustainability
Strict regulations and bans on animal fur in Europe and other regions are accelerating the adoption of faux alternatives. The faux fur clothing market benefits from government support for sustainable fashion practices and industry pledges to phase out animal-derived materials. It creates a favorable environment where retailers and designers are compelled to expand faux fur collections. The movement positions faux fur as a mainstream and responsible choice across global fashion hubs.
- For instance, Kering confirmed that by December 2022, all 12 of its luxury houses-such as Gucci and Saint Laurent-had fully replaced animal fur with high-grade recycled faux fur in their collections, marking a complete fur-free transition across its portfolio 12.
Growing Influence of Fashion Trends and Celebrity Endorsements:
Fashion trends driven by celebrities, influencers, and social media platforms are strongly shaping consumer demand. The faux fur clothing market is gaining momentum as stylish, versatile outerwear and accessories become popular across demographics. It benefits from visibility in global fashion weeks and seasonal collections from leading designers. The association of faux fur with premium yet ethical fashion significantly amplifies its market growth.
Market Trends:
Integration of Sustainability and Circular Fashion Practices:
The faux fur clothing market is witnessing a strong trend toward sustainable production and circular fashion models. Brands are incorporating recycled polyester, bio-based fibers, and eco-friendly dyes to reduce the environmental footprint of faux fur garments. It supports the demand for fashion that aligns with both ethical and environmental values. Leading fashion houses are highlighting transparency in sourcing and manufacturing to attract conscious consumers. Rental platforms and resale channels are also extending the life cycle of faux fur products. The adoption of such practices positions faux fur as a long-term sustainable alternative within global fashion markets.
- For instance, Stella McCartney’s KOBA® faux fur integrates 37 percent plant-based DuPont™ Sorona® fibers, enabling full recyclability at the end of its life cycle.
Mainstream Acceptance Through Luxury and Fast-Fashion Adoption:
The faux fur clothing market is experiencing growing acceptance across both luxury and mass-market segments. High-end fashion houses are showcasing faux fur on global runways, enhancing its status as a premium material. At the same time, fast-fashion retailers are expanding affordable collections to cater to middle-income consumers. It reflects the versatility of faux fur in meeting diverse fashion needs across price points. Social media platforms amplify these trends by showcasing new styles and influencing rapid adoption. This widespread acceptance is redefining consumer perception of faux fur, moving it from a niche alternative to a mainstream fashion essential.
- For instance, Gucci’s Off The Grid collection introduced faux fur jackets made with 90% recycled polyester-equivalent to repurposing 14 plastic bottles per coat in 2024.
Market Challenges Analysis:
High Environmental Impact of Synthetic Materials:
The faux fur clothing market faces a challenge due to the environmental concerns associated with synthetic fibers. Most faux fur garments rely on petroleum-based materials such as acrylic and polyester, which contribute to plastic pollution and slow biodegradation. It creates a conflict for consumers seeking both cruelty-free and eco-friendly fashion. Growing criticism of microplastic shedding during washing further intensifies sustainability debates. Brands are under pressure to innovate with bio-based or recycled alternatives to address this gap. The inability to balance ethical sourcing with environmental impact slows wider acceptance among environmentally conscious buyers.
Perception Issues and Market Competition:
The faux fur clothing market also struggles with consumer perception and intense competition from other sustainable materials. Some buyers still view faux fur as less luxurious compared to natural fur, limiting its appeal in premium segments. It competes with alternative fabrics such as organic wool, hemp, and recycled textiles that promote both warmth and sustainability. Price sensitivity in emerging markets also restricts the adoption of high-quality faux fur products. Supply chain complexities and inconsistent quality standards across regions further weaken market confidence. Overcoming these barriers is essential for maintaining steady growth and reinforcing faux fur’s role in mainstream fashion.
Market Opportunities:
Rising Demand for Sustainable and Cruelty-Free Fashion:
The faux fur clothing market presents a major opportunity in catering to the rising global demand for sustainable and animal-friendly apparel. Consumers are increasingly rejecting animal-derived products, creating space for innovative faux fur alternatives. It enables brands to capture a wider audience by combining fashion appeal with ethical responsibility. Growing support from regulators and fashion councils further enhances the adoption of cruelty-free materials. Expanding eco-conscious consumer bases in both developed and emerging markets strengthen long-term growth potential. Companies that align their offerings with these values can build strong brand loyalty and competitive differentiation.
Expansion Across Emerging Markets and New Fashion Segments:
The faux fur clothing market has an opportunity to grow rapidly in Asia-Pacific, Latin America, and the Middle East, where rising disposable incomes and global fashion awareness are reshaping consumer choices. Demand for stylish outerwear and luxury-inspired designs is driving acceptance among younger demographics. It creates prospects for both affordable fast-fashion and premium luxury brands to establish stronger presence. Increasing adoption of e-commerce platforms accelerates market penetration in untapped regions. Collaboration with influencers and local fashion designers further amplifies product visibility and consumer interest. These factors create significant room for expansion beyond traditional Western markets.
Market Segmentation Analysis:
By Product Type:
The faux fur clothing market is segmented into coats, jackets, vests, stoles, and accessories. Coats and jackets dominate due to their versatility and high demand in colder regions. It gains traction from consumers who view outerwear as both a necessity and a fashion statement. Vests and stoles appeal to niche buyers seeking luxury-inspired styles, while accessories such as hats and trims add value to seasonal collections. Rising product variety strengthens brand portfolios and enhances consumer choice.
- For instance, Stella McCartney’s Spring 2020 collection included 1,500 KOBA® faux fur vests made with 37 percent bio-based DuPont™ Sorona® fibers, reducing greenhouse gas emissions by 63 percent.
By Distribution Channel:
The market is divided into online platforms, specialty stores, supermarkets, and others. Online platforms lead growth by offering wide product access, competitive pricing, and global reach. It benefits from fashion influencers and e-commerce campaigns that highlight cruelty-free trends. Specialty stores remain significant, especially for luxury brands that emphasize premium quality and exclusivity. Supermarkets and departmental outlets expand reach among middle-income buyers seeking affordable fashion. Retail diversity ensures balanced sales momentum across regions.
By End-user:
The market caters to women, men, and children, with women holding the largest share due to strong demand for stylish outerwear. It reflects high fashion adoption rates and the influence of social media on women’s apparel. Men’s segment is growing as brands expand designs in coats and jackets targeting premium buyers. Children’s wear offers new opportunities, supported by parental preference for ethical clothing. Expanding end-user categories drive overall market resilience.
- For instance, Patagonia’s 3-layer H₂No® alpine shell achieves a 20,000-mm waterproof rating under lab tests.
Segmentations:
By Product Type:
- Coats
- Jackets
- Vests
- Stoles
- Accessories
By Distribution Channel:
- Online Platforms
- Specialty Stores
- Supermarkets
- Departmental Stores
- Others
By End-user:
- Women
- Men
- Children
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe:
Europe holds 40 % share of the faux fur clothing market, making it the leading regional contributor. Strict bans on real fur and strong consumer awareness of sustainability drive the dominance of this region. It benefits from the presence of luxury fashion houses in Italy, France, and the United Kingdom that integrate faux fur into high-end collections. The European Union’s regulations on animal welfare reinforce market adoption and push retailers toward eco-conscious alternatives. Rising interest in circular fashion practices further accelerates growth. Retailers and designers continue to expand seasonal offerings, ensuring faux fur remains embedded in regional fashion trends.
North America:
North America accounts for 30 % share of the faux fur clothing market, supported by a strong base of fashion-conscious consumers. The U.S. and Canada are driving demand with rising bans on real fur at state and city levels. It is further strengthened by collaborations between luxury brands and fast-fashion retailers, which are popularizing faux fur across different price ranges. E-commerce platforms enhance accessibility, enabling diverse consumer groups to embrace cruelty-free fashion. The region’s cultural emphasis on individuality and style supports adoption across younger demographics. Seasonal demand for outerwear in colder climates continues to reinforce market expansion.
Asia-Pacific:
Asia-Pacific holds 20 % share of the faux fur clothing market, reflecting its rapid expansion across China, Japan, and South Korea. Rising disposable incomes and growing awareness of sustainable fashion are driving significant adoption. It benefits from strong influence of global fashion trends and increased exposure through digital platforms. Local fashion retailers are incorporating faux fur into collections to attract younger consumers seeking stylish yet ethical choices. E-commerce growth enhances distribution and provides access to international brands. The region’s large consumer base and fast-developing fashion industry position it as a critical growth driver for the coming years.
Key Player Analysis:
- FIM
- Peltex
- DEALTASK
- Texfactor Textiles
- Yorkshire Fur Fabrics
- Joel Son Fabrics
- Aono Pile
- EZ Fabric
- Throw
- Velu, JANWO
- Ningbo Berrex Textile
- Shanghai Haixin Plush
- Zhejiang Jiashan Yueda Artificial
Competitive Analysis:
The faux fur clothing market is competitive, with key players focusing on innovation, sustainability, and quality to strengthen their positions. Major companies include FIM, Peltex, DEALTASK, Texfactor Textiles, Yorkshire Fur Fabrics, Joel Son Fabrics, Aono Pile, EZ Fabric, and Throw. It is defined by continuous product development where brands invest in advanced synthetic fibers to replicate the softness and warmth of real fur while reducing environmental impact. Global leaders emphasize ethical fashion commitments, aligning strategies with consumer demand for cruelty-free alternatives. Regional manufacturers compete by offering cost-effective solutions and catering to niche fashion requirements. Strategic partnerships with designers and retailers are common, enabling faster adoption of seasonal collections and greater brand visibility. It reflects a market where differentiation is achieved through innovation in fabric technology, competitive pricing, and expanding distribution networks, creating a dynamic environment for established companies and emerging players alike.
Recent Developments:
- In December 2023, ABB launched ABB Ability™ Field Information Manager (FIM) 3.0, enhancing connectivity, system integration, and operational efficiency for field instrumentation systems with advanced communication protocols like OPC UA and PA-DIM.
- In January 2025, Fellfab announced and completed the acquisition of Miltex Solutions Canada Inc., further expanding its market reach in industrial and manufacturing solutions.
Market Concentration & Characteristics:
The faux fur clothing market is moderately concentrated, with competition shaped by both luxury fashion houses and fast-fashion retailers. It is characterized by continuous product innovation, as brands focus on developing high-quality synthetic fibers that replicate the look and feel of real fur. Global leaders emphasize sustainability, transparency, and ethical sourcing to strengthen consumer trust and brand positioning. Regional players compete by offering affordable alternatives and leveraging e-commerce platforms for wider reach. Fashion influencers and seasonal trends play a critical role in driving consumer adoption. The market maintains a balance between premium exclusivity and mass-market accessibility, ensuring steady growth across diverse consumer segments.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Distribution Channel, End-user and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The faux fur clothing market will expand as ethical and sustainable fashion becomes a global standard across luxury and mass-market segments.
- Brands will invest in advanced textile technologies to create eco-friendly alternatives using recycled and bio-based fibers.
- Demand will rise in colder regions where faux fur outerwear serves as both a fashion statement and a functional necessity.
- E-commerce platforms will enhance market penetration by offering broader accessibility and personalized shopping experiences.
- Luxury fashion houses will continue to set trends by replacing real fur with high-quality faux alternatives on global runways.
- Social media and influencer marketing will shape consumer preferences, especially among younger demographics seeking stylish yet ethical options.
- Regulatory support and fur bans in multiple countries will accelerate the transition toward cruelty-free fashion.
- Emerging markets in Asia-Pacific and Latin America will provide new growth avenues, driven by rising disposable incomes and global fashion influence.
- Collaboration between designers and sustainability-focused organizations will improve awareness and adoption of eco-conscious practices.
- Continuous innovation in product quality and variety will strengthen consumer confidence, positioning faux fur as a mainstream fashion essential.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Ethical Consumerism and Animal Welfare Concerns
Consumers are increasingly seeking cruelty-free and animal-friendly fashion, leading to a shift away from real fur and driving demand for faux fur clothing. Regulatory bans and global campaigns against animal fur further reinforce this trend, compelling brands to offer sustainable alternatives.
Advancements in Fabric Innovation and Product Quality
Technological improvements in synthetic fibers have enhanced the softness, warmth, and durability of faux fur, making it more appealing to consumers across both premium and affordable segments. These innovations are expanding the market by improving product acceptance and broadening the consumer base.
Regulatory Support and Industry Commitments to Sustainability
Strict regulations and bans on animal fur, especially in Europe and North America, are accelerating the adoption of faux fur. Industry commitments to phase out animal-derived materials and government support for sustainable fashion practices create a favorable environment for market growth.
Influence of Fashion Trends and Celebrity Endorsements
Celebrity endorsements, influencer marketing, and visibility in global fashion weeks are making faux fur clothing highly desirable. This trend-driven demand is boosting adoption across demographics and positioning faux fur as both a stylish and ethical choice.
Expansion in Emerging Markets and E-commerce Growth
Rising disposable incomes and growing fashion awareness in Asia-Pacific and Latin America, combined with the accessibility provided by e-commerce platforms, are opening new growth avenues for faux fur clothing. These factors are enabling brands to reach wider audiences and penetrate untapped markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the faux fur clothing market, and what is its projected size in 2032?
Which faux fur clothing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the faux fur clothing market?
Who are the leading companies in the faux fur clothing market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Women
- 1.2.2 Men
- 1.2.3 Children
- 1.3 By Product Type
- 1.3.1 Coats
- 1.3.2 Jackets
- 1.3.3 Vests
- 1.3.4 Stoles
- 1.3.5 Accessories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1880 million → 2032: USD 3746 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Faux Fur Clothing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Faux Fur Clothing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Faux Fur Clothing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Faux Fur Clothing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Faux Fur Clothing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Faux Fur Clothing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Faux Fur Clothing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Faux Fur Clothing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1880 million → 2032: USD 3746 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Faux Fur Clothing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Women
- 12.3.7.2 Men
- 12.3.7.3 Children
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coats
- 12.4.7.2 Jackets
- 12.4.7.3 Vests
- 12.4.7.4 Stoles
- 12.4.7.5 Accessories
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Faux Fur Clothing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Faux Fur Clothing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Faux Fur Clothing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Faux Fur Clothing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stella McCartney
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Gucci (Kering Group)
- 18.4 LVMH
- 18.5 FIM
- 18.6 Peltex
- 18.7 Yorkshire Fur Fabrics
- 18.8 Joel Son Fabrics
- 18.9 Aono Pile
- 18.10 EZ Fabric
- 18.11 Ningbo Berrex Textile
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

