
Fermented Foods Market Overview:
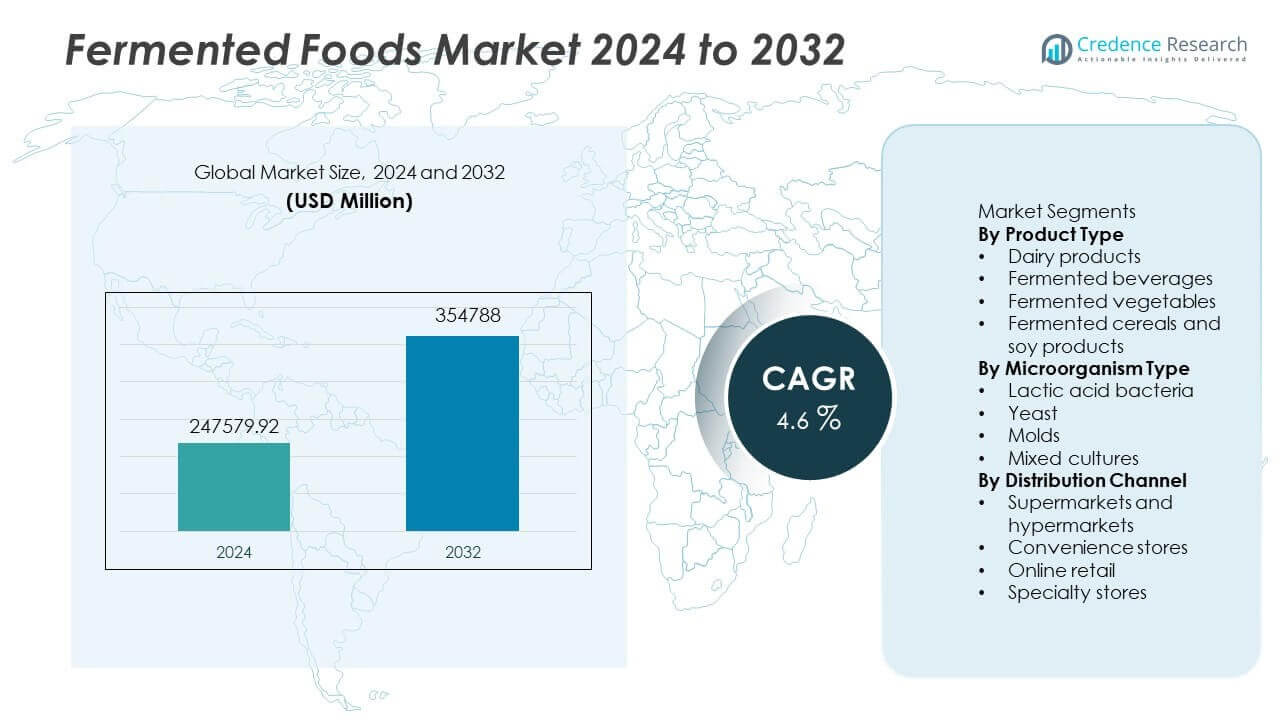
The fermented foods market reached USD 247579.92 million in 2024 and is projected to reach USD 354788 million by 2032, growing at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fermented Foods Market Size 2024 | USD 247579.92 million |
| Fermented Foods Market, CAGR | 4.6% |
| Fermented Foods Market Size 2032 | USD 354788 million |
Fermented Foods Market Insights
- Growing demand for gut health, immunity support, and natural preservation methods drives adoption, with dairy products leading the product type segment at a market share of 41.8% due to daily consumption and probiotic awareness.
- Product trends include expansion of non-dairy fermented foods and premium functional offerings, while lactic acid bacteria dominate the microorganism segment with a market share of 47.3% due to proven digestive benefits.
- Competitive intensity remains high as global brands focus on clean-label innovation, cold-chain efficiency, and portfolio diversification, while private labels increase pressure in mature retail markets.
- Asia Pacific leads regional performance with a market share of 38.4%, followed by Europe at 27.6% and North America at 22.1%, supported by cultural consumption patterns and strong retail penetration.
Fermented Foods Market Segmentation Analysis:
By Product Type
By product type, dairy products dominate the fermented foods market with a market share of 41.8%. Yogurt, kefir, and fermented milk drive this leadership due to daily consumption habits and strong probiotic awareness. Consumers associate dairy-based fermented foods with gut health, immunity support, and digestive balance. Long-established consumption patterns in Europe and Asia Pacific support steady demand. Product innovation in low-fat, lactose-free, and fortified dairy variants further strengthens adoption. Fermented beverages and vegetables follow, supported by clean-label trends, while cereals and soy products show rising acceptance among vegan consumers. Dairy maintains leadership due to trust, availability, and nutritional positioning.
- For instance, Danone expanded its yogurt R&D with over 1,700 active researchers and more than 55 global research centers, supporting rapid dairy formulation upgrades.
By Microorganism Type
By microorganism type, lactic acid bacteria hold a dominant market share of 47.3%. This dominance reflects wide usage in yogurt, cheese, fermented milk, and vegetable-based products. Lactic acid bacteria support digestion, improve gut microbiota, and enhance food preservation. Strong clinical backing and regulatory acceptance increase manufacturer confidence in these cultures. Food producers favor lactic strains for consistent fermentation performance and flavor stability. Yeast and mixed cultures serve niche beverage and specialty applications, while molds remain limited to specific products. The dominance of lactic acid bacteria continues due to proven health benefits, scalable production, and strong consumer recognition.
- For instance, Chr. Hansen Holding A/S maintains a microbial culture collection exceeding 40,000 strains, enabling precise lactic culture selection for yogurt and cheese.
By Distribution Channel
By distribution channel, supermarkets and hypermarkets lead the fermented foods market with a market share of 52.6%. These outlets offer wide product assortments, competitive pricing, and strong cold-chain infrastructure. High footfall supports impulse purchases and brand visibility. Consumers prefer physical retail for perishable fermented products due to freshness assurance. Promotional strategies and private-label offerings further strengthen channel dominance. Convenience stores support urban demand, while online retail gains traction for specialty products. Specialty stores cater to premium buyers but remain smaller in scale. Supermarkets retain leadership through accessibility, trust, and efficient distribution networks.
Key Growth Drivers
Rising Consumer Focus on Gut Health and Immunity
Consumers increasingly link fermented foods with digestive health and immune support. Products containing live cultures gain strong acceptance in daily diets. Medical guidance and nutrition awareness programs reinforce probiotic benefits. Urban consumers seek functional foods that support long-term wellness. Fermented dairy and beverages fit well into regular meals and snacks. This health-driven shift supports repeat consumption across age groups. Manufacturers highlight digestive benefits on packaging to influence buying behavior. Growing awareness of microbiome balance continues to drive demand across developed and emerging markets.
- For instance, Yakult Honsha Co., Ltd. uses a single Lactobacillus casei Shirota strain, supported by more than 200 human studies published globally.
Expansion of Clean-Label and Natural Food Preferences
Clean-label demand strongly supports fermented food consumption. Consumers prefer foods made through natural preservation methods. Fermentation aligns with minimal processing and ingredient transparency. Shoppers avoid artificial preservatives and additives. Traditional fermentation methods build trust and product authenticity. Brands promote short ingredient lists to attract health-focused buyers. Regulatory pressure on synthetic additives also supports this shift. Natural positioning helps fermented foods compete against processed alternatives. This driver supports strong adoption across retail and foodservice channels.
- For instance, Unilever plc applies fermentation-based processes across multiple food brands, operating more than 20 global food innovation kitchens focused on natural formulations.
Growth of Urbanization and Changing Dietary Habits
Urban lifestyles increase demand for convenient yet healthy food options. Fermented foods fit modern diets due to ready-to-eat formats. Busy consumers prefer products that combine nutrition and taste. Exposure to global cuisines boosts acceptance of fermented vegetables and beverages. Urban retail expansion improves product accessibility. Working populations adopt fermented snacks and drinks for daily consumption. Rising disposable income supports premium fermented offerings. This driver sustains steady volume growth across major metropolitan regions.
Key Trends & Opportunities
Product Innovation Across Non-Dairy Fermented Foods
Non-dairy fermented foods gain traction due to plant-based diet adoption. Fermented vegetables, cereals, and soy products attract vegan consumers. Manufacturers innovate with new flavors and textures to expand appeal. Advances in fermentation technology improve taste consistency. This trend reduces dependence on dairy-based products. Brands target lactose-intolerant and flexitarian consumers. Product diversification strengthens portfolio resilience. Non-dairy innovation creates growth opportunities across retail and foodservice segments.
- For instance, Meiji Holdings Co., Ltd. conducts extensive fermentation research utilizing various substrates to develop diverse food products and ensure consistent flavor profiles.
Growth of Online Retail and Premium Positioning
Online retail creates strong opportunities for fermented food brands. Digital platforms support niche and premium product visibility. Subscription models encourage repeat purchases of probiotic foods. Cold-chain logistics improvements support online expansion. Brands use direct channels to educate consumers. Premium pricing becomes viable through storytelling and health claims. Online reviews build trust for emerging brands. This trend supports higher margins and broader geographic reach.
- For instance, PepsiCo, Inc. operates a global network of distribution and warehouse facilities that support temperature-controlled direct delivery models.
Key Challenges
Short Shelf Life and Cold Chain Dependency
Fermented foods often require strict temperature control. Limited shelf life increases storage and transport complexity. Cold-chain failures risk product quality and safety. Smaller retailers face challenges managing refrigeration costs. Distribution in remote regions remains difficult. Product spoilage increases operational losses. Manufacturers invest heavily in packaging and logistics. These constraints limit market penetration in underdeveloped infrastructure regions.
Regulatory and Labeling Compliance Complexity
Regulatory standards for live cultures vary by region. Health claims face strict scrutiny from authorities. Labeling requirements differ across countries. Compliance increases time-to-market and costs. Smaller producers struggle with documentation and testing. Inconsistent regulations create market entry barriers. Brands must invest in regulatory expertise. These challenges slow innovation and cross-border expansion.
Regional Analysis
North America
North America holds a market share of 22.1% in the fermented foods market, supported by strong health awareness and high purchasing power. Consumers actively seek probiotic-rich foods to support digestion and immunity. Yogurt, kefir, kombucha, and fermented snacks see steady demand across the United States and Canada. Retail chains offer wide product assortments with strong cold-chain infrastructure. Product innovation focuses on low-sugar and functional variants. Clean-label positioning strengthens consumer trust. Foodservice adoption also supports volume growth. The region benefits from advanced processing capabilities and strong regulatory clarity for fermented food products.
Europe
Europe accounts for a market share of 27.6%, driven by deep-rooted fermentation traditions and high per capita consumption. Countries such as Germany, France, and Eastern European nations show strong demand for fermented dairy, vegetables, and bakery products. Consumers value traditional recipes, natural preservation, and flavor authenticity. Regulatory support for clean-label and natural foods strengthens market stability. Private-label fermented products perform well in supermarkets. Innovation in organic and artisanal offerings supports premiumization. The region maintains steady demand through cultural acceptance, strong retail penetration, and growing interest in gut health and preventive nutrition.
Asia Pacific
Asia Pacific leads the fermented foods market with a market share of 38.4%, reflecting widespread cultural integration of fermented products. Daily consumption of kimchi, miso, tempeh, fermented rice, and dairy supports high volumes. Large populations and rising urbanization drive sustained demand. Consumers recognize fermentation as a traditional health practice rather than a trend. Expanding middle-class income supports packaged and branded products. Modern retail growth improves accessibility. Manufacturers invest in scalable fermentation technologies to meet demand. The region benefits from both traditional consumption patterns and growing interest in functional packaged foods.
Rest of the World
The Rest of the World region holds a market share of 11.9%, supported by gradual dietary shifts and rising health awareness. Latin America shows growing interest in fermented dairy and beverages. The Middle East and Africa adopt fermented foods through expanding urban retail networks. Local fermentation traditions support baseline demand, while packaged products gain traction. Infrastructure development improves cold-chain capabilities. International brands expand presence through partnerships. Consumer education remains a key growth lever. Although smaller in scale, the region offers long-term growth potential driven by urbanization, nutrition awareness, and retail modernization.
Fermented Foods Market Segmentations:
By Product Type
- Dairy products
- Fermented beverages
- Fermented vegetables
- Fermented cereals and soy products
By Microorganism Type
- Lactic acid bacteria
- Yeast
- Molds
- Mixed cultures
By Distribution Channel
- Supermarkets and hypermarkets
- Convenience stores
- Online retail
- Specialty stores
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights strong competition led by Nestlé S.A., Danone S.A., Yakult Honsha Co., Ltd., Unilever plc, and PepsiCo, Inc.. These players focus on brand strength, scale, and science-backed formulations. Large companies invest in culture research, strain stability, and product consistency to protect market positions. Portfolio expansion across dairy, beverages, and plant-based fermented foods supports revenue stability. Strategic acquisitions help companies enter regional niches and premium categories. Private-label competition intensifies pressure on pricing in mature markets. Innovation centers on low-sugar recipes, clean-label positioning, and functional claims. Strong distribution networks and cold-chain control provide competitive advantages. Smaller regional brands compete through authenticity and traditional recipes. Overall competition remains intense, driven by health demand, innovation pace, and retail shelf visibility.
Key Player Analysis
- Nestlé S.A.
- Danone S.A.
- Yakult Honsha Co., Ltd.
- PepsiCo, Inc.
- Kraft Heinz Company
- Unilever plc
- General Mills, Inc.
- Hansen Holding A/S
- Fonterra Co-operative Group
- Meiji Holdings Co., Ltd.
Recent Developments
- In July 2025, PepsiCo, Inc. introduced Pepsi Prebiotic Cola, its first prebiotic-infused cola with functional fiber.
- In January 2025, Danone S.A. launched a new probiotic yogurt range aimed at gut-health conscious consumers.
- In 2025, Nestlé S.A. maintained fermented dairy and plant-based fermented product innovation in key markets as part of broader strategy.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Microorganism Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Focus on Gut Health and Immunity
Consumers increasingly associate fermented foods with digestive health and immune system support, leading to higher daily consumption of probiotic-rich products such as yogurt, kefir, and kombucha. Medical guidance and nutrition awareness programs further reinforce the perceived health benefits, driving repeat purchases across age groups.
Expansion of Clean-Label and Natural Food Preferences
The demand for foods made with natural preservation methods and minimal processing is boosting the popularity of fermented foods. Clean-label trends and regulatory pressure on synthetic additives encourage consumers to choose products with transparent ingredient lists, supporting market growth.
Growth of Urbanization and Changing Dietary Habits
Urban lifestyles and busy schedules are increasing the demand for convenient, ready-to-eat, and nutritious food options. Fermented foods fit these needs, and exposure to global cuisines is broadening acceptance of products like kimchi, miso, and fermented beverages, especially among younger and working populations.
Product Innovation in Non-Dairy and Functional Offerings
Manufacturers are expanding their portfolios with non-dairy fermented foods and premium functional products to cater to vegan, lactose-intolerant, and health-conscious consumers. Advances in fermentation technology and new flavor profiles are attracting a wider customer base and reducing reliance on traditional dairy segments.
Growth of Online Retail and Premium Positioning
The rise of online retail platforms enables brands to reach niche and premium consumer segments, offering subscription models and direct-to-consumer education. Improved cold-chain logistics and digital marketing support the expansion of specialty and high-margin fermented food products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Fermented Foods market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fermented Foods market projected to grow between 2024 and 2032?
Which Fermented Foods market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fermented Foods market?
Who are the leading companies in the Fermented Foods market?
Which region commanded the largest share of the Fermented Foods market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Dairy products
- 1.2.2 Fermented beverages
- 1.2.3 Fermented vegetables
- 1.2.4 Fermented cereals and soy products
- 1.3 By Microorganism Type
- 1.3.1 Lactic acid bacteria
- 1.3.2 Yeast
- 1.3.3 Molds
- 1.3.4 Mixed cultures
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 247579.92 million → 2032: USD 354788 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fermented Foods Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fermented Foods Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fermented Foods Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fermented Foods Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fermented Foods Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fermented Foods Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fermented Foods Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fermented Foods Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 247579.92 million → 2032: USD 354788 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fermented Foods Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dairy products
- 12.3.7.2 Fermented beverages
- 12.3.7.3 Fermented vegetables
- 12.3.7.4 Fermented cereals and soy products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Microorganism Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lactic acid bacteria
- 12.4.7.2 Yeast
- 12.4.7.3 Molds
- 12.4.7.4 Mixed cultures
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fermented Foods Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Fermented Foods Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Fermented Foods Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Nestlé S.A.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Danone S.A.
- 17.4 Yakult Honsha Co., Ltd.
- 17.5 PepsiCo, Inc.
- 17.6 Kraft Heinz Company
- 17.7 Unilever plc
- 17.8 General Mills, Inc.
- 17.9 Chr. Hansen Holding A/S
- 17.10 Fonterra Co-operative Group
- 17.11 Meiji Holdings Co., Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

