
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
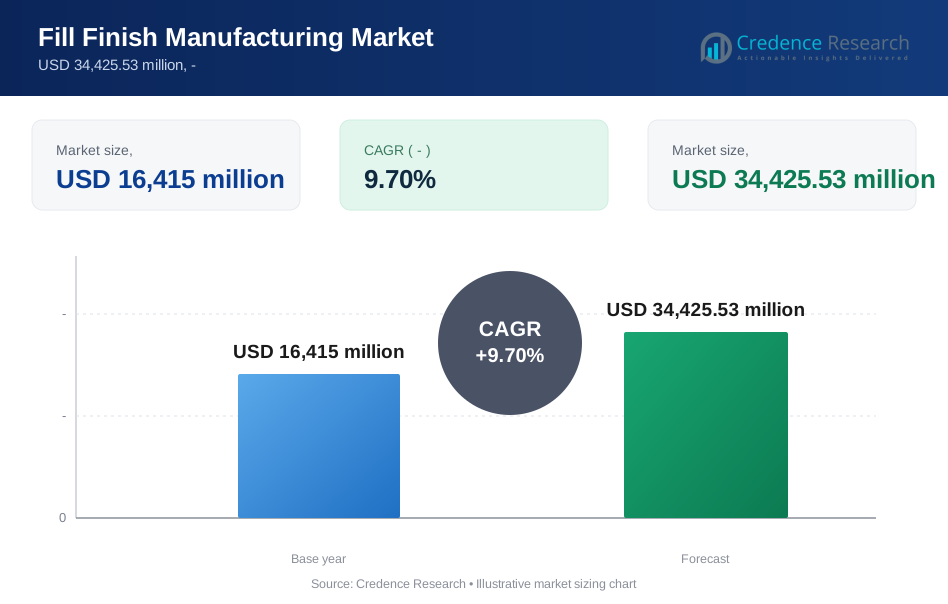
| Fill Finish Manufacturing Market Size 2024 | USD 16,415 Million |
| Fill Finish Manufacturing Market, CAGR | 9.70% |
| Fill Finish Manufacturing Market Size 2032 | USD 34,425.53 Million |
Market Overview:
The Fill Finish Manufacturing Market is poised for substantial growth, driven by the increasing demand for efficient and safe drug delivery systems. As of 2024, the global Fill Finish Manufacturing Market is valued at approximately USD 16,415 million and is projected to grow at a compound annual growth rate (CAGR) of 9.70% over the forecast period, reaching around USD 34,425.53 million by 2032. This robust growth reflects the rising emphasis on sterile manufacturing processes and the growing biopharmaceutical industry, which necessitates advanced fill finish capabilities.
Several key factors are contributing to the market's expansion. The increasing prevalence of chronic diseases and the corresponding demand for biologics and injectable therapies are significant drivers. Additionally, the rising complexity of drug formulations requires specialized fill finish technologies to ensure product integrity and patient safety. The integration of automation and digital technologies in manufacturing processes is further enhancing operational efficiency and reducing turnaround times.
Regionally, North America dominates the Fill Finish Manufacturing Market, primarily due to its well-established biopharmaceutical sector and stringent regulatory standards that necessitate high-quality manufacturing practices. Europe follows closely, driven by similar factors, alongside increasing investments in advanced manufacturing technologies. The Asia-Pacific region is expected to witness remarkable growth during the forecast period, fueled by a rapidly expanding biopharmaceutical market, increasing government support for healthcare infrastructure, and a growing focus on contract manufacturing services. Emerging economies in this region, such as China and India, present significant growth opportunities due to their large populations and escalating demand for advanced therapeutic solutions.
Market Drivers:
Growing Demand for Biologics and Sterile Products:
The global increase in demand for biologics, coupled with the need for sterile manufacturing processes, is a primary driver in the fill finish manufacturing market. According to the World Bank, biologics are expected to account for approximately 50% of new drug approvals by 2025. This surge in biologics, which require highly specialized fill finish processes, is pushing manufacturers to enhance their capabilities. Furthermore, the International Monetary Fund (IMF) notes that the pharmaceutical sector is projected to grow at around 6%, largely influenced by the need for advanced manufacturing solutions that ensure product safety and compliance with stringent regulatory standards. For instance, Gerresheimer launched Gx Elite, a new line of glass injection vials designed to enhance patient safety and production efficiency. This product emphasizes superior quality and increased shatter resistance, aligning with the rising expectations for product integrity in biologics.
Technological Advancements and Automation:
Technological advancements play a pivotal role in driving the fill finish manufacturing market. Automation and innovative technologies streamline operations, enhance production efficiency, and reduce human error. The World Health Organization (WHO) emphasizes the importance of adopting cutting-edge technologies to improve manufacturing processes, especially in sterile environments. The adoption of automation technologies, such as robotics and data analytics, is projected to increase operational efficiency by up to 30% by 2025, as highlighted in various industry reports. For instance, in October 2023, Datwyler introduced its ready-for-sterilization (RFS) combi-seals designed for cartridges used in injection devices. This innovation not only supports manufacturing efficiency but also addresses the growing need for automated solutions in the fill finish sector.
Regulatory Compliance and Quality Assurance:
Regulatory compliance remains a critical driver in the fill finish manufacturing landscape. Governments and health authorities worldwide are implementing stricter guidelines to ensure product safety and quality. The European Medicines Agency (EMA) and the U.S. Food and Drug Administration (FDA) continuously update their regulations, which necessitates manufacturers to adapt and invest in technologies that ensure compliance. For Instance, Datwyler partnered with Conserva UK to establish a supply chain for pharmaceutical primary packaging in the UK market. This strategic collaboration aims to strengthen Datwyler's presence by ensuring compliance with local regulations while meeting the stringent quality demands of their customer network. Such partnerships are crucial in navigating the complex regulatory environment and ensuring product integrity throughout the manufacturing process.
Expansion of Manufacturing Capabilities:
The expansion of manufacturing capabilities is another significant driver in the fill finish manufacturing market. Companies are increasingly investing in new facilities and technologies to accommodate the growing demand for sterile products. The IMF forecasts that the pharmaceutical manufacturing sector will require a substantial increase in production capacity, particularly in emerging markets, to meet global health needs.
For instance, on February 8, 2024, Alcami Corporation announced the strategic expansion of its sterile fill/finish manufacturing capacity. The addition of a new sterile fill/finish line with an isolator and two lyophilizers at its Charleston, SC, facility demonstrates the company's commitment to meeting the rising demand for high-quality sterile products. This expansion reflects broader industry trends where manufacturers are scaling their operations to keep pace with market needs and technological advancements. The fill finish manufacturing market is driven by several interlinked factors, including the growing demand for biologics, technological advancements, regulatory compliance, and expansion of manufacturing capabilities. With global health authorities like the World Bank and WHO emphasizing the importance of high-quality production processes, manufacturers are compelled to innovate and adapt. The ongoing developments in this sector not only highlight the increasing complexity of drug manufacturing but also underline the vital role of strategic partnerships and technological integration in meeting future challenges.
Market Trends:
Increased Focus on Sustainability:
One of the most significant trends in the fill finish manufacturing market is the growing emphasis on sustainability. As global awareness of environmental issues rises, pharmaceutical companies are increasingly adopting eco-friendly practices in their manufacturing processes. According to the International Monetary Fund (IMF), sustainable manufacturing practices can reduce waste and energy consumption by up to 25%, contributing to a more environmentally responsible industry. Regulatory bodies and health organizations are encouraging pharmaceutical companies to implement sustainable practices, including the use of recyclable materials and reduction of carbon footprints. The World Health Organization (WHO) has highlighted the importance of sustainability in healthcare manufacturing, advocating for practices that not only enhance product quality but also minimize environmental impact. For instance, Stevanato Group unveiled two new offerings to enhance small batch pharmaceutical manufacturing: the EZ-fill Kit and a non-GMP laboratory fill and finish service at its Technology Excellence Centers (TEC). The EZ-fill Kit expands the company’s existing platform of pre-sterilized containment solutions, enabling customers to effectively screen various primary packaging options while maintaining a focus on sustainability. This move illustrates how companies are adapting to market demands for environmentally friendly practices without compromising on quality.
Shift Towards Personalized Medicine:
Another prominent trend in the fill finish manufacturing sector is the shift towards personalized medicine. As the healthcare landscape evolves, there is a growing demand for tailored treatment options that cater to individual patient needs. This trend is supported by research from various governmental health agencies, indicating that personalized medicine can lead to better patient outcomes and improved treatment adherence. The rise of biologics and advanced therapies necessitates specialized fill finish manufacturing processes that can accommodate small batch sizes and unique formulation requirements. According to reports from the World Bank, the market for personalized medicine is expected to grow significantly, driven by advancements in genomics and biotechnology. To capitalize on this trend, manufacturers are investing in flexible production capabilities that can handle a variety of products and formulations. Companies are increasingly adopting modular manufacturing systems that allow for quick adjustments in production lines to accommodate diverse drug formulations. The increased regulatory focus on personalized medicine is pushing companies to enhance their fill finish capabilities, ensuring that they can meet the unique demands of this evolving market. The fill finish manufacturing market is undergoing significant transformation, driven by trends such as sustainability and the shift towards personalized medicine. As global organizations like the IMF and WHO emphasize the importance of environmentally responsible practices and tailored healthcare solutions, pharmaceutical companies are adapting their manufacturing processes accordingly. The introduction of innovative products, like Stevanato Group's EZ-fill Kit, reflects the industry's commitment to meeting these changing demands while maintaining high-quality standards. As these trends continue to evolve, they will undoubtedly shape the future landscape of the fill finish manufacturing market, creating opportunities for growth and innovation.
Market Challenge Analysis:
Regulatory Compliance and Quality Assurance One of the foremost challenges facing the Fill Finish Manufacturing Market is navigating the complex landscape of regulatory compliance and quality assurance. Pharmaceutical and biotechnology companies must adhere to stringent guidelines set forth by regulatory bodies such as the FDA in the United States and the EMA in Europe. These regulations mandate rigorous testing, documentation, and validation processes to ensure that products meet safety and efficacy standards. The continuous evolution of these regulations can pose significant challenges for manufacturers, who must remain agile and adaptable to comply with new requirements. Failure to meet these standards can lead to product recalls, financial penalties, and damage to brand reputation, which can significantly impact market growth.
Moreover, maintaining quality throughout the manufacturing process is critical, especially in fill finish operations where sterility and precision are paramount. Manufacturers face the constant challenge of implementing advanced technologies and processes that ensure high-quality outputs while also managing costs. This balance is particularly difficult for smaller firms and contract manufacturers that may lack the resources to invest in cutting-edge equipment or to navigate complex regulatory landscapes. As a result, ensuring compliance and quality remains a significant hurdle that can affect overall operational efficiency and market competitiveness.
Supply Chain Disruptions and Resource Constraints Another significant challenge impacting the Fill Finish Manufacturing Market is supply chain disruptions and resource constraints. The global pharmaceutical supply chain is intricate and often vulnerable to various external factors, including geopolitical tensions, natural disasters, and pandemics, as demonstrated during the COVID-19 crisis. Such disruptions can lead to shortages of critical raw materials, equipment, and packaging components, which can halt production and delay product launches. Manufacturers must develop strategies to mitigate these risks, such as diversifying their supplier base and investing in local sourcing to reduce reliance on global supply chains.
In addition to external disruptions, resource constraints also pose challenges in terms of workforce availability and skilled labor. The fill finish manufacturing sector requires highly specialized personnel who are trained in compliance, quality control, and advanced manufacturing technologies. The ongoing shortage of skilled labor in many regions makes it increasingly difficult for companies to maintain operational efficiency and meet market demand. Companies may need to invest in training and development programs to build a skilled workforce, which can be both time-consuming and costly. Addressing these supply chain and resource challenges is crucial for manufacturers aiming to sustain growth and competitive advantage in the rapidly evolving fill finish manufacturing landscape.
Market Segmentation Analysis:
By Type
The Fill Finish Manufacturing Market is segmented into two primary types: vials and syringes. Vials are widely used for storing and delivering liquid medications, particularly biologics, due to their compatibility with various drug formulations. Syringes, on the other hand, are increasingly preferred for their ease of use and patient convenience, particularly in self-administration scenarios. The growth of prefilled syringes is also notable, driven by the rising demand for ready-to-use solutions that enhance patient adherence.
By Technology
The market is categorized based on technology into conventional filling and automated filling systems. Conventional filling processes are still prevalent but are gradually being replaced by automated systems that offer greater precision and efficiency. Automated filling technologies are becoming the standard due to their ability to minimize human error, improve throughput, and ensure sterility in the manufacturing environment. Advanced technologies, such as isolators and robotic systems, are gaining traction, further enhancing the capabilities of fill finish operations.
By End-User
The Fill Finish Manufacturing Market serves various end-users, including pharmaceutical companies, contract manufacturing organizations (CMOs), and research institutions. Pharmaceutical companies constitute the largest segment, driven by the need for reliable and compliant manufacturing solutions. CMOs are experiencing significant growth as they provide specialized services to smaller biotech firms and emerging companies looking to outsource their fill finish processes. Research institutions also represent a crucial segment, requiring fill finish capabilities for clinical trials and product development initiatives.
Segmentation:
Based on Product Type:
- Vials • Syringes • Prefilled Syringes • Other Delivery Systems
Based on Technology:
- Conventional Filling Systems • Automated Filling Systems • Robotic Filling Systems • Isolators
Based on End-User:
- Pharmaceutical Companies • Contract Manufacturing Organizations (CMOs) • Research Institutions • Biotech Firms
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America (40% Market Share) North America holds the largest share of the Fill Finish Manufacturing Market, accounting for approximately 40% of the total market. This dominance is primarily driven by the well-established biopharmaceutical sector and stringent regulatory requirements that necessitate high-quality manufacturing processes. The United States, being home to numerous pharmaceutical and biotechnology companies, has witnessed significant investments in advanced manufacturing technologies and innovation. The growing demand for biologics, coupled with the increasing prevalence of chronic diseases, has further fueled market growth in this region.
Additionally, the presence of leading market players and contract manufacturing organizations (CMOs) enhances competition and encourages technological advancements. The integration of automation and digital solutions in manufacturing processes also contributes to efficiency and compliance with regulatory standards. Furthermore, North America benefits from a strong healthcare infrastructure and extensive R&D activities, fostering a conducive environment for the fill finish manufacturing sector.
Europe (35% Market Share) Europe follows closely, representing about 35% of the Fill Finish Manufacturing Market. The region is characterized by its strong pharmaceutical industry and a robust regulatory framework that ensures product quality and safety. Countries like Germany, the United Kingdom, and France are key players, driven by their advanced healthcare systems and significant investments in research and development.
The increasing demand for advanced drug delivery systems and sterile manufacturing processes is propelling market growth across Europe. The region's focus on biopharmaceutical innovation, particularly in the areas of gene and cell therapies, necessitates sophisticated fill finish solutions. Furthermore, the rise of contract manufacturing services enables smaller biotech firms to access state-of-the-art facilities, driving the market forward. Europe’s commitment to sustainability and environmentally friendly practices also influences the adoption of new technologies in the fill finish sector.
Asia-Pacific (25% Market Share) The Asia-Pacific region is experiencing remarkable growth in the Fill Finish Manufacturing Market, currently holding about 25% of the market share. This growth is largely attributed to the rapidly expanding biopharmaceutical sector in countries such as China and India. The increasing demand for high-quality pharmaceutical products, coupled with rising healthcare expenditures, is driving investment in manufacturing capabilities and infrastructure. Governments in the region are actively promoting initiatives to improve healthcare services, further enhancing the appeal of the fill finish manufacturing sector. As the regulatory landscape evolves, there is a growing emphasis on compliance and quality assurance, which is prompting manufacturers to adopt advanced technologies and practices. The rise of contract manufacturing organizations in Asia-Pacific also presents significant opportunities, enabling local firms to cater to global pharmaceutical companies seeking cost-effective and high-quality solutions.
Moreover, the region benefits from a large population base and a growing awareness of healthcare issues, which drives demand for injectable medications. This trend is expected to continue, positioning Asia-Pacific as a key player in the global fill finish manufacturing landscape.
Key Player Analysis:
- Asymchem Inc.
- Syntegon Technology GmbH
- I.M.A. INDUSTRIA MACCHINE AUTOMATICHE S.P.A
- West Pharmaceutical Services, Inc.
- Gerresheimer AG
- AptarGroup, Inc.
- Dätwyler Holding Inc.
- Stevanato Group
- OPTIMA
- SGD Pharma
- Nipro Corporation
- Bausch Advanced Technology Group
Competitive Analysis:
The Fill Finish Manufacturing Market is characterized by intense competition among key players striving to enhance their market positions through innovation and strategic partnerships. Major companies such as Gerresheimer, Stevanato Group, and Datwyler lead the market by offering advanced packaging solutions and sterile manufacturing capabilities tailored to the needs of the biopharmaceutical sector. These organizations are investing significantly in research and development to create new products, such as prefilled syringes and automated filling systems, which enhance efficiency and ensure compliance with stringent regulatory standards. Additionally, many players are focusing on automation and digital technologies to streamline operations and reduce costs. The rise of contract manufacturing organizations (CMOs) has also intensified competition, as they provide flexible and cost-effective solutions for smaller biotech firms that require high-quality fill finish services without the capital investment in manufacturing facilities. Furthermore, regional players in Asia-Pacific are emerging, capitalizing on the growing demand for affordable and efficient manufacturing options, which adds another layer of complexity to the competitive landscape. Strategic collaborations and partnerships, such as Datwyler’s recent alliance with Conserva UK, are becoming increasingly common, as companies seek to enhance their supply chain capabilities and expand their geographical reach. Overall, the competitive dynamics of the Fill Finish Manufacturing Market necessitate continuous innovation and adaptation to market trends, with companies striving to differentiate themselves through technological advancements, quality assurance, and customer-centric solutions. As the market evolves, organizations that successfully navigate these competitive pressures while meeting the ever-growing demand for injectable therapies will position themselves for sustained growth and success.
Recent Developments:
- In October 2023, Gerresheimer launched Gx Elite, a new product line of glass injection vials designed to enhance patient safety and improve production efficiency. This range emphasizes superior quality and increased shatter resistance.
- Also in October 2023, Datwyler introduced its ready-for-sterilization (RFS) combi-seals, specifically designed for cartridges used in injection devices such as pens and autoinjectors.
- In December 2023, Datwyler partnered with Conserva UK to establish a supply chain for pharmaceutical primary packaging within the UK market. This strategic collaboration aims to strengthen Datwyler's presence in the UK by leveraging Conserva UK as the primary interface for its esteemed customer network.
- On February 8, 2024, Alcami Corporation announced the strategic expansion of its sterile fill/finish manufacturing capacity. The company will add a new sterile fill/finish line with an isolator and two lyophilizers at its existing manufacturing campus in Charleston, SC.
- On January 24, 2024, Stevanato Group unveiled two new offerings to enhance small batch pharmaceutical manufacturing: the EZ-fill Kit and a non-GMP laboratory fill and finish service at its Technology Excellence Centers (TEC). The EZ-fill Kit expands Stevanato Group’s existing platform of pre-sterilized containment solutions, including vials, cartridges, and syringes, enabling customers to effectively screen various primary packaging options alongside their drug products.
Market Concentration & Characteristics:
The Fill Finish Manufacturing Market exhibits moderate concentration, with a few key players dominating a significant portion of the market share while allowing room for smaller firms and contract manufacturing organizations (CMOs) to thrive. Major companies like Gerresheimer, Stevanato Group, and Datwyler lead the industry through their advanced technological capabilities and established reputations for quality and compliance. These players are known for their extensive product portfolios, including glass vials, syringes, and specialized delivery systems, which cater to the growing demand for biologics and injectables. The market is characterized by a strong emphasis on innovation, driven by the need for enhanced patient safety and efficient production processes. Companies are increasingly investing in automation and digital technologies to improve operational efficiency and reduce human error, thus aligning with regulatory requirements. Additionally, the rise of CMOs has introduced greater flexibility into the market, enabling biopharmaceutical firms, especially smaller biotech companies, to access high-quality fill finish services without substantial capital investments. This trend fosters a competitive environment that encourages collaboration and strategic partnerships. Overall, the Fill Finish Manufacturing Market reflects a dynamic landscape where innovation, regulatory compliance, and adaptability to customer needs are critical for success, allowing both established players and emerging companies to find their niche within this evolving sector.
Report Coverage:
This report provides a comprehensive analysis of the Fill Finish Manufacturing Market, encompassing key trends, growth drivers, and challenges impacting the industry. It examines market dynamics across various segments, including product types, technologies, and end-users, offering insights into the competitive landscape dominated by major players such as Gerresheimer, Stevanato Group, and Datwyler. The report delves into regional analyses, highlighting the market shares of North America, Europe, Asia-Pacific, and other regions, while also assessing the implications of regulatory compliance and quality assurance on market operations. Additionally, it explores the rise of contract manufacturing organizations (CMOs) and their role in enhancing flexibility and efficiency within the supply chain. By providing in-depth evaluations of market concentration and characteristics, the report identifies opportunities for innovation and strategic partnerships that can drive growth in this sector. Through quantitative data and qualitative insights, this report aims to equip stakeholders-including manufacturers, investors, and industry analysts-with the necessary knowledge to navigate the evolving landscape of fill finish manufacturing effectively. The analysis also includes forecasts for market growth from 2024 to 2032, ensuring a forward-looking perspective on industry developments and potential investment areas.
Future Outlook:
- The Fill Finish Manufacturing Market is expected to continue its robust growth, driven by increasing demand for biologics and injectable therapies.
- Advancements in automation and digital technologies will enhance production efficiency and reduce operational costs.
- Regulatory compliance will remain a key focus, prompting ongoing investments in quality assurance measures.
- The rise of contract manufacturing organizations (CMOs) will provide flexibility and scalability for pharmaceutical companies.
- Emerging markets, particularly in Asia-Pacific, will present significant growth opportunities due to expanding healthcare infrastructures.
- Collaborative partnerships between manufacturers and technology providers will foster innovation in packaging solutions.
- Sustainability initiatives will gain traction, influencing the development of eco-friendly packaging materials.
- Increasing prevalence of chronic diseases will drive the demand for safe and effective drug delivery systems.
- The market will witness greater integration of advanced technologies, such as artificial intelligence and machine learning, to optimize processes.
- Overall, the Fill Finish Manufacturing Market is poised for a dynamic evolution, adapting to changing consumer needs and regulatory landscapes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Biologics and Sterile Products
The increasing prevalence of chronic diseases and the shift toward biologics and injectable therapies require advanced fill finish manufacturing processes to ensure sterility and product integrity, driving significant investments and capacity expansion in this market.
Technological Advancements and Automation
The integration of automation, robotics, and digital technologies in fill finish manufacturing is enhancing operational efficiency, reducing human error, and enabling higher throughput, which is crucial for meeting the rising complexity and volume of modern drug formulations.
Regulatory Compliance and Quality Assurance
Stringent regulatory standards from agencies like the FDA and EMA necessitate continuous upgrades in manufacturing processes and quality systems, compelling companies to invest in advanced technologies and robust quality assurance to maintain compliance and market access.
Expansion of Manufacturing Capabilities
Pharmaceutical companies and CMOs are expanding their fill finish manufacturing capacities, particularly in emerging markets, to meet global demand for sterile products and to support the growing pipeline of biologics and personalized medicines.
Sustainability Initiatives
Increasing focus on eco-friendly manufacturing practices and sustainable packaging solutions is prompting manufacturers to adopt greener technologies and materials, aligning with regulatory and consumer expectations for reduced environmental impact.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Fill Finish Manufacturing Market?
How much is the market expected to grow by 2032?
Which regions are leading the Fill Finish Manufacturing Market?
What are the main factors driving market expansion?
What are the primary challenges and opportunities in the Fill Finish Manufacturing Market?
Who are the major players in the global fill-finish manufacturing equipment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Pharmaceutical Companies
- 1.2.2 Contract Manufacturing Organizations (CMOs)
- 1.2.3 Research Institutions
- 1.2.4 Biotech Firms
- 1.3 By Technology
- 1.3.1 Conventional Filling Systems
- 1.3.2 Automated Filling Systems
- 1.3.3 Robotic Filling Systems
- 1.3.4 Isolators
- 1.4 By Product Type
- 1.4.1 Vials
- 1.4.2 Syringes
- 1.4.3 Prefilled Syringes
- 1.4.4 Other Delivery Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 16,415 million → Forecast year: USD 34,425.53 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fill Finish Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fill Finish Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fill Finish Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fill Finish Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fill Finish Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fill Finish Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fill Finish Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fill Finish Manufacturing Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 16,415 million → Forecast year: USD 34,425.53 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fill Finish Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceutical Companies
- 12.3.7.2 Contract Manufacturing Organizations (CMOs)
- 12.3.7.3 Research Institutions
- 12.3.7.4 Biotech Firms
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional Filling Systems
- 12.4.7.2 Automated Filling Systems
- 12.4.7.3 Robotic Filling Systems
- 12.4.7.4 Isolators
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Vials
- 12.5.7.2 Syringes
- 12.5.7.3 Prefilled Syringes
- 12.5.7.4 Other Delivery Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fill Finish Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fill Finish Manufacturing Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fill Finish Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fill Finish Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gerresheimer AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stevanato Group
- 18.4 Dätwyler Holding Inc.
- 18.5 West Pharmaceutical Services, Inc.
- 18.6 Syntegon Technology GmbH
- 18.7 AptarGroup, Inc.
- 18.8 I.M.A. INDUSTRIA MACCHINE AUTOMATICHE S.P.A
- 18.9 OPTIMA
- 18.10 SGD Pharma
- 18.11 Nipro Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

