
Market Overview:
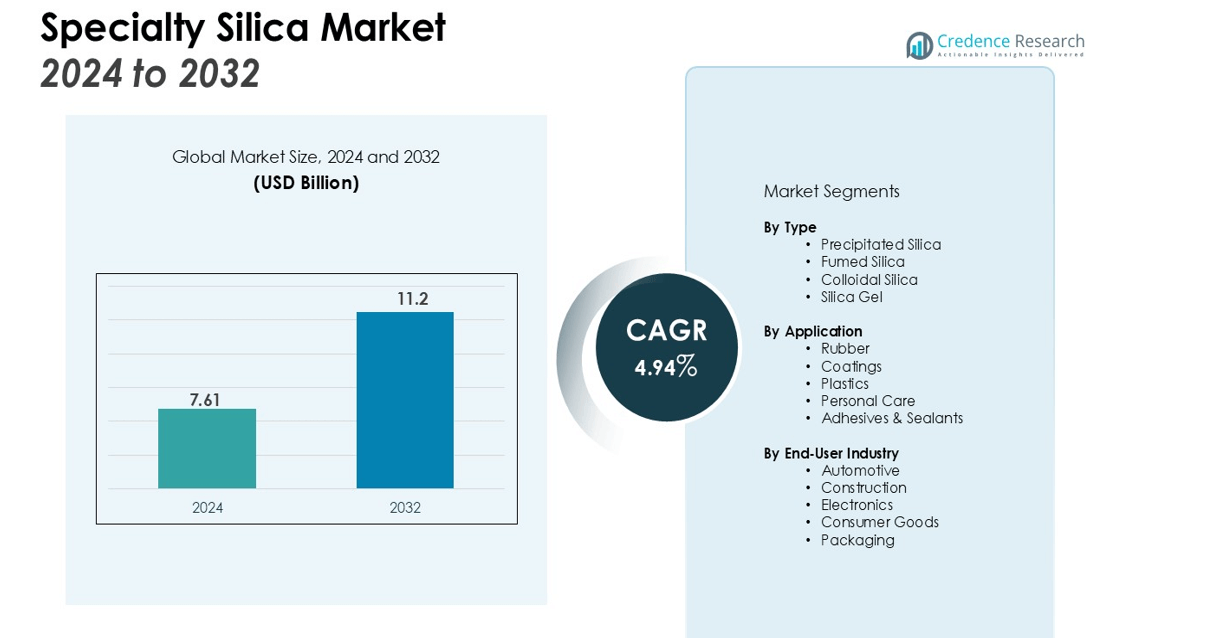
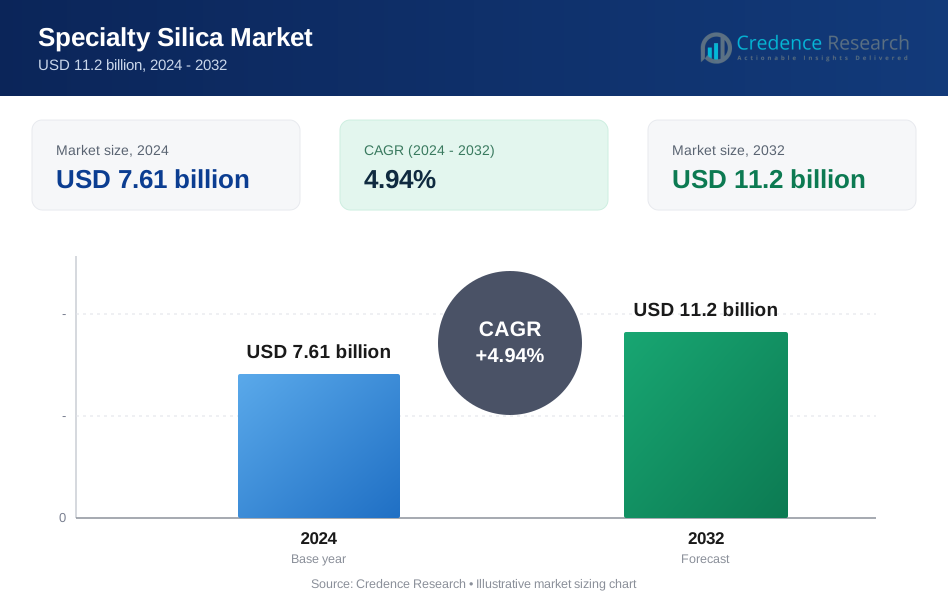
The Specialty Silica Market size was valued at USD 7.61 billion in 2024 and is anticipated to reach USD 11.2 billion by 2032, at a CAGR of 4.94% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Specialty Silica Market Size 2025 | USD 7.61 Billion |
| Specialty Silica Market, CAGR | 4.94% |
| Specialty Silica Market Size 2032 | USD 11.2 Billion |
Market growth is fueled by increasing demand for green tires, as specialty silica improves fuel efficiency and reduces rolling resistance. Expanding use in coatings, adhesives, and sealants enhances product performance by improving durability and dispersion. Additionally, strong uptake in personal care products, particularly in cosmetics and oral care, highlights silica’s versatility. Growing focus on lightweight materials and eco-friendly additives across industries further strengthens the market outlook.
Regionally, Asia-Pacific leads the market, supported by robust automotive production, rapid industrialization, and growing consumer goods demand. North America demonstrates steady growth due to strong investments in advanced materials and stringent regulations promoting sustainable products. Europe benefits from technological innovation and a well-established automotive sector, while emerging economies in Latin America and the Middle East & Africa are witnessing rising adoption, driven by infrastructure expansion and industrial diversification.
Market Insights:
- The Specialty Silica Market was valued at USD 7.61 billion in 2024 and will reach USD 11.2 billion by 2032, growing at a CAGR of 4.94%.
- Demand for green tires continues to rise as silica improves fuel efficiency, wet grip, and durability in automotive applications.
- Expanding use in coatings, adhesives, and sealants enhances product quality by strengthening durability and improving dispersion properties.
- The personal care industry boosts demand with silica’s role in absorption, thickening, and texture improvement in cosmetics and oral care.
- High production costs and raw material supply volatility remain key challenges, pressuring smaller producers and limiting scalability.
- Asia-Pacific dominates with 45% share, supported by strong automotive output, infrastructure growth, and consumer goods expansion.
- North America holds 23% share and Europe 21%, both driven by sustainability regulations, advanced industries, and innovation in eco-friendly applications.
Market Drivers:
Rising Demand for Green Tires and Fuel-Efficient Automotive Solutions
Specialty Silica plays a vital role in the automotive industry by enhancing tire performance. It improves rolling resistance, wet grip, and durability, making it essential for green tire production. Global policies that encourage reduced carbon emissions have accelerated the adoption of silica-based tires. Automotive manufacturers view it as a strategic material for balancing performance and sustainability in high-demand markets.
- For instance, Madhu Silica Pvt. Ltd., India’s largest precipitated silica manufacturer, has an installed capacity of 270,000 metric tonnes per annum as of March 31, 2024, to meet the growing demand from the tire industry.
Expanding Applications in Personal Care and Cosmetics Industry
The personal care sector drives significant demand for Specialty Silica due to its versatile properties. It provides superior absorption, matting, and thickening functions in cosmetics and oral care products. Rising consumer preference for premium skincare and dental care boosts silica usage in formulations. It has become integral for global brands aiming to improve texture, shelf life, and product performance.
- For instance, Evonik’s SIPERNAT® 500 LS specialty silica, designed for personal care, has a high absorption capacity and can hold up to 320 grams of liquid per 100 grams of silica, which helps create dry, free-flowing powders from liquid ingredients.
Increasing Role in Coatings, Adhesives, and Sealants for Industrial Use
Specialty Silica supports the coatings, adhesives, and sealants segment by improving dispersion, mechanical strength, and anti-settling properties. Industries such as construction, packaging, and electronics rely on these materials to deliver high-quality and durable products. Growing infrastructure investment and product innovation strengthen the demand for silica-based additives. It ensures consistent performance and broad applicability in industrial environments.
Growing Focus on Lightweight Materials and Sustainable Industrial Practices
Industries increasingly seek sustainable and lightweight solutions, driving demand for Specialty Silica. It reduces environmental impact while providing superior reinforcement and processing advantages. Manufacturers leverage silica in polymer and composite applications to achieve strength without added weight. The shift toward eco-friendly materials positions it as a critical enabler of sustainable industrial growth.
Market Trends:
Advancements in High-Performance Materials and Functional Applications
Specialty Silica is witnessing strong demand from industries focused on advanced performance materials. It supports the automotive sector through green tire manufacturing and aligns with global sustainability goals. The coatings and adhesives industries adopt it for improved durability, dispersion, and strength in high-demand environments. In electronics, silica-based materials are gaining traction due to their thermal stability and insulation properties. The growing emphasis on lightweight yet strong components across manufacturing sectors continues to fuel adoption. It is increasingly viewed as a versatile enabler of performance across multiple applications.
- For instance, Evonik's ULTRASIL® silica/silane system, when used in the production of green passenger car tires, enables a reduction of up to 1.4 metric tons of CO2 equivalent emissions over a driving distance of 150,000 km.
Shift Toward Sustainable Production and Eco-Friendly Solutions
Specialty Silica production trends highlight the industry’s focus on low-emission and sustainable practices. Companies are investing in energy-efficient manufacturing and innovative recycling methods to reduce environmental impact. Personal care and cosmetics brands prefer silica-based products due to their eco-friendly characteristics and safe formulations. Demand for renewable feedstock and biodegradable solutions strengthens its market positioning across global industries. The construction and infrastructure sectors also explore sustainable silica use to meet stricter regulations. It reflects a growing alignment between industrial innovation and environmental responsibility, driving long-term growth opportunities.
- For instance, Evonik developed its TEGO® Therm line of silica-based additives that improve the performance of thermal insulation coatings, offering heat resistance for industrial pipelines and components at continuous temperatures as high as 250 degrees Celsius, thereby reducing energy loss.
Market Challenges Analysis:
High Production Costs and Complex Manufacturing Requirements
Specialty Silica faces challenges linked to high production costs and energy-intensive processes. Manufacturers must balance the demand for quality with the expense of raw materials and advanced technologies. Strict environmental regulations on emissions and waste management further raise operational costs. Smaller producers often struggle to compete due to limited resources and higher capital requirements. It remains difficult for companies to scale efficiently while ensuring consistent quality and compliance.
Market Competition and Volatility in Raw Material Supply
Specialty Silica encounters intense competition from alternative materials that offer lower costs or easier availability. Volatility in raw material supply chains creates risks for stable production and timely delivery. Global disruptions, trade restrictions, or regional shortages can affect profitability and customer trust. It requires continuous innovation and investment to differentiate products in a crowded market. Price pressure from major buyers adds another layer of challenge for sustaining long-term margins.
Market Opportunities:
Rising Potential in Green Technologies and Automotive Applications
Specialty Silica holds strong opportunities in the global shift toward green technologies and sustainable mobility. The growing demand for fuel-efficient and eco-friendly tires creates a robust platform for silica adoption. Governments support policies that emphasize reduced emissions and energy efficiency, boosting its relevance in the automotive industry. Emerging markets with rapid vehicle production present further expansion avenues. It is expected to remain a critical enabler of performance in advanced tire and mobility solutions.
Expanding Role in High-Growth Industries and Sustainable Consumer Products
Specialty Silica is set to benefit from rising demand in personal care, electronics, and construction. Its use in cosmetics and oral care aligns with consumer preference for safer, eco-friendly products. Growth in electronics manufacturing drives opportunities for thermal insulation and enhanced material performance. Sustainable construction trends also increase reliance on silica-based additives. It is well-positioned to capture growth through innovation and alignment with environmental responsibility in consumer and industrial sectors.
Market Segmentation Analysis:
By Type
Specialty Silica is segmented into precipitated silica, fumed silica, colloidal silica, and silica gel. Precipitated silica dominates due to its extensive use in green tires and rubber applications. Fumed silica finds strong demand in adhesives, coatings, and sealants for its reinforcing and rheology control properties. Colloidal silica supports electronics, precision casting, and polishing industries with high purity and stability. Silica gel continues to be relevant in desiccants and packaging solutions.
- For instance, to meet high demand from the tire industry, Evonik Industries increased its annual production capacity for precipitated silica at its site in Adapazari, Turkey, by an additional 40,000 metric tons.
By Application
Specialty Silica supports diverse applications including rubber, coatings, plastics, and personal care. The rubber segment leads due to rising demand for low-emission and fuel-efficient tires. Coatings and adhesives benefit from silica’s role in improving dispersion, scratch resistance, and durability. Plastics adopt it to enhance strength, reduce weight, and improve surface finish. Personal care remains a fast-growing application, where it provides absorption, matting, and stability.
- For instance, Cabot Corporation is enhancing its supply for the coatings and adhesives markets by constructing a new fumed silica facility designed with a manufacturing capacity of 8,000 metric tons per year.
By End-Use Industry
Specialty Silica is adopted across automotive, construction, electronics, and consumer goods industries. Automotive leads through tire manufacturing, supported by global emission standards and demand for performance tires. Construction and infrastructure benefit from silica’s role in coatings and sealants. Electronics rely on high-purity grades for insulation and polishing. Consumer goods, particularly cosmetics and oral care, continue to expand usage, making it a versatile material across multiple industries.
Segmentations:
- By Type
- Precipitated Silica
- Fumed Silica
- Colloidal Silica
- Silica Gel
- By Application
- Rubber
- Coatings
- Plastics
- Personal Care
- Adhesives & Sealants
- By End-Use Industry
- Automotive
- Construction
- Electronics
- Consumer Goods
- Packaging
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
Asia-Pacific Leading Through Industrial Expansion and Automotive Growth
Asia-Pacific holds 45% share of the Specialty Silica market, making it the dominant region. Rapid industrialization, strong automotive production, and expanding construction activities continue to drive demand. Countries like China, India, and Japan lead consumption due to large-scale tire manufacturing and rising infrastructure investment. Consumer goods and personal care industries also support steady market uptake. Regional manufacturers invest heavily in capacity expansion to meet both domestic and export demand. It remains the fastest-growing region, supported by favorable government policies and cost-effective production capabilities.
North America Demonstrating Steady Adoption Across Key Industries
North America accounts for 23% share of the Specialty Silica market, supported by its advanced industries. Adoption is strong in automotive, electronics, and personal care, with companies focusing on eco-friendly applications. The region emphasizes sustainability, aligning silica use with regulations and consumer expectations. High investment in R&D encourages innovation in high-performance and specialized grades. Growth in electric vehicles further strengthens demand for green tires. It continues to benefit from technological advancements and a well-established industrial base.
Europe Advancing Through Sustainability and Technological Innovation
Europe represents 21% share of the Specialty Silica market, backed by sustainability-driven growth. The automotive sector, particularly in Germany, drives high demand for silica-based green tires. Strong growth in cosmetics and personal care markets across France and the UK supports diversified applications. Regional companies emphasize innovation in sustainable production processes to strengthen competitiveness. It remains an influential region, combining advanced infrastructure with regulatory support to enhance long-term demand.
Key Player Analysis:
- 3M
- Cabot
- Fuji Silysia Chemical
- Imerys
- Tata Chemicals
- Wacker Chemie
- Denka Company
- Evonik Industries
- Madhu Silica
- Oriental Silicas
- Qemetica
- Nouryon
Competitive Analysis:
The Specialty Silica market is highly competitive, with global and regional players focusing on innovation, sustainability, and product quality to strengthen their position. Leading companies invest in advanced technologies to enhance performance while reducing environmental impact, while strategic mergers, acquisitions, and capacity expansions expand their market presence. Specialty Silica producers target diverse sectors such as automotive, personal care, and construction to secure growth opportunities, and it remains vital for them to balance cost efficiency with compliance to strict regulations. Competitors differentiate by offering tailored solutions for green tires, eco-friendly coatings, and advanced electronics, creating a market landscape where established corporations and emerging players compete for share. Long-term success depends on R&D investment, reliable supply chains, and alignment with sustainability-driven demand.
Recent Developments:
- In July 2025, Cabot launched its new LITX® 95F conductive carbon, a material specifically engineered for use in energy storage systems.
- In May 2025, Denka announced the indefinite suspension of operations at its Denka Performance Elastomer (DPE) facility in LaPlace, Louisiana, citing environmental regulations and increasing costs.
- In January 2025, Evonik launched Smart Effects, a new business entity created through the strategic merger of its Silica and Silanes business lines, which together employ 3,500 people globally.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End-Use Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Specialty Silica will gain wider acceptance in green tire manufacturing driven by global emission reduction policies.
- Demand from the personal care sector will strengthen due to its role in high-performance cosmetics and oral care products.
- It will see increased adoption in electronics where thermal stability and insulation properties are critical.
- Construction and infrastructure industries will continue integrating silica in coatings, adhesives, and sealants for improved durability.
- Producers will invest in sustainable production methods to align with tightening environmental regulations.
- It will benefit from rising demand for lightweight materials across automotive, aerospace, and packaging industries.
- Global players will expand capacity in Asia-Pacific to leverage cost advantages and serve high-growth markets.
- Continuous R&D will create advanced grades with enhanced purity and functional properties for specialized applications.
- Market competition will intensify, encouraging companies to differentiate through innovation and customer-focused product solutions.
- Emerging economies in Latin America and the Middle East & Africa will create new opportunities through industrial diversification and infrastructure projects.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Specialty Silica, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Specialty Silica projected to grow between 2024 and 2032?
Which Specialty Silica segment held the largest share in 2024?
What are the primary factors fueling the growth of the Specialty Silica?
Who are the leading companies in the Specialty Silica?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Specialty Silica Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Specialty Silica Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7.61 billion → 2032: USD 11.2 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Specialty Silica Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Specialty Silica Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Specialty Silica Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Specialty Silica Market Drivers
- 3.3 Specialty Silica Market Restraints & Challenges
- 3.4 Specialty Silica Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Specialty Silica Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Specialty Silica Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Specialty Silica category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Specialty Silica Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Specialty Silica Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Specialty Silica market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Specialty Silica Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Specialty Silica Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Specialty Silica Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Specialty Silica (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Specialty Silica Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Specialty Silica Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Specialty Silica Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Specialty Silica Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Specialty Silica Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Specialty Silica Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Specialty Silica Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Specialty Silica Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Specialty Silica Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
