
Market Overview
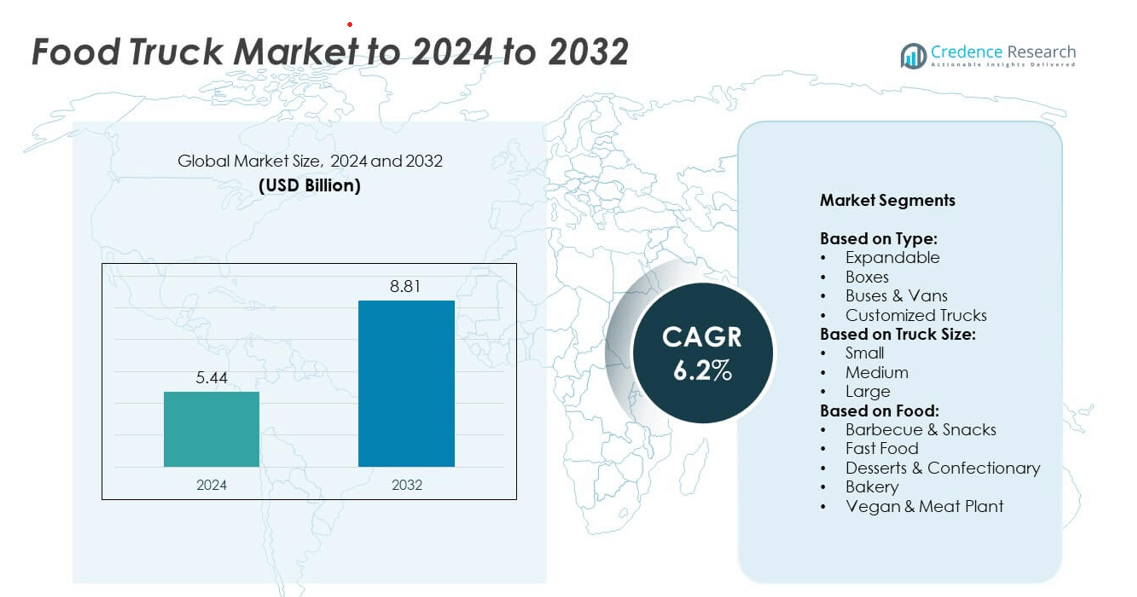
The global food truck market size was valued at USD 5.44 billion in 2024 and is anticipated to reach USD 8.81 billion by 2032, at a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Truck Market Size 2024 | USD 5.44 billion |
| Food Truck Market, CAGR | 6.2% |
| Food Truck Market Size 2032 | USD 8.81 billion |
The food truck market features prominent players such as Futuristo Trailers, Cousins Maine Lobster, Food Truck Company, Veicoli Speciali, MSM Catering Trucks MFG. Inc., Prestige Food Trucks, The Fud Trailer, Bostonian Body, Inc., United Food Truck, and M&R Specialty Trailers and Trucks. These companies strengthen the industry by offering customized, durable, and technologically advanced mobile kitchens tailored to diverse operator needs. North America led the global market in 2024 with a 38% share, supported by strong street food culture, high consumer spending, and widespread participation in food festivals. Europe followed with 27%, while Asia Pacific accounted for 22%, driven by rising urbanization and demand for affordable, on-the-go dining solutions
Market Insights
- The food truck market was valued at USD 5.44 billion in 2024 and is projected to reach USD 8.81 billion by 2032, growing at a CAGR of 6.2%.
- Growth is fueled by the rising popularity of street food culture, low startup costs, and increasing demand for mobile and convenient food services across urban areas.
- Key trends include the adoption of digital ordering systems, social media marketing, and menu diversification with health-conscious options such as vegan, gluten-free, and organic offerings.
- The market is highly competitive with global and regional players focusing on customizable trucks, energy-efficient designs, and strategic partnerships with entrepreneurs to strengthen their presence.
- North America led the market with 38% share in 2024, followed by Europe at 27% and Asia Pacific at 22%. By type, buses & vans dominated with over 40% share, while medium-sized trucks held the lead in truck size due to their balance of mobility and capacity.
Market Segmentation Analysis:
By Type
The buses & vans segment held the dominant share of the food truck market in 2024, accounting for over 40% of total revenue. Their popularity stems from flexibility, ease of mobility, and cost-efficient operations compared to expandable or customized trucks. Buses and vans offer suitable space for fast food and beverages, making them the preferred choice among new entrepreneurs and small businesses. Growing urban street food demand and low initial investment requirements continue to drive the adoption of vans and buses, particularly in North America and Asia-Pacific urban centers.
- For instance, SNS Insider reports that “Buses & Vans” held roughly 60–65 % share in the global food truck market by type.
By Truck Size
Medium-sized trucks accounted for the largest share, holding nearly 45% of the global food truck market in 2024. These vehicles strike a balance between mobility and kitchen space, allowing operators to serve diverse menus while accessing both high-traffic urban zones and event venues. Small trucks remain popular in densely populated cities but face space limitations, while large trucks offer higher capacity but are costlier. Rising food festivals and catering events are fueling demand for medium-sized food trucks, making them the most commercially viable option.
- For instance, In 2024, trucks of 14 to 22 ft length held a leading position in many markets.
By Food
Fast food dominated the market by food category in 2024, securing around 38% of total revenue share. The segment benefits from rising consumer demand for quick-service meals, including burgers, sandwiches, and fried snacks. Food trucks specializing in fast food are highly scalable and draw consistent demand across urban areas, college campuses, and event gatherings. While barbecue & snacks and bakery categories also show steady growth, fast food trucks continue to lead due to convenience, affordability, and the influence of international quick-service trends on local street food culture.
Key Growth Drivers
Rising Popularity of Street Food Culture
Street food culture is expanding rapidly worldwide, and food trucks play a vital role in this shift. Consumers, especially younger demographics, are drawn to affordable, diverse, and convenient dining experiences. The trend is reinforced by social media exposure, where food trucks gain visibility through digital marketing and influencer promotions. Events, festivals, and pop-up dining also contribute to increased demand. This cultural acceptance has turned food trucks into mainstream dining options, positioning the segment as a critical driver of growth in both developed and emerging markets.
- For instance, in a recent assessment of food truck marketing, 75% of operators were found to actively use Facebook to promote their business.
Low Startup and Operating Costs
Compared to traditional restaurants, food trucks offer significantly lower entry barriers for entrepreneurs. Investment in a food truck business requires less capital for infrastructure, staffing, and permits, making it attractive to small businesses. This affordability encourages startups and established restaurateurs alike to explore mobile food ventures. Lower operating expenses also allow for greater flexibility in menu innovation and pricing strategies. As governments in several regions promote small business development, favorable licensing and financial support further fuel this cost-driven expansion.
- For instance, in the 2024 food truck market, operations focused on events and festivals comprised 60.9% of the revenue in roaming and event-based services.
Growing Demand for Mobile and On-the-Go Food Services
Urban lifestyles are increasingly fast-paced, creating a strong appetite for convenient food options. Food trucks fulfill this demand by providing mobility and easy access in offices, colleges, public spaces, and events. Their ability to relocate and serve high-footfall areas boosts revenue potential compared to static restaurants. Rising participation in outdoor events, food fairs, and festivals adds to the expansion. With changing consumer preferences toward quick-service and portable food, mobile food solutions stand out as one of the key growth drivers in this industry.
Key Trends & Opportunities
Menu Innovation and Health-Conscious Offerings
Food trucks are capitalizing on the rising demand for healthier, sustainable, and plant-based meals. Vendors are expanding menus with vegan, gluten-free, and organic options to cater to evolving consumer preferences. This shift not only broadens customer reach but also aligns with global wellness and sustainability trends. Innovative fusion cuisines and seasonal menus further differentiate operators in a competitive market. Offering unique dining experiences through diverse and health-focused menus presents a strong opportunity for food truck operators to attract a wider, health-aware consumer base.
- For instance, in 2025, reports on food truck technology adoption found that 61% of food trucks were using digital menus to enhance clarity and ordering, while 66% had adopted mobile ordering systems to improve customer experience and reduce wait times.
Technology Integration and Digital Ordering
Adoption of digital solutions is transforming the food truck market. Mobile apps, QR-based ordering, and digital payment systems streamline customer service and improve convenience. Integration with food delivery platforms expands reach beyond physical locations, enabling trucks to serve remote customers. Social media engagement also boosts brand visibility and customer loyalty. Technology-driven operations allow for better inventory management, customer feedback analysis, and targeted marketing. This technological shift offers food truck businesses an opportunity to enhance efficiency and align with the growing demand for digital-first consumer experiences.
- For instance, the Guinness World Record for the largest parade of food trucks was 121 trucks, which was achieved in Tampa in 2014. However, the current record for the largest rally of food trucks is 158 trucks, achieved in Malaysia in 2018.
Key Challenges
Regulatory and Licensing Barriers
Food trucks face strict regulations related to health, safety, and location permits, which vary widely across regions. Obtaining licenses, parking permissions, and health clearances often requires time and resources, limiting operational flexibility. Inconsistent or restrictive local policies can hinder expansion, especially for smaller entrepreneurs. Compliance costs may also offset the affordability advantage of food trucks. These regulatory complexities create significant barriers to market entry and sustained operations, making legal compliance a major challenge for growth in the food truck market.
High Competition and Market Saturation
The food truck industry is highly competitive, with new entrants frequently emerging due to low startup costs. Intense rivalry often results in price wars, reduced margins, and difficulty in maintaining customer loyalty. Established restaurant chains entering the mobile dining space add further pressure. Additionally, consumer preferences for novelty create challenges for sustaining consistent demand. Operators must continuously innovate menus and marketing strategies to stay competitive. Market saturation in key urban centers intensifies the struggle for prime operating locations, posing a long-term growth challenge.
Regional Analysis
North America
North America held the largest share of the food truck market in 2024, accounting for 38% of global revenue. The region’s strong dominance is supported by a well-established street food culture, a large base of urban consumers, and extensive participation in food festivals and public events. Rising demand for fast food and gourmet offerings through mobile outlets also strengthens market expansion. Supportive regulations in several states and the presence of established operators enhance competitiveness. The United States leads the region, while Canada is experiencing steady growth with growing adoption of food trucks in metropolitan cities.
Europe
Europe accounted for 27% of the global food truck market in 2024, supported by urban demand for diverse street food experiences. Countries such as the United Kingdom, Germany, and France are key contributors, driven by consumer interest in fusion cuisine and mobile dining concepts. Food truck businesses benefit from tourism and cultural events, providing steady growth opportunities. However, the region faces stricter regulations compared to North America, which can limit expansion in certain cities. Despite this, Europe’s evolving consumer food habits and increasing popularity of health-conscious offerings continue to create significant growth potential for the market.
Asia Pacific
Asia Pacific captured 22% of the global food truck market in 2024, driven by rising urbanization and expanding middle-class consumer spending. Street food has a long cultural presence in countries such as India, China, and Thailand, and modern food trucks are adapting to changing preferences by offering innovative and hygienic solutions. Rapid growth in urban centers and increasing youth demand for convenient, affordable dining options fuel the market. Government initiatives supporting small businesses also encourage new entrants. With its large population base and expanding food service sector, Asia Pacific represents one of the fastest-growing regions in this industry.
Latin America
Latin America represented 8% of the food truck market in 2024, with growth led by Brazil, Mexico, and Argentina. The region benefits from a strong street food tradition combined with growing urban demand for mobile food services. Food trucks in Latin America are increasingly offering diverse menus ranging from traditional snacks to international cuisines. The affordability of starting food truck businesses makes them appealing for entrepreneurs, particularly in major cities. However, regulatory inconsistencies and infrastructure limitations pose challenges. Despite this, the region’s rising tourism sector and increasing adoption of food festivals continue to create opportunities for steady expansion.
Middle East & Africa
The Middle East & Africa held a 5% share of the global food truck market in 2024, emerging as a niche but growing segment. Rising urbanization, tourism expansion, and increasing demand for international cuisines support adoption in countries such as the United Arab Emirates and South Africa. The region benefits from strong investments in hospitality and food service sectors, particularly in urban hubs and tourist destinations. However, limited consumer awareness and high regulatory barriers in some areas slow market penetration. Despite these challenges, the growing trend of outdoor dining and cultural festivals is fostering gradual regional market growth.
Market Segmentations:
By Type:
- Expandable
- Boxes
- Buses & Vans
- Customized Trucks
By Truck Size:
- Small
- Medium
- Large
By Food:
- Barbecue & Snacks
- Fast Food
- Desserts & Confectionary
- Bakery
- Vegan & Meat Plant
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The food truck market is characterized by the presence of leading manufacturers and franchise operators such as Futuristo Trailers, Cousins Maine Lobster, Food Truck Company, Veicoli Speciali, MSM Catering Trucks MFG. Inc., Prestige Food Trucks, The Fud Trailer, Bostonian Body, Inc., United Food Truck, and M&R Specialty Trailers and Trucks. These players compete by offering a wide variety of truck designs, customizable features, and innovative kitchen layouts to meet the needs of different food service operators. Strong emphasis is placed on durability, mobility, and compliance with regional safety and hygiene standards. Many companies are also investing in advanced technologies, including energy-efficient power systems and integrated digital solutions, to enhance operational efficiency. Competitive strategies often focus on partnerships with small businesses and entrepreneurs, enabling affordable entry into the market. Additionally, increasing demand for specialized trucks, such as those catering to health-conscious or gourmet offerings, is driving innovation across the competitive landscape.
Key Player Analysis
- Futuristo trailers
- Cousins Maine Lobster (Franchise Operator)
- Food Truck Company
- Veicoli Speciali
- MSM CATERING TRUCKS MFG. INC.
- Prestige Food Trucks
- The Fud Trailer
- Bostonian Body, Inc.
- United Food Truck
- M&R SPECIALTY TRAILERS AND TRUCKS
Recent Developments
- In 2025, Cousins Maine Lobster (Franchise Operator) Launched a second franchise food truck in the Upstate New York area, following the successful debut of its first truck there nine months prior.
- In 2024, Prestige Food Trucks Grew its operations by completing nearly 50 custom food truck builds, delivering to over 20 U.S. states and overseas.
- In 2024, United Food Trucks unveiled a custom-designed food truck for UTEC, a non-profit organization
Report Coverage
The research report offers an in-depth analysis based on Type, Truck Size, Food and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The food truck market will continue to expand with rising urban street food demand.
- Medium-sized trucks will remain the preferred choice due to balance of space and mobility.
- Fast food trucks will dominate, supported by growing quick-service culture across cities.
- Health-focused menus such as vegan and organic options will gain more popularity.
- Digital payments and app-based ordering will drive operational efficiency and customer engagement.
- Food festivals and outdoor events will provide consistent revenue opportunities for operators.
- North America will maintain leadership, while Asia Pacific will see the fastest growth.
- Competition will intensify, pushing operators to innovate menus and marketing approaches.
- Regulatory simplification in emerging markets will encourage new entrants and small businesses.
- Partnerships with delivery platforms will expand reach beyond traditional food truck locations.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Popularity of Street Food Culture
The global embrace of street food culture, especially among younger consumers, is fueling demand for food trucks by offering affordable, diverse, and convenient dining experiences. Social media exposure and participation in food festivals further amplify this trend, making food trucks a mainstream dining option.
Low Startup and Operating Costs
Food trucks require significantly less capital investment and have lower operating expenses compared to traditional restaurants, making them attractive to entrepreneurs and small businesses. This affordability encourages new market entrants and supports rapid expansion, especially in urban areas.
Growing Demand for Mobile and On-the-Go Food Services
Urbanization and fast-paced lifestyles are increasing the need for convenient, mobile food options. Food trucks can relocate to high-traffic areas and events, providing flexible access to consumers and capitalizing on outdoor gatherings, festivals, and office locations.
Menu Innovation and Health-Conscious Offerings
Operators are expanding menus to include vegan, gluten-free, and organic options, responding to evolving consumer preferences for healthier and more sustainable food. This innovation attracts a broader customer base and aligns with global wellness trends.
Technology Integration and Digital Ordering
The adoption of digital ordering systems, mobile payments, and social media marketing is enhancing customer experience and operational efficiency for food trucks. These technologies help operators reach more customers, streamline service, and build brand loyalty in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Food Truck Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Truck Market projected to grow between 2025 and 2032?
Which Food Truck Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Truck Market?
Who are the leading companies in the Food Truck Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Food
- 1.2.1 Barbecue & Snacks
- 1.2.2 Fast Food
- 1.2.3 Desserts & Confectionary
- 1.2.4 Bakery
- 1.2.5 Vegan & Meat Plant
- 1.3 By Type
- 1.3.1 Expandable
- 1.3.2 Boxes
- 1.3.3 Buses & Vans
- 1.3.4 Customized Trucks
- 1.4 By Truck Size
- 1.4.1 Small
- 1.4.2 Medium
- 1.4.3 Large
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.44 billion → 2032: USD 8.81 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Truck Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Truck Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Truck Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Truck Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Truck Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Truck Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Truck Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Truck Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.44 billion → 2032: USD 8.81 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Truck Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Food - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Barbecue & Snacks
- 12.3.7.2 Fast Food
- 12.3.7.3 Desserts & Confectionary
- 12.3.7.4 Bakery
- 12.3.7.5 Vegan & Meat Plant
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Expandable
- 12.4.7.2 Boxes
- 12.4.7.3 Buses & Vans
- 12.4.7.4 Customized Trucks
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Truck Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Small
- 12.5.7.2 Medium
- 12.5.7.3 Large
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Truck Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Food Truck Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Food Truck Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Futuristo Trailers
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Cousins Maine Lobster
- 17.4 Food Truck Company
- 17.5 Veicoli Speciali
- 17.6 MSM Catering Trucks MFG. Inc.
- 17.7 Prestige Food Trucks
- 17.8 The Fud Trailer
- 17.9 Bostonian Body, Inc.
- 17.10 United Food Truck
- 17.11 M&R Specialty Trailers and Trucks
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

