
Market Overview:
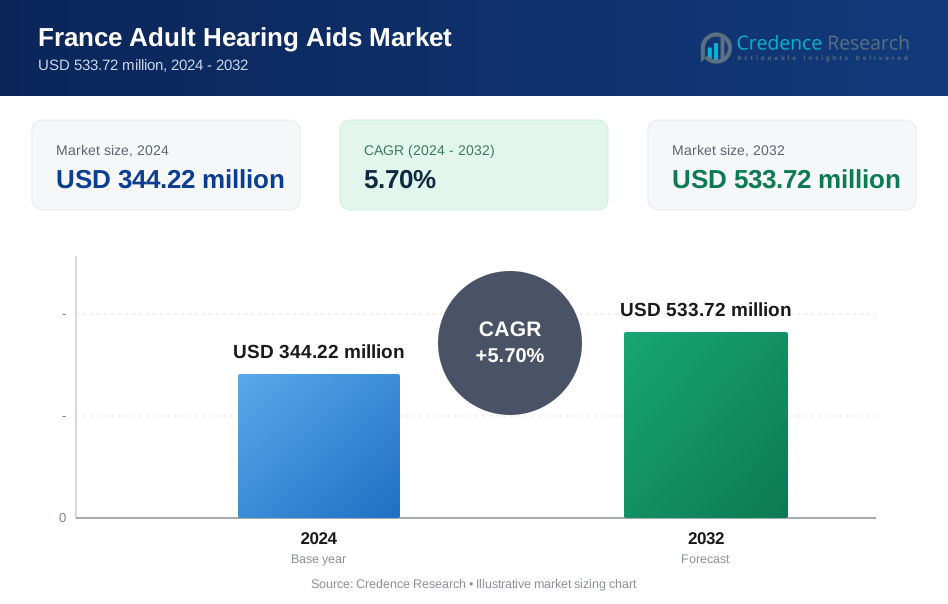
The France Adult Hearing Aids Market size was valued at USD 277.77 million in 2018 to USD 344.22 million in 2024 and is anticipated to reach USD 533.72 million by 2032, at a CAGR of 5.70% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Adult Hearing Aids Market Size 2024 | USD 344.22 Million |
| France Adult Hearing Aids Market, CAGR | 5.70% |
| France Adult Hearing Aids Market Size 2032 | USD 533.72 Million |
The market growth is being driven by the rising prevalence of hearing loss among the aging population, coupled with increased awareness about the benefits of early diagnosis and treatment. Technological advancements in hearing aid devices, such as the integration of Bluetooth connectivity, rechargeable batteries, and AI-driven sound processing, are enhancing user adoption. Government support through healthcare reimbursement programs and improving accessibility of hearing aids in both urban and rural areas further stimulate demand. Additionally, social acceptance of hearing aids is improving, leading to higher adoption rates.
Regionally, Western Europe, including France, remains a leading market due to advanced healthcare systems, strong government support, and widespread availability of technologically advanced hearing aids. Northern European countries also demonstrate steady demand, while Southern and Eastern Europe are emerging as promising markets driven by growing awareness and improving healthcare infrastructure. France stands as a key hub, benefiting from innovation, strong distribution networks, and a growing elderly population seeking quality hearing solutions.
Market Insights:
- The France Adult Hearing Aids Market was valued at USD 277.77 million in 2018, reached USD 344.22 million in 2024, and is projected to hit USD 533.72 million by 2032, growing at a CAGR of 5.70%.
- Northern France led with 34% share in 2024, supported by advanced healthcare infrastructure and urban populations; Southern France followed with 29%, driven by strong urban demand; Western and Eastern regions together accounted for 37%, benefiting from demographic diversity and cross-border healthcare influence.
- The fastest-growing subregion is Southern France, holding 29% share, driven by expanding distribution networks, rising awareness in urban hubs, and insurance-backed accessibility.
- Age-related hearing loss dominates type segmentation, representing the largest share, supported by rising elderly populations seeking consistent hearing support.
- Behind-the-Ear (BTE) hearing aids lead application segmentation, holding the largest share due to durability, ease of use, and suitability for severe impairments.

Market Drivers
Rising Geriatric Population Driving Demand for Hearing Aid Devices in France
The growing elderly population forms a critical demand base for hearing solutions. France is witnessing an increase in the proportion of people over 60 years, leading to higher incidences of hearing loss. This demographic group actively seeks advanced devices to improve quality of life. Hearing aids are no longer viewed only as medical necessities but as tools for maintaining independence and communication. The France Adult Hearing Aids Market is gaining traction as awareness grows around untreated hearing loss. Social programs encourage early diagnosis, creating more users in this age group. It benefits from public healthcare policies that focus on aging populations. This demand driver remains central to market growth.
Technological Integration Enhancing Adoption of Modern Hearing Aid Solutions
Hearing aid devices are now designed with smart features that attract users. France is witnessing higher demand for products with Bluetooth, AI-powered noise management, and rechargeable options. Consumers prefer seamless connectivity with smartphones and televisions. The France Adult Hearing Aids Market benefits from continuous product innovation. Manufacturers are investing in R&D to reduce device size while improving functionality. It creates strong consumer trust and higher satisfaction rates. Retailers highlight technology upgrades to attract younger adults with hearing needs. This integration is a major force supporting long-term adoption.
- For instance, Widex Allure hearing aids, driven by the new W1 chip, incorporate a 52-band spectral analysis system within its Speech Enhancer Pro feature, along with AI-based classification via the Allure App. Early studies show an impressive 92% user preference in noisy environments and a 4.3 dB improvement in speech intelligibility in noise over the previous Widex Moment platform, showcasing its advanced noise management technology.
Supportive Healthcare Reimbursement Policies Encouraging Higher Market Penetration
Healthcare coverage in France creates an encouraging environment for hearing aid adoption. Public health systems reimburse part of the costs, reducing barriers for patients. Private insurance schemes further expand accessibility. The France Adult Hearing Aids Market benefits from strong regulatory backing. It creates stability for manufacturers and distributors serving different income groups. Improved reimbursement models allow patients to select advanced devices without significant financial strain. Government focus on equitable healthcare strengthens adoption. This driver significantly improves affordability for adults needing hearing aids.
Rising Social Acceptance of Hearing Aid Devices in Everyday Life
Hearing aids are becoming more socially accepted in France, reducing stigma linked to their use. Advertising campaigns highlight design improvements and lifestyle benefits. Consumers are increasingly confident in choosing visible devices with modern styles. The France Adult Hearing Aids Market benefits from this cultural change. It reflects a society where technology and health merge seamlessly. Younger adults with hearing impairments also demonstrate openness to adoption. Wider acceptance encourages repeat purchases and upgrades. This driver fosters growth beyond traditional age segments.
- For instance, GN Hearing’s 2024 “The New Norm” campaign aims to challenge misperceptions and increase the social acceptance of hearing aids. The campaign, launched on World Hearing Day 2024, uses diverse, normalizing imagery of hearing aid users, which is available in a free Unsplash image bank
Market Trends
Adoption of Tele-Audiology Services Reshaping Patient Care in Hearing Solutions
Remote consultations are transforming the way patients access audiology services. Clinics in France now provide tele-audiology platforms for diagnosis and follow-ups. Patients can adjust device settings through connected applications. The France Adult Hearing Aids Market is experiencing growth due to this digital integration. It reduces travel barriers for rural populations and improves convenience for urban users. Manufacturers integrate apps that support real-time monitoring. Audiologists also benefit from continuous engagement with patients. This trend reflects the modernization of healthcare delivery.
- For instance, Oticon's RemoteCare feature, integrated within its Companion app, enables real-time remote adjustments and tele-audiology consultations. This functionality has improved access and patient engagement through digital platforms, which is a growing trend in the audiology sector.
Miniaturization of Devices Driving Consumer Preference for Discreet Solutions
Device miniaturization is influencing consumer purchase decisions in France. Smaller, lightweight designs make products more comfortable for daily use. Patients value discreet devices that blend with personal lifestyles. The France Adult Hearing Aids Market benefits from innovations in micro-components. It drives acceptance among younger adults who prefer aesthetic appeal. Manufacturers invest in nanotechnology to deliver advanced sound processing within compact designs. This trend is expected to shape competitive differentiation. Consumers increasingly demand performance without visible bulkiness.
- For instance, Phonak's Marvel 2.0 hearing aids incorporated advanced micro-electronics that enabled universal Bluetooth connectivity and binaural streaming. The update in 2019 made RogerDirect technology available in all Marvel aids, eliminating the need for an external receiver and making the device up to 42% smaller for those who use the Roger technology. The platform maintained high-fidelity sound processing with its AutoSense OS 3.0.
Growing Use of Eco-Friendly and Sustainable Materials in Hearing Aid Production
Sustainability trends are influencing manufacturing practices across Europe. Companies in France are adopting recyclable materials in hearing aid production. Consumers show preference for devices aligned with eco-conscious values. The France Adult Hearing Aids Market is responding to sustainability demands. It creates opportunities for manufacturers to align with green policies. Governments encourage industries to adopt circular economy models. Retailers highlight eco-labels as a differentiating factor. This trend strengthens brand reputation and long-term consumer loyalty.
Integration of Artificial Intelligence in Personalized Hearing Experiences
Artificial intelligence is reshaping user experiences in the hearing aid sector. Devices now provide adaptive sound management for complex environments. AI algorithms analyze background noise and improve speech clarity. The France Adult Hearing Aids Market is advancing through this trend. It delivers customized solutions that adapt to lifestyle changes. Patients benefit from superior auditory comfort and reduced listening fatigue. Audiologists use data-driven insights for improved fitting. This trend positions AI as a cornerstone of next-generation hearing aids.
Market Challenges Analysis
High Cost of Advanced Hearing Aids Limiting Access Across Consumer Groups
Premium devices with advanced technology remain expensive for many users in France. The France Adult Hearing Aids Market faces adoption barriers due to these costs. It impacts low-income adults who often delay or avoid purchase. Public reimbursement helps but does not cover all premium features. High prices discourage upgrades to newer models. Many consumers opt for basic versions, limiting innovation penetration. Manufacturers struggle to balance affordability with profitability. This challenge creates a divide in access across different socioeconomic groups.
Limited Awareness in Rural Regions Restricting Market Expansion Opportunities
Awareness gaps hinder adoption in rural and semi-urban areas of France. Many adults remain unaware of available solutions or avoid consultations. The France Adult Hearing Aids Market faces growth hurdles in underserved areas. It struggles due to limited audiology clinics outside major cities. It affects diagnosis rates and delays treatment. Cultural barriers in smaller towns reinforce stigma about hearing aids. Distributors often face logistical difficulties in reaching remote populations. This challenge slows nationwide market penetration.
Market Opportunities
Expanding Digital Platforms Creating Broader Market Reach for Audiology Services
Digital healthcare platforms offer new pathways to reach wider populations. France is adopting e-health services at a rapid pace. The France Adult Hearing Aids Market can benefit from this expansion. It enables clinics to offer virtual diagnosis, device adjustments, and follow-ups. Patients gain access to continuous support without geographic barriers. This opportunity can reshape service models for hearing solutions. Manufacturers also benefit from data integration through digital platforms. It creates long-term engagement and brand loyalty.
Rising Demand for Customized Devices Supporting Growth Across Diverse Demographics
Consumers in France are showing strong demand for tailored hearing aids. The France Adult Hearing Aids Market benefits from increasing focus on personalization. It includes customized fittings, design preferences, and sound adjustments. Younger adults seek lifestyle-compatible products, while seniors value comfort and clarity. Manufacturers can capture share by offering diverse models. This opportunity fosters brand differentiation in a competitive environment. Expanding customization aligns with consumer behavior shifts. It supports both adoption and repeat purchases.
Market Segmentation Analysis:
The France Adult Hearing Aids Market is segmented
By type into congenital hearing loss, age-related hearing loss, and acquired trauma hearing loss. Age-related hearing loss forms the dominant segment due to the country’s growing elderly population requiring consistent auditory support. Congenital hearing loss remains a smaller share but receives attention through early intervention programs. Acquired trauma hearing loss contributes steadily, supported by rising awareness of occupational and environmental risks. It reflects a demand base that spans across diverse age groups and medical needs.
- For instance, France’s Universal Newborn Hearing Screening (UNHS) program, introduced in the Champagne-Ardenne region in January 2004, enabled early diagnosis of congenital hearing loss in infants. A study following the program found an average diagnosis age of 3.2 months, significantly improving outcomes for diagnosed newborns through tailored auditory interventions
By application, the market is categorized into behind-the-ear (BTE), in-the-ear (ITE), in-the-canal (ITC), and completely-in-canal (CIC) hearing aids. BTE devices hold the largest share due to ease of use, durability, and suitability for severe impairments. ITE and ITC models appeal to consumers seeking comfort and moderate discretion. CIC devices represent a premium category, favored by younger adults valuing aesthetics and invisible design. It shows how technology and lifestyle preferences influence adoption across segments.
- For instance, WS Audiology’s Signia promotes its Styletto X in France as a slim, rechargeable Receiver-in-Canal hearing aid, combining modern design with advanced features to appeal to younger, style-conscious adults seeking discreet solutions.
By sales channel, the market is divided into direct channel and distribution channel. The distribution channel dominates, supported by retail networks, audiology clinics, and partnerships with healthcare providers. Direct channels, including online sales and company-owned outlets, are expanding rapidly with the rise of digital healthcare and e-commerce adoption. It highlights a shift toward convenience and personalized buying experiences. Both channels create competitive advantages, shaping how companies expand market reach.
Segmentation:
By Type
- Congenital Hearing Loss
- Age-Related Hearing Loss
- Acquired Trauma Hearing Loss
By Application
- Behind-the-Ear (BTE) Hearing Aids
- In-the-Ear (ITE) Hearing Aids
- In-The-Canal (ITC) Hearing Aids
- Completely-In-Canal (CIC) Hearing Aids
By Sales Channel
- Direct Channel
- Distribution Channel
Regional Analysis:
Northern France accounts for 34% share of the France Adult Hearing Aids Market, supported by strong healthcare infrastructure and a higher concentration of urban populations. Major cities such as Paris and Lille host specialized audiology clinics and advanced medical centers, driving higher adoption rates. The presence of leading distribution networks ensures easy availability of devices. It benefits from government-backed awareness campaigns targeting early diagnosis of hearing conditions. The concentration of elderly citizens in metropolitan hubs further strengthens demand. This subregion maintains leadership due to access, affordability, and patient-centered healthcare systems.
Southern France represents 29% of the market, driven by a mix of urban and rural populations. The subregion faces challenges in rural penetration but gains momentum through expanding retail distribution. Cities like Marseille and Nice play a pivotal role in supporting device adoption with well-established healthcare facilities. It records steady growth from increasing lifestyle-related hearing issues and expanding insurance coverage. The tourism-driven economy also fosters awareness campaigns targeting occupational hearing health. This balance between healthcare accessibility and lifestyle adoption positions the subregion as a strong contributor.
Western and Eastern France collectively capture 37% share of the market, reflecting a diverse demand pattern across mixed demographics. Western regions such as Brittany demonstrate solid growth in elderly populations needing long-term care. Eastern regions, including Alsace and Lorraine, benefit from cross-border healthcare influence due to proximity to Germany and Switzerland. It records higher acceptance of premium devices among middle- and high-income groups. The mix of industrial hubs and semi-urban populations drives steady adoption across application types. This subregional diversity creates opportunities for targeted product strategies and distribution expansion.
Key Player Analysis:
- GN Hearing
- Sonova
- GrandAudition
- WS Audiology
- GN ReSound
- Rion
- Sebotek Hearing Systems
- Audina Hearing Instruments
- Microson
- Amplifon France
- Phonak
- Others
Competitive Analysis:
The France Adult Hearing Aids Market features a competitive landscape shaped by global leaders and regional specialists. Key players such as GN Hearing, Sonova, WS Audiology, and Phonak dominate with strong product portfolios and advanced technology integration. Amplifon France secures a significant share through its widespread retail presence and personalized service models. Smaller players like Microson and Audina Hearing Instruments target niche segments with cost-effective solutions. It benefits from continuous innovation where companies focus on AI integration, rechargeable models, and wireless connectivity to capture diverse consumer needs. Competition is also influenced by mergers, acquisitions, and strategic alliances that expand market reach and enhance technological capabilities. Distribution networks remain a crucial factor, with companies leveraging both physical clinics and digital platforms to expand consumer access. Global manufacturers rely on economies of scale, while local firms emphasize customization and affordability. The France Adult Hearing Aids Market encourages players to balance innovation with accessibility, ensuring products appeal across different income levels.
Recent Developments:
- In August 2025, William Demant Invest entered a three-year research collaboration with Lineage Cell Therapeutics to develop ReSonance (ANP1), an auditory neuronal cell transplant targeting hearing loss. William Demant will fund up to $12 million for preclinical development in this pioneering initiative.
- In June 2025, Starkey announced a partnership with MED-EL, introducing DualSync, a bimodal streaming technology that allows seamless audio from Apple devices to both Starkey hearing aids (Edge AI and Genesis AI) and MED-EL cochlear implants, launching July 1, 2025. This collaboration aims to unify wireless connectivity for users requiring both technologies.
- In August 2024, Sonova Holding AG launched the Phonak Audéo Infinio Sphere, a new receiver-in-canal (RIC) hearing aid featuring advanced Bluetooth connectivity, IP68+ water resistance, and next-generation fitness tracking capabilities, further establishing their innovation leadership in the adult hearing aids market.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The France Adult Hearing Aids Market will see strong growth supported by an aging population with higher hearing care needs.
- Rising adoption of AI-enabled and Bluetooth-connected hearing aids will transform user experiences.
- Growing acceptance of discreet and cosmetic designs will attract younger demographics seeking comfort and style.
- Tele-audiology and digital health platforms will expand access to underserved regions across the country.
- Insurance coverage and public healthcare reimbursement will continue to improve affordability of advanced devices.
- Demand for eco-friendly and sustainable hearing aids will shape product innovation and brand positioning.
- Competitive dynamics will intensify as global leaders expand presence alongside regional firms offering cost-effective options.
- Distribution channels will diversify, with e-commerce and direct sales gaining prominence alongside clinical networks.
- Increasing awareness campaigns will reduce stigma and support early adoption across rural and urban populations.
- Strategic collaborations and technological investments will sustain long-term growth and strengthen consumer trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for France Adult Hearing Aids Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Adult Hearing Aids Market projected to grow between 2024 and 2032?
Which France Adult Hearing Aids Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Adult Hearing Aids Market?
Who are the leading companies in the France Adult Hearing Aids Market?
Which region commanded the largest share of the France Adult Hearing Aids Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Adult Hearing Aids Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Adult Hearing Aids Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 344.22 million → 2032: USD 533.72 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Adult Hearing Aids Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Adult Hearing Aids Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Adult Hearing Aids Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Adult Hearing Aids Market Drivers
- 3.3 France Adult Hearing Aids Market Restraints & Challenges
- 3.4 France Adult Hearing Aids Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Adult Hearing Aids Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Adult Hearing Aids Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Adult Hearing Aids category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Adult Hearing Aids Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Adult Hearing Aids Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Adult Hearing Aids market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Adult Hearing Aids Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Adult Hearing Aids Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Adult Hearing Aids Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Adult Hearing Aids (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Adult Hearing Aids Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Adult Hearing Aids Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Adult Hearing Aids Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Adult Hearing Aids Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Adult Hearing Aids Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Adult Hearing Aids Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Adult Hearing Aids Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Adult Hearing Aids Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Adult Hearing Aids Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
