
Market Overview
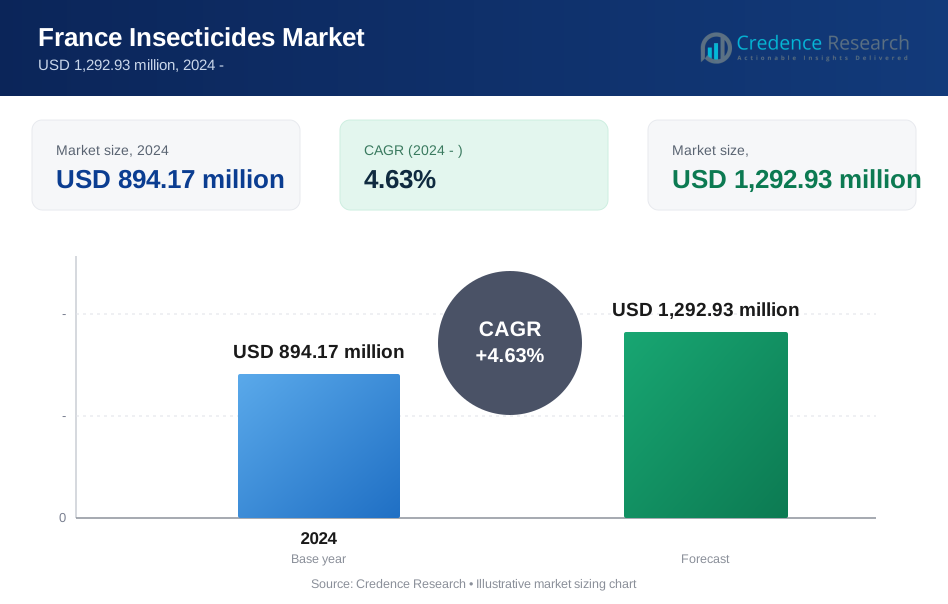
France Insecticides Market size was valued at USD 670.45 million in 2018 to USD 894.17 million in 2024 and is anticipated to reach USD 1,292.93 million by 2032, at a CAGR of 4.63% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Insecticides Market Size 2024 | USD 894.17 Million |
| France Insecticides Market, CAGR | 4.63% |
| France Insecticides Market Size 2032 | USD 1,292.93 Million |
The France Insecticides Market is shaped by global leaders and regional specialists competing through innovation, product diversity, and distribution strength. Key players include Bayer AG, BASF SE, Syngenta, FMC Corporation, ADAMA Agricultural Solutions, Nufarm Limited, UPL Limited, Sipcam France, Cheminova (FMC), and Bioline AgroSciences, all of which focus on developing compliant, eco-friendly, and effective formulations. These companies leverage strong R&D, partnerships, and integrated pest management solutions to maintain competitiveness in a regulatory-driven environment. Among regions, Northern France leads with 28% market share, supported by extensive cereal and sugar beet farming alongside vineyards, making it the most significant contributor to national demand.
Market Insights
- The France Insecticides Market grew from USD 670.45 million in 2018 to USD 894.17 million in 2024 and is forecasted to reach USD 1,292.93 million by 2032.
- Organophosphates lead with 34% share due to extensive use in cereals and vineyards, while pyrethroids at 22% gain demand for cost-effectiveness and wide pest control.
- Agriculture dominates applications with 63% share, driven by cereals, fruits, and vegetables, followed by public health at 13% as vector-borne disease control demand rises.
- Northern France holds the largest regional share at 28%, supported by cereals, sugar beet, and vineyards, while Western France follows with 24% from wine-focused horticulture.
- Key players such as Bayer AG, BASF SE, Syngenta, FMC Corporation, ADAMA, UPL, and Sipcam France emphasize eco-friendly formulations and integrated pest management solutions.
Market Segment Insights
By Product Type
Organophosphates account for the dominant share of around 34% in the France insecticides market. Their strong position stems from widespread use in large-scale agriculture, particularly cereal and vineyard production. Carbamates hold nearly 18%, supported by effectiveness in horticultural crops and orchard protection. Pyrethroids represent about 22%, gaining demand due to cost-effectiveness and strong control over household and crop pests. Neonicotinoids contribute close to 12%, although growth is constrained by regulatory restrictions within the EU. Biological insecticides capture around 9%, driven by eco-friendly solutions and rising organic farming adoption. The remaining 5% share belongs to other insecticides, used mainly in niche applications and integrated pest management programs.
- For instance, Bayer CropScience expanded its portfolio in France by releasing Movento® insecticide, used predominantly in horticulture for protecting fruits and vegetables from harmful sap-feeding insects, aligning with integrated pest management programs.
By Application
Agriculture dominates the France insecticides market with approximately 63% share, supported by intensive farming of cereals, fruits, and vegetables. Forestry applications represent nearly 11%, primarily for protecting pine and hardwood species from pests. Turf and landscape maintenance contributes about 8%, reflecting use in parks, golf courses, and municipal green spaces. Public health applications account for 13%, as demand for mosquito and vector control increases with climate-driven disease risks. Other uses cover around 5%, including household and industrial settings, where insect control ensures hygiene and safety standards.
- For instance, BASF launched Exponus® insecticide, based on broflanilide, for use on various crops including maize and potatoes, to protect against resistant pests

Key Growth Drivers
Rising Agricultural Productivity Needs
The France insecticides market is driven by the country’s intensive agricultural sector, particularly cereals, vineyards, and vegetable production. Farmers increasingly rely on effective pest control solutions to secure higher yields and protect crop quality. Growing demand for food security and export competitiveness amplifies the importance of insecticides in large-scale farming. This demand ensures continued adoption of both chemical and biological products, reinforcing organophosphates and pyrethroids as dominant sub-segments. The focus on sustaining agricultural output amid rising pest resistance fuels steady growth in the market.
- For instance, BASF introduced the fungicide Sercadis® Plus in India to help vineyard and apple farmers combat fungal diseases, particularly powdery mildew. It is a combination fungicide, not a fungicide-insecticide, designed to provide broad-spectrum disease control and improve resistance management.
Expansion of Integrated Pest Management (IPM)
The adoption of integrated pest management practices is strengthening insecticide demand in France. Farmers are combining traditional chemical insecticides with biological products, crop rotation, and monitoring technologies. This balanced approach reduces pest resistance and aligns with stringent EU environmental regulations. Biological insecticides are gaining traction as a result, with support from government incentives promoting eco-friendly solutions. IPM strategies not only improve sustainability but also extend the lifecycle of existing chemical solutions. This shift enhances long-term market stability while opening opportunities for innovative product portfolios.
- For instance, BASF launched its Smart IPM system integrating chemical and biological controls alongside digital monitoring tools, helping reduce pesticide resistance while ensuring compliance with EU regulations.
Regulatory Push Toward Safer Formulations
Regulatory frameworks in France and the wider EU are pushing insecticide manufacturers toward safer, compliant formulations. Strict controls on neonicotinoids and certain organophosphates encourage the development of alternatives that balance effectiveness and environmental safety. Companies are investing in research for low-residue, targeted, and biodegradable solutions to meet compliance. These shifts create growth for biological and next-generation synthetic products. The regulatory environment is fostering innovation and helping domestic and global firms expand their presence with advanced formulations that meet evolving market standards.
Key Trends & Opportunities
Rising Demand for Biological Insecticides
Biological insecticides are emerging as one of the fastest-growing segments in France. Farmers engaged in organic farming and sustainable agriculture increasingly prefer microbial and natural-based solutions. EU Green Deal objectives and consumer preference for residue-free produce support this growth. Although biologicals currently hold a modest share, their CAGR outpaces conventional products. This trend creates strong opportunities for local innovators and global firms to expand portfolios with eco-certified products and establish partnerships in the organic farming sector.
- For instance, Koppert expanded the use of its entomopathogenic nematode product Capsanem® in French berry production, offering growers an alternative to chemical soil treatments.
Digitalization and Precision Agriculture
The rise of digital farming and precision agriculture is reshaping insecticide use in France. Smart sensors, drones, and AI-driven platforms allow farmers to monitor pest outbreaks in real time and apply insecticides more efficiently. This reduces overuse, improves sustainability, and lowers operational costs. Technology integration also supports compliance with EU regulations by minimizing chemical input. Companies providing insecticides with digital integration solutions will capture a competitive advantage, making precision agriculture a significant opportunity for future growth in the French market.
- For instance, Syngenta partnered with xFarm Technologies to roll out AI-powered crop detection tools in France, supporting compliance with regulations for applying plant protection products near non-target crops.
Key Challenges
Stringent EU Regulatory Environment
The France insecticides market faces pressure from strict EU rules limiting the use of several chemical classes. Bans on neonicotinoids and tighter restrictions on organophosphates significantly affect product portfolios. Compliance costs for reformulation are high, especially for smaller regional players. These rules not only limit product diversity but also create uncertainty in long-term planning. Market participants must adapt quickly with innovative, eco-friendly solutions while maintaining effectiveness, which presents a major challenge for sustained competitiveness.
Growing Pest Resistance
Increasing pest resistance to conventional insecticides poses a critical challenge for French agriculture. Overuse of organophosphates and pyrethroids has reduced their efficacy against common pests in cereals, vineyards, and horticulture. Resistance forces farmers to rotate products or combine insecticides with biologicals, raising costs. Companies must invest in research to develop novel molecules and integrated solutions. Without innovation, resistance risks undermining the reliability of key chemical products, potentially reducing crop protection effectiveness and market growth potential.
Rising Costs of Innovation and Compliance
Developing new insecticides that meet both efficacy and regulatory demands involves significant costs. Long development cycles, extensive safety testing, and approval processes increase financial pressure on manufacturers. Global leaders can absorb these costs, but smaller regional companies face barriers to entry. These high investments slow product launches and limit diversity in the market. As regulatory hurdles rise, cost challenges are expected to intensify, creating financial strain and limiting innovation speed in the France insecticides market.

Regional Analysis
Northern France
Northern France holds 28% of the France Insecticides Market, led by its strong cereal and sugar beet farming base. The region’s large-scale agriculture drives significant use of organophosphates and pyrethroids for pest management. Vineyards in this zone also require targeted solutions to safeguard grape production. Farmers face increasing regulatory pressure, which encourages gradual adoption of biological alternatives. The demand is further shaped by mechanized farming practices that emphasize efficiency and yield protection. Northern France continues to represent a strategic hub for both domestic suppliers and multinational crop protection companies.
Western France
Western France accounts for 24% share, largely supported by its extensive vineyard and horticulture industries. Wine production in Bordeaux and surrounding areas creates steady demand for effective insecticide formulations. Pyrethroids and neonicotinoids, where permitted, have been prominent, while biological products are gaining traction due to sustainability initiatives. Farmers rely on a mix of chemical and eco-friendly options to protect high-value crops from pest infestations. The market reflects strong consumer-driven expectations for residue-free produce. Western France provides significant opportunities for companies focused on vineyard-specific solutions and innovation.
Central France
Central France captures 18% of the national market, characterized by diverse agricultural activities including cereals, oilseeds, and mixed farming. Insecticides are used intensively in crop cycles to maintain yields under varying climatic conditions. Farmers in this region increasingly combine carbamates and biological solutions within integrated pest management systems. Market growth is shaped by government programs encouraging sustainable practices. Local distributors play an important role in supplying farmers with both conventional and newer eco-certified products. Central France is evolving into a balanced market that reflects both traditional and modern farming approaches.
Southern France
Southern France represents 20% share, supported by its vineyards, orchards, and vegetable farming. Climatic conditions make the region highly vulnerable to pests, driving strong reliance on chemical insecticides. Neonicotinoid restrictions have shifted demand toward pyrethroids and biological alternatives. Public health applications, such as mosquito control, also add to regional demand. Farmers adopt precision agriculture practices to optimize insecticide usage and reduce compliance risks. Southern France continues to provide fertile ground for innovation in crop protection tailored to high-value agriculture.
Eastern France
Eastern France holds the remaining 10% share, with smaller but specialized agricultural activities. Vineyards in Alsace and mixed farming systems shape demand for selective insecticides. Regulatory enforcement is strong, which favors biological solutions and low-residue formulations. Regional adoption is slower compared to leading zones but shows steady improvement with policy support. Public health applications contribute moderately due to seasonal vector control requirements. Eastern France, though smaller in scale, remains an important region for testing and expanding new eco-friendly insecticide products.

Market Segmentations:
By Product Type
- Organophosphates
- Carbamates
- Pyrethroids
- Neonicotinoids
- Biological Insecticides
- Others
By Application
- Agriculture
- Forestry
- Turf & Landscape
- Public Health
- Others
By Region
- North France
- West France
- Central France
- South France
- Eastern France
Competitive Landscape
The France Insecticides Market is highly competitive, shaped by the presence of global leaders and regional specialists. Major players such as Bayer AG, BASF SE, Syngenta, FMC Corporation, ADAMA Agricultural Solutions, and UPL Limited dominate with extensive product portfolios, advanced formulations, and strong distribution networks. These companies leverage research investments to develop eco-friendly and compliant solutions that align with EU regulations. Regional players like Sipcam France and Bioline AgroSciences strengthen competition by focusing on niche segments such as biological insecticides and integrated pest management products. Market participants emphasize innovation, partnerships with distributors, and digital farming integration to capture demand across vineyards, cereals, and horticultural crops. Regulatory restrictions on certain chemical classes drive competition toward safer, sustainable alternatives, intensifying the race for innovation. The landscape reflects a balance between established multinational corporations and agile local firms, ensuring dynamic competition and ongoing transformation within the French crop protection industry.
Key Players
- Bayer AG
- BASF SE
- Syngenta
- FMC Corporation
- ADAMA Agricultural Solutions
- Nufarm Limited
- UPL Limited
- Sipcam France
- Cheminova (FMC)
- Bioline AgroSciences
Recent Developments
- In July 2025, Veganic introduced NOFLY WP in France through a partnership with Futureco Bioscience. The bioinsecticide, developed from Paecilomyces fumosoroseus strain FE 9901, is designed to control whiteflies across all life stages.
- In June 2023, Syngenta Seedcare introduced EQUENTO, a new seed treatment with insecticidal properties, aimed at controlling various soil pests and increasing sustainability in French agriculture.
- In May 2023, Syngenta partnered with Unium Bioscience to launch NUELLO iN, a biological seed treatment designed to reduce nitrogen fertilizer use and improve crop yield in northwest Europe, including France.
- In January 2025, Sumitomo Chemical completed a full acquisition of Philagro Holding S.A., its France-based sales subsidiary for crop protection products. The move strengthens its market presence and distribution capabilities within France.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biological insecticides will continue to rise with expanding organic farming practices.
- Regulatory pressure will push companies to develop safer and low-residue formulations.
- Precision agriculture adoption will enhance efficiency in insecticide application across major crops.
- Vineyards and horticulture will remain key sectors driving demand for specialized insecticides.
- Pest resistance challenges will accelerate research into novel molecules and integrated solutions.
- Public health demand for vector control will expand due to changing climate conditions.
- Partnerships between global firms and local distributors will strengthen product accessibility.
- Farmers will increasingly adopt integrated pest management strategies for sustainable outcomes.
- Digital platforms and AI-driven monitoring will reshape pest management practices.
- Market consolidation will intensify as larger players acquire niche innovators in biological solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the France Insecticides Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Insecticides Market projected to grow between 2025 and 2032?
Which France Insecticides Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Insecticides Market?
Who are the leading companies in the France Insecticides Market?
Which region commanded the largest share of the France Insecticides Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Insecticides Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Insecticides Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 894.17 million → forecast year: USD 1,292.93 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Insecticides Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Insecticides Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Insecticides Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Insecticides Market Drivers
- 3.3 France Insecticides Market Restraints & Challenges
- 3.4 France Insecticides Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Insecticides Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Insecticides Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Insecticides category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Insecticides Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Insecticides Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Insecticides market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Insecticides Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Insecticides Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Insecticides Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Insecticides (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Insecticides Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Insecticides Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Insecticides Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Insecticides Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Insecticides Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Insecticides Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Insecticides Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Insecticides Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Insecticides Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
