
Market Overview:
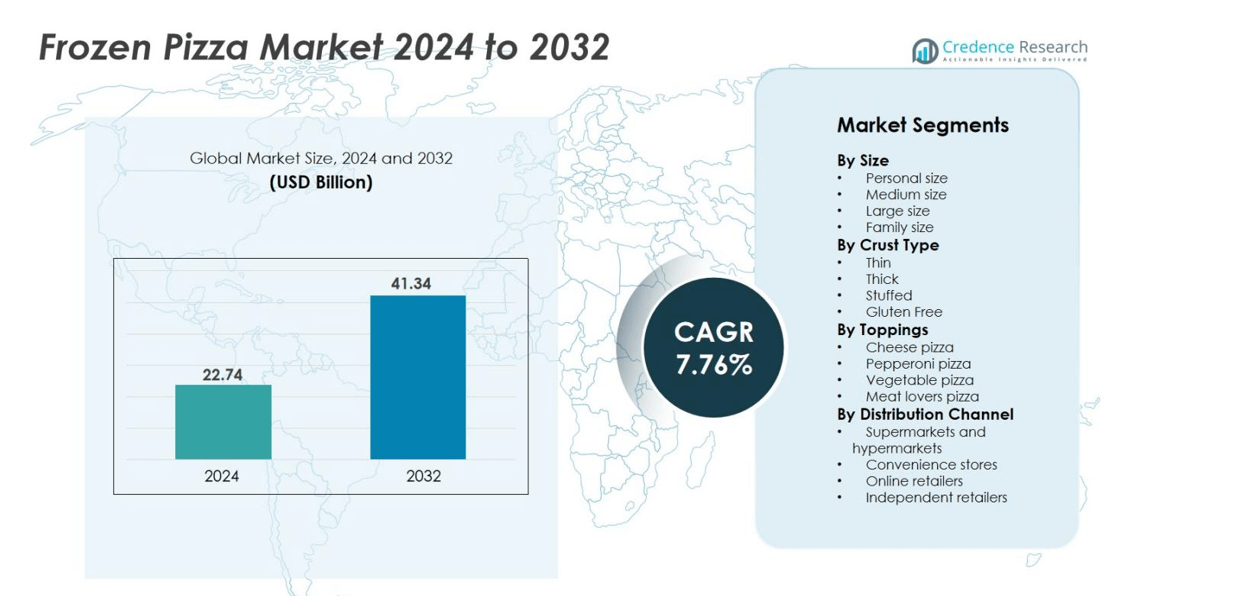
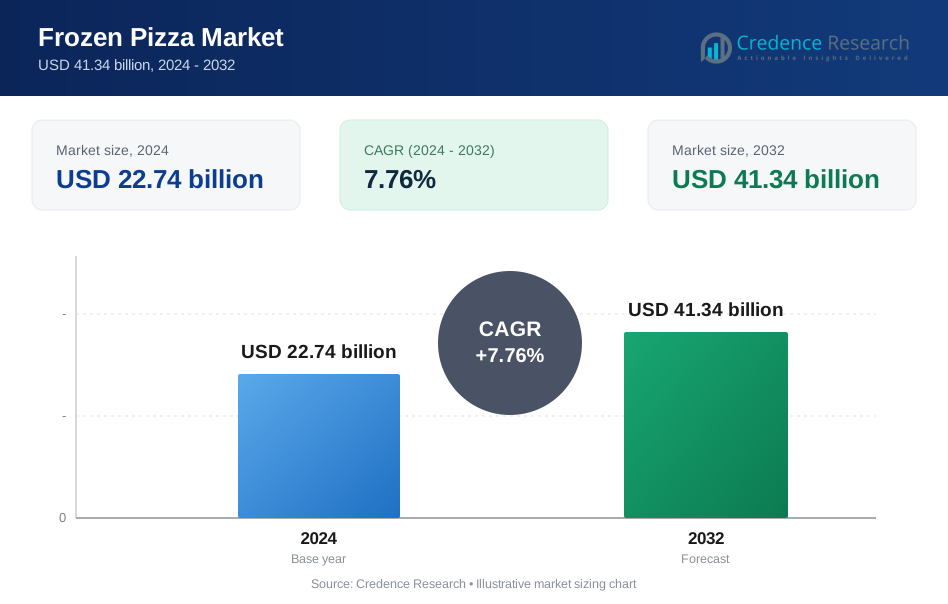
Frozen Pizza market size was valued at USD 22.74 billion in 2024 and is anticipated to reach USD 41.34 billion by 2032, at a CAGR of 7.76% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Frozen Pizza Market Size 2024 | USD 22.74 billion |
| Frozen Pizza Market, CAGR | 7.6% |
| Frozen Pizza Market Size 2032 | USD 41.34 billion |
The Frozen Pizza market is marked by intense rivalry among global and regional producers. Leading companies including Nestlé S.A., Dr. Oetker, McCain Foods Limited, Freiberger Lebensmittel GmbH, Bellisio Foods, Daiya Foods, California Pizza Kitchen, and Jubilant FoodWorks are broadening their portfolios with premium crust varieties, clean-label formulations, and plant-based topping options. Many brands strengthen retail presence through supermarket partnerships and online delivery platforms. North America leads the market with a 38% share, driven by high frozen food consumption and strong cold-chain logistics, while Europe holds 32%, supported by premium product adoption and private-label growth. Continuous innovation and regional flavor customization remain key competitive strategies.
Market Insights
- The Frozen Pizza market was valued at USD 22.74 billion in 2024 and will reach USD 41.34 billion by 2032, growing at a CAGR of 7.76%.
- Convenience and ready-to-eat meal demand drive growth, supported by busy lifestyles, strong retail penetration, and expanding online grocery channels.
- Thin-crust pizzas hold the largest crust share at 41%, while cheese toppings lead with 34%, and personal-size formats dominate size preferences.
- Competition remains high, with leading players such as Nestlé, Dr. Oetker, McCain Foods, Freiberger, and Bellisio Foods launching clean-label, plant-based, and gourmet products to strengthen differentiation.
- North America leads with 38% market share, followed by Europe at 32%, while Asia Pacific captures 18% and remains the fastest-growing region due to rising urbanization and adoption of Western-style frozen foods.
Market Segmentation Analysis
By Size
Personal-size frozen pizzas lead this category with a 38% market share due to rising single-person households and demand for convenient, portion-controlled meals. Quick preparation time and lower price points make this format attractive for students and working professionals. Medium and large sizes continue to appeal to families seeking shared meals, while family-size formats gain traction through value packs offered by major retailers. However, the personal segment remains dominant as busy consumers prefer grab-and-go meals and healthier calorie control, supporting steady adoption across supermarkets and online grocery channels.
- For instance, Nestlé launched a new line of personal frozen pizzas in the U.S. specifically designed for calorie control and busy consumers, priced at around $5 and tailored for people managing weight with GLP-1 drugs, highlighting the focus on health-conscious portion sizes.
By Crust Type
Thin-crust frozen pizzas dominate the crust segment with a 41% market share, driven by consumer interest in lighter textures, lower calories, and faster baking times. Brands position thin-crust variants as a healthier and crispier alternative to traditional thick bases, boosting repeat purchases. Stuffed crust appeals to indulgence-driven buyers, while gluten-free options grow rapidly among health-conscious consumers and people with wheat intolerance. Despite this growth, thin crust remains the leading choice across North America and Europe, supported by premium product launches and artisanal-style recipes.
- For instance, Domino’s recently launched its first-ever Parmesan Stuffed Crust Pizza, made with mozzarella stuffed buttery-flavored dough topped with garlic seasoning and Parmesan, targeting indulgence-driven buyers with a premium product.
By Toppings
Cheese pizza holds the largest share at 34%, making it the dominant topping segment thanks to its universal taste and lower price compared to meat-based options. Pepperoni and meat-lover variants attract buyers who prefer high-protein meals, especially in Western markets. Vegetable-based toppings are gaining popularity among vegan and flexitarian consumers, supported by plant-based cheese and clean-label ingredients. However, cheese pizzas maintain leadership because they target all age groups, offer freezer-friendly packaging formats, and serve as a base for customization at home.
Key Growth Drivers
Rise of Convenient and Ready-to-Eat Meals
Growing demand for quick meals continues to propel frozen pizza sales across global markets. Busy working lifestyles, dual-income households, and limited time for cooking increase reliance on ready-to-eat products with long shelf life. Frozen pizzas require minimal preparation, making them popular among students, office workers, and families with hectic schedules. Retail chains offer a wide range of flavors and crust types, which support variety and repeat purchases. Expansion of microwave-friendly and oven-ready packaging also enhances product convenience. As rapid urbanization accelerates, especially in Asia and Latin America, more consumers adopt frozen meal habits, positioning frozen pizza as a preferred comfort food.
- For instance, Rustica Foods launched a line of frozen pizzas in November 2024, including varieties like Double Pepperoni and 4 Cheese & Garlic, catering to diverse taste preferences with ready-to-bake convenience.
Innovation in Premium and Health-Focused Variants
Product innovation drives strong growth as brands introduce gluten-free, whole wheat, vegan cheese, and plant-based toppings to meet changing dietary habits. Consumers seeking healthier alternatives prefer lower-calorie thin crusts, reduced sodium options, and high-fiber formulations. Manufacturers also use organic ingredients, artisan sauces, and clean-label claims to capture premium buyers. The rise of plant-based diets supports rapid growth of meatless toppings and dairy-free cheese, especially among flexitarian and lactose-intolerant consumers. Brands invest in natural preservatives instead of synthetic additives, improving nutritional appeal without compromising taste or texture.
- For instance, Oggi has expanded its offerings by partnering with Beyond Meat to launch entirely plant-based pizzas featuring vegan mozzarella and plant-based sausage and beef crumbles, tapping into the rising demand for vegan and flexitarian diets in North America.
Expansion of E-Commerce and Direct-to-Consumer Channels
Online grocery platforms and quick-commerce delivery models create new growth opportunities for frozen pizzas. Consumers prefer doorstep delivery of frozen meals, especially after the widespread shift to digital shopping. Supermarkets partner with delivery apps to offer real-time inventory and discount offers, making frozen pizzas easily accessible. Direct-to-consumer subscription boxes and brand-owned web stores offer customizable toppings, specialty dietary products, and bulk pricing. Improved cold-chain logistics, temperature-controlled packaging, and reliable last-mile delivery reduce spoilage risks. As digital adoption accelerates in emerging markets, online distribution helps brands reach consumers beyond traditional retail stores, supporting strong market penetration and stable sales volumes.
Key Trends & Opportunities
Growing Popularity of Premium and Gourmet Flavors
Consumers increasingly seek restaurant-style frozen pizzas offering wood-fired crusts, authentic sauces, and unique toppings like goat cheese, truffle oil, or smoked meats. Gourmet frozen pizzas replicate artisanal quality at a lower cost compared to dine-in restaurants or delivery chains. Brands experiment with international flavors such as Mediterranean, Mexican, or Asian-inspired toppings to attract adventurous buyers. The rise of premium supermarket chains and specialty food stores also supports higher-priced gourmet options. As consumers shift towards indulgent comfort foods with high quality, this premiumization trend strengthens revenue potential, especially in urban markets.
- For instance, Kagome India produces authentic pizza sauce made from vine-ripened tomatoes and select herbs without preservatives, providing a fresh, natural flavor that elevates frozen pizza quality.
Increasing Adoption of Plant-Based and Clean-Label Products
Health-conscious consumers and vegan buyers accelerate adoption of plant-based frozen pizzas. These products use dairy-free cheese, vegetable proteins, and wheat-free crusts to meet special diets. Clean-label ingredient lists, free from trans fats, artificial flavors, or preservatives, attract parents and wellness-focused buyers. Brands highlight nutritional claims such as high fiber, reduced calories, and organic ingredients to build trust. Strong growth in lactose-intolerant and gluten-sensitive populations further drives demand. As food regulations tighten and consumer awareness rises, clean-label innovation becomes a key competitive strategy for new entrants and established manufacturers.
- For instance, Daiya Foods has introduced its melty plant-based mozzarella that enhances the sensory appeal of dairy-free pizzas, supporting its growth in the health-focused segment.
Key Challenges
High Competition from Fresh and Fast-Food Alternatives
Frozen pizzas face strong competition from food delivery services, fresh bakery pizzas, and quick-service restaurants. Consumers often prefer hot, freshly made pizza with customizable toppings, making delivered meals a strong substitute. In markets where delivery apps offer low-cost deals and fast service, frozen pizza struggles to compete on taste and freshness perception. Restaurants advertise fresh dough, premium cheese, and healthier ingredient claims, attracting customers who view frozen meals as less nutritious. To counter this challenge, frozen brands focus on artisanal-style crusts, premium toppings, and healthier formulations, but price-sensitive buyers may still shift toward discounted restaurant offers.
Cold-Chain and Storage Limitations in Emerging Markets
Frozen pizza relies on reliable cold-chain logistics from production to retail shelves. In emerging regions, inadequate freezer storage, power instability, and high logistics costs create distribution barriers. Small stores may avoid frozen products due to limited freezer capacity, restricting rural penetration. Transportation challenges increase spoilage risk and raise product prices, reducing affordability. As a result, market growth remains slower in regions without strong infrastructure. Companies must invest in logistics partnerships, centralized distribution hubs, and insulated packaging to improve availability. Without these improvements, penetration in developing countries will remain restricted despite high demand potential.
Regional Analysis
North America
North America holds the largest market share at 38%, supported by high consumption of ready-to-eat meals, strong retail presence, and widespread adoption of frozen foods in household diets. The U.S. drives most sales through supermarket chains, club stores, and online grocery platforms offering large product assortments. Consumers prefer premium thin-crust, gluten-free, and gourmet toppings, pushing brands to innovate healthier and artisanal-style variants. Canada follows a similar demand pattern, with rising interest in organic and plant-based toppings. Strong cold-chain logistics and aggressive promotional offers ensure consistent product availability, reinforcing the region’s leadership position.
Europe
Europe captures 32% market share, driven by strong demand in Germany, the U.K., Italy, and France. Consumers show high preference for authentic flavors, sourdough crusts, and clean-label formulations. Premium frozen pizzas compete directly with restaurant-style offerings, attracting buyers seeking high-quality meals at affordable prices. Growth in vegan options and lactose-free cheese supports increasing adoption among health-conscious and gluten-sensitive consumers. Supermarkets and discount retail chains expand private-label offerings, boosting sales volume across Western and Central Europe. Efficient refrigeration infrastructure and mature retail distribution networks sustain stable growth across the region.
Asia Pacific
Asia Pacific accounts for 18% market share, but remains the fastest-growing region due to rapid urbanization and rising acceptance of Western fast foods. Young consumers and working professionals show strong interest in convenient frozen meals, especially in Japan, South Korea, China, and Australia. International brands introduce localized flavors such as seafood, spicy sauces, and vegetarian toppings to appeal to regional tastes. Expanding cold-chain logistics, e-commerce penetration, and modern retail stores enhance product accessibility. Increasing disposable income and aggressive marketing campaigns further strengthen market growth, making Asia Pacific a key long-term opportunity.
Latin America
Latin America holds 7% market share, led by Brazil, Mexico, and Argentina. Demand grows as supermarket chains and hypermarkets expand frozen food sections with economy and premium product options. Consumers prefer large and family-sized formats designed for group dining, boosting volume sales. Economic private-label offerings attract price-sensitive households. Limited cold-chain infrastructure in rural locations restricts full market penetration, but urban regions see steady adoption. Promotions, bundled offers, and brand partnerships with retail chains strengthen visibility, supporting gradual expansion of frozen pizza consumption in the region.
Middle East & Africa
The Middle East & Africa region represents 5% market share, supported by growing modern retail distribution in the UAE, Saudi Arabia, and South Africa. Increasing expatriate population and demand for Western-style fast foods contribute to frozen pizza adoption. Manufacturers introduce halal-certified, vegetarian, and cheese-focused variants to meet regional dietary preferences. However, high product pricing and limited freezer capacity in small stores restrict wider access. Expansion of supermarket chains, online grocery platforms, and cold-storage facilities gradually improves availability, positioning the region for future growth despite its smaller base.
Market Segmentations:
By Size
- Personal size
- Medium size
- Large size
- Family size
By Crust Type
- Thin
- Thick
- Stuffed
- Gluten Free
By Toppings
- Cheese pizza
- Pepperoni pizza
- Vegetable pizza
- Meat lovers pizza
By Distribution Channel
- Supermarkets and hypermarkets
- Convenience stores
- Online retailers
- Independent retailers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Frozen Pizza market remains highly competitive, with global and regional players focusing on product quality, flavor innovation, and wider retail penetration. Leading companies such as Nestlé S.A., Dr. Oetker, McCain Foods, California Pizza Kitchen, and Freiberger Lebensmittel GmbH expand portfolios with thin-crust, gluten-free, and gourmet-style offerings to attract health-conscious and premium buyers. Private-label brands from large retail chains further intensify competition by offering cost-effective alternatives. Manufacturers invest in clean-label ingredients, organic toppings, and environmentally friendly packaging to strengthen brand appeal. E-commerce distribution, quick-commerce platforms, and direct-to-consumer models support broader market reach. Strategic marketing, partnerships with supermarkets, and promotional pricing drive higher volumes in developed regions, while localization of flavors supports expansion in emerging markets. Overall, innovation, distribution strength, and pricing strategy remain central competitive factors.
Key Player Analysis
- Freiberger Lebensmittel GmbH Co
- One Planet Pizza
- Bellisio Foods, Inc.
- Jubilant FoodWorks
- McCain Foods Limited
- The Simply Good Foods Company
- Dr. Oetker
- Nestlé S.A.
- California Pizza Kitchen
- Daiya Foods
Recent Developments
- In November 2025, Urban Farmer completed the acquisition of CAULIPOWER, forming an integrated frozen foods platform emphasizing healthier frozen pizzas and dough products.
- In September 2025, MBC Companies acquired Alpha Foods to strengthen its frozen pizza manufacturing capabilities and expand its product portfolio.
- In May 2025, Palermo Villa Inc. partnered with Ragu to launch a new frozen pizza line featuring sauces inspired by the Ragu brand.
- In 2023, Schwan’s Company opened a state-of-the-art frozen pizza facility in Kansas, USA, boosting production capacity for its Red Baron and Freschetta brands to meet rising demand.
Report Coverage
The research report offers an in-depth analysis based on Size, Crust, Toppings, Distribution and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for convenient ready-to-eat meals will continue to rise among busy consumers.
- Premium and gourmet frozen pizzas will gain stronger traction in retail stores.
- Plant-based toppings and dairy-free cheese options will expand product portfolios.
- Gluten-free and clean-label formulations will attract health-conscious buyers.
- Online grocery platforms and quick-commerce delivery will boost market penetration.
- Brands will invest in sustainable packaging and cleaner ingredient lists.
- Restaurant-style crusts and artisanal flavors will improve product quality perception.
- Private-label frozen pizzas will grow in supermarkets due to cost advantage.
- Emerging markets will adopt frozen pizzas faster as cold-chain logistics improve.
- Flavor localization will help international brands reach regional consumer preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Frozen Pizza market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Frozen Pizza market projected to grow between 2025 and 2032?
Which Frozen Pizza market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Frozen Pizza market?
Who are the leading companies in the Frozen Pizza market?
Which region commanded the largest share of the Frozen Pizza market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 22.74 billion → 2032: USD 41.34 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Frozen Pizza Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Frozen Pizza Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Frozen Pizza Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Frozen Pizza Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Frozen Pizza Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Frozen Pizza Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Frozen Pizza Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Frozen Pizza Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 22.74 billion → 2032: USD 41.34 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Frozen Pizza Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Frozen Pizza Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Frozen Pizza Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Frozen Pizza Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

