
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Galvanized Rebar Market Size 2024 | USD 282.28 million |
| Galvanized Rebar Market, CAGR | 5.7% |
| Galvanized Rebar Market Size 2032 | USD 439.8 million |
Market Overview:
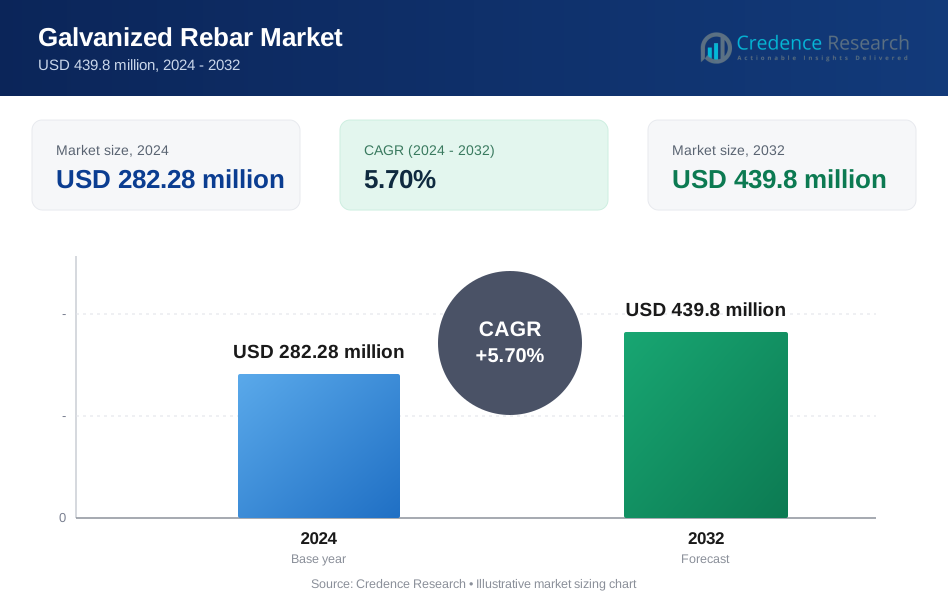
Galvanized Rebar Market size was valued at USD 282.28 million in 2024 and is anticipated to reach USD 439.8 million by 2032, at a CAGR of 5.7% during the forecast period (2024-2032).
The Galvanized Rebar Market growth reflects rising infrastructure investment and robust construction activity worldwide. Expanding road, bridge and railway projects stimulate demand for corrosion-resistant reinforcement. Growing urban populations drive high-rise residential and commercial construction, which requires durable materials. Stringent regulations and standards encourage use of protective coatings to extend structural service life and reduce maintenance costs. Manufacturers innovate by integrating advanced galvanizing techniques that improve adhesion and uniformity. Sustainability concerns also support adoption of galvanized rebar, which offers longer lifespan and recyclability, aligning with green building objectives. Digitalization trends and adoption of IoT sensors enable real-time monitoring of corrosion and structural health. Key players invest in capacity expansion to meet rising demand.
Asia Pacific dominates the Galvanized Rebar Market, driven by rapid urbanization and government-led infrastructure spending in China, India and Southeast Asia. Japan and South Korea also benefit from renovation initiatives and high standards for structural safety. North America follows, supported by federal infrastructure bills and renovation of aging bridges and highways. The United States leads regional consumption, with state-level incentive programs further boosting demand. Europe records steady growth under strict building codes and growing demand for rehabilitation of legacy structures. The Middle East and Africa witness niche adoption in oil and gas facilities and mega construction projects, while Latin America shows cumulative growth in urban housing but faces supply chain and cost challenges. Regional manufacturers focus on localizing production to optimize supply chains and reduce lead times.
Market Insights:
- The Galvanized Rebar Market was valued at USD 282.28 million in 2024 and is projected to reach USD 439.8 million by 2032, driven by rising infrastructure investment and durable construction needs.
- High demand from road, bridge, and railway projects boosts usage of galvanized rebar due to its superior corrosion resistance and long-term structural integrity.
- Regulatory bodies like the Bureau of Indian Standards mandate galvanized coatings under ASTM A767, enhancing durability and compliance across large-scale public works.
- Asia Pacific holds 67% of the global market share, led by China and India’s aggressive infrastructure programs and regional manufacturing capacity expansions.
- Sustainability goals push developers to adopt recyclable materials; galvanized rebar aligns with green building practices and offers life-cycle cost savings.
- Challenges include zinc price volatility and supply disruptions, although major producers like Hindustan Zinc ensure production stability for consistent market support.
- Technological barriers and workforce skill gaps delay automation in smaller mills, limiting the adoption of smart galvanization processes and digital traceability systems.
Market Drivers:
Infrastructure Expansion and Urban Growth:
Rapid infrastructure expansion in emerging economies drives reinforced concrete projects. The Galvanized Rebar Market meets demand for corrosion-resistant reinforcement. It supports road, bridge and railway construction that need durable materials. Urban migration fuels high-rise development that relies on coated steel for longevity. Governments fund public works to improve connectivity and stimulate economy. Contractors prefer galvanized options to reduce maintenance and extend service life.
Regulatory Standards and Durability Requirements:
Stringent building codes mandate protective coatings on reinforcement to ensure structural safety. The Galvanized Rebar Market addresses durability requirements under modern regulations. It reduces rust formation in aggressive environments. Inspection protocols favor coated rebar to minimize liability and enhance quality control. Project managers select galvanized solutions to comply with health and safety mandates. Industry stakeholders recognize the value of long-term performance over initial cost.
- For instance, the Bureau of Indian Standards references ASTM Standard A767, which specifies zinc-coated (galvanized) steel bars for reinforced concrete, ensuring compliance with durability mandates in Indian infrastructure projects.
Advancements in Galvanization Techniques and Quality Control:
Manufacturers adopt thermal spray and continuous hot-dip processes for uniform coating. The Galvanized Rebar Market benefits from improved adhesion and steel coverage. It matches precise specifications through automated monitoring and sensor integration. Quality teams implement real-time testing to maintain consistency. Enhanced coating processes cut waste and streamline workflows. Construction firms rely on certified products for predictable performance.
- For instance, Asia’s first-ever Continuous Galvanized Rebar (CGR) manufacturing facility, launched by Madhav KRG Group in association with the International Zinc Association and supported by Hindustan Zinc Limited, utilizes the continuous hot-dip galvanizing process as specified in ASTM A1094/A1094M, enabling the production of ZNCOAT TEMPCORE TMT BARS with superior corrosion resistance and quality assurance.
Sustainability Focus and Life-Cycle Cost Efficiency:
Environmental priorities push adoption of recyclable materials in construction. The Galvanized Rebar Market aligns with green building trends and circular economy goals. It extends structure life span and cuts replacement frequency. Life-cycle assessments highlight galvanized steel’s lower carbon footprint. Developers calculate long-term cost savings from reduced repair cycles. Industry leaders promote coated rebar for its economic and environmental benefits.
Market Trends:
Innovations in Coating Technologies and Alloy Composition:
Industry leaders develop advanced galvanizing processes that deliver uniform zinc layers and strong adhesion. Galvanized Rebar Market shows adoption of duplex systems combining zinc and polymer topcoats. It extends protection against corrosion in marine and industrial environments. Research teams evaluate alloy composition to improve strength and weldability. Project teams specify high-tensile options that reduce steel weight and cut transportation costs. Manufacturers introduce small-diameter rebar to fit congested reinforcement layouts. Quality protocols enforce strict coating thickness and adhesion tests to guarantee consistency.
For instance, the Florida Department of Transportation (FDOT) has conducted extensive evaluations of hot-dip galvanized rebar (HDGR) produced according to ASTM A767, emphasizing its improved corrosion resistance and mechanical properties for use in marine substructures.
Integration of Digital Construction Methods and Prefabrication Models:
Building firms integrate digital tracking solutions that monitor coating quality and installation status. Galvanized Rebar Market supports cloud-based platforms that record batch data and lifecycle metrics. It aligns with BIM workflows and delivers precise material estimates before fabrication. Contractors adopt preassembled rebar cages to streamline onsite handling and reduce labor time. Suppliers partner with modular plant operators to deliver ready-to-install reinforcement modules. Standard protocols ensure compatibility across global supply chains and prevent errors. Industry conferences highlight case studies that demonstrate time savings and cost control.
- For instance, Rebar Cloud offers cloud-based solutions with full bundle traceability from mill to construction site, supporting 2D and 3D BIM integration and real-time tracking of steel reinforcement processes.
Market Challenges Analysis:
Inconsistent Zinc Supply and Price Volatility:
Producers face erratic zinc feedstock availability and wide price swings in commodity markets. The Galvanized Rebar Market depends on steady zinc supply to maintain coating quality. It strains profit margins when metal costs spike unpredictably. Procurement teams struggle to secure long-term contracts at stable rates. Volatile prices force construction firms to revise budgets and timelines. Material cost uncertainty hampers strategic planning across project lifecycles.
- For instance, Hindustan Zinc Limited, the world’s largest integrated zinc producer, has demonstrated operational resilience and supply stability by consistently achieving over one million tonnes of metal production annually for the past three years, supporting steady zinc availability for downstream industries despite global market volatility.
Technological Integration Barriers and Workforce Skill Gaps:
Stakeholders encounter obstacles when they adopt digital monitoring systems and automation. The Galvanized Rebar Market requires skilled technicians to operate advanced galvanization equipment. It delays modernization when training programs lag industry requirements. Smaller mills find it hard to invest in smart factories due to high capital outlay. Workforce shortages in metallurgical and quality control roles widen operational inefficiencies. Companies weigh the cost of talent development against expected productivity gains. Without targeted talent development, new technologies remain underutilized.
Market Opportunities:
Expansion in Infrastructure Projects and Sustainable Construction:
Global efforts to upgrade bridges and highways present significant growth potential. The Galvanized Rebar Market can leverage this momentum by providing durable reinforcement solutions. Government funding for public works demands corrosion-resistant materials. Increased interest in sustainable structures drives uptake of zinc-treated steel with extended service life. Investment in water treatment and coastal defense schemes further broadens market scope. Private developers seek materials that lower maintenance budgets over project lifetimes. Contractors choose galvanized options to ensure project longevity and reduce total ownership cost.
Opportunity in Modular Construction and Process Efficiency:
Modular construction methods reduce onsite labor and accelerate project delivery. The Galvanized Rebar Market can support prefab initiatives with pre-assembled reinforcement cages. Integration of steel producers with logistics providers enhances supply chain certainty. Local mill establishment in emerging regions cuts lead times and shipping costs. Collaborations with coating technology firms enable tailored solutions for harsh environments. Standardization efforts simplify specification and approval processes across contractors. It expands options for complex reinforcement designs in challenging build scenarios.
Market Segmentation Analysis:
By Application
Strong demand in commercial development fuels segment growth. The Galvanated Rebar Market meets requirements for durable reinforcement in residential and commercial structures. It supports infrastructure and industrial projects through high corrosion resistance. Road and bridge construction uses galvanized rebar to extend service life in harsh climates. Specialized agricultural and water treatment facilities adopt this segment for reliability. This segment commands the largest share and attracts manufacturers to optimize capacity. Public-private infrastructure partnerships in remote areas drive demand for corrosion-resistant reinforcement.
By Product Type
Standard diameter rebar segment dominates due to wide applicability. The Galvanated Rebar Market offers both standard and small-diameter options that meet structural and retrofit demands. It delivers consistent coating thickness and meets tensile strength requirements under current standards. Low-carbon steel rebar gains traction in sustainability-driven projects. High-tensile types appeal to high-rise and industrial developments that require reduced weight. Product innovation increases efficiency and uniformity in coating processes.
By Distribution Channel
Direct sales channel retains strong presence through established producer-distributor relationships. The Galvanated Rebar Market leverages direct procurement to ensure material traceability and quality assurance. It benefits from long-term contracts that stabilize supply and pricing. Specialized distributors and wholesalers serve regional construction firms with flexible order quantities. E-commerce platforms begin to influence smaller-scale projects to provide quick access. Partnerships between mills and logistics providers enhance last-mile delivery.
Segmentations:
By Application
- Residential construction
- Commercial construction
- Infrastructure projects
- Industrial facilities
By Product Type
- Standard rebar
- Small-diameter rebar
- High-tensile rebar
- Low-carbon rebar
By Distribution Channel
- Direct sales
- Distributors and wholesalers
- E-commerce
By Operating Mechanism
- Hot-dip galvanizing
- Electro-galvanizing
- Thermal spray
By End-User
- Contractors
- Prefabricators
- Infrastructure developers
- Industrial operators
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia Pacific: Capitalizes on Urbanization and Infrastructure Spending
Asia Pacific captures 67% of the global Galvanized Rebar Market. China drives demand for corrosion-resistant reinforcement in highway and high-speed rail projects. India allocates resources to upgrade bridges and urban transport networks. Southeast Asian nations invest in coastal protection and water treatment facilities. Stakeholders find strong uptake in these projects due to performance benefits while local producers expand capacity to serve rising regional demand. It enhances supply chain resilience by situating mills closer to end users. Public-private infrastructure partnerships in remote areas drive demand for corrosion-resistant reinforcement.
North America: Benefits from Infrastructure Renewal and Modernization Drives
North America holds 14% of the global Galvanized Rebar Market. Federal funding replaces aging bridges and highways under national programs. Canada invests in public transit upgrades and urban development schemes. Contractors specify galvanized steel to meet stringent safety and corrosion-protection standards. It secures steady growth through stable supply chains and local manufacturing, while regional mills adapt production to match local specifications and delivery schedules. It supports private developers seeking low-maintenance building materials. Industry consolidation through mergers among local producers shapes competitive dynamics.
Europe: Pursues Durability under Stringent Regulatory Mandates
Europe represents 14% of the global Galvanized Rebar Market. EU building codes mandate corrosion protection for reinforcement. Germany leads investment in renewable energy infrastructure and industrial parks. The United Kingdom renovates historical structures using modern reinforcement techniques. France and Italy finance public works and water treatment facilities. It aligns with green directives by offering recyclable steel products and ensures consistent coating quality through rigorous third-party audits. The EU’s Green Deal allocates funding to resilient infrastructure projects, boosting demand for coated rebar.
Key Player Analysis:
- Commercial Metals Company
- Nucor
- ZINKPOWER
- Debrunner Acifer Bewehrungen
- Madhav KRG Group
- Xiamen New Steel Metal Products Co., Ltd
- Jenco Group
- ArcelorMittal
- Baosteel Group
Competitive Analysis:
The Galvanized Rebar Market features a competitive landscape shaped by global steel producers, regional manufacturers, and niche players focused on corrosion-resistant reinforcement. It includes key companies such as Nucor Corporation, ArcelorMittal, Gerdau S.A., Tata Steel, and Commercial Metals Company, each leveraging integrated production, broad distribution, and technical expertise. Firms compete on coating quality, product certification, and alignment with international standards such as ASTM A767 and A1094. Market players focus on capacity expansion, automation, and zinc coating innovation to meet project-specific requirements and reduce lead times. Strategic acquisitions and partnerships with infrastructure developers strengthen supply security and project visibility. The shift toward sustainable construction amplifies demand for long-lasting, recyclable materials, compelling companies to invest in advanced galvanization technologies. It rewards firms that offer consistent quality, efficient logistics, and strong customer support. Localized production and responsive service models help regional suppliers compete with multinational corporations across cost-sensitive and regulation-driven markets.
Recent Developments:
- In March 2023, Commercial Metals Company (CMC) announced investments of up to $600 million for growth projects and acquisitions, including the purchase of a metals recycling company and a post-tensioning solutions producer, to meet rising demand from infrastructure spending in North America.
- In January 2025, ArcelorMittal Nippon Steel India announced the commissioning of two new advanced steel production lines at its Gujarat facility, including a Continuous Galvanizing Line (CGL) and a Continuous Galvanizing and Annealing Line (CGAL).
Market Concentration & Characteristics:
The Galvanized Rebar Market shows moderate concentration, dominated by a mix of global steel leaders and regional producers. It includes firms with integrated operations that control zinc sourcing, coating processes, and downstream distribution. High entry barriers arise from capital intensity, environmental compliance, and adherence to international standards. It favors players that offer consistent coating quality, lifecycle performance, and reliable logistics. The market supports standardized product dimensions, but variations in coating thickness and application methods enable differentiation. Demand concentrates in infrastructure-heavy regions where corrosion resistance is critical. It benefits from regulatory mandates, public project specifications, and sustainability goals. Procurement decisions depend on performance certifications, supply lead times, and total cost of ownership. It also reflects a growing preference for local production facilities to reduce delays and ensure quality assurance.
Report Coverage:
The research report offers an in-depth analysis based on Application, Product Type, Distribution Channel, Operating Mechanism, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Galvanized Rebar Market will expand as governments invest in resilient infrastructure to meet long-term urban development goals.
- Rising concerns over structural degradation in marine and humid environments continue to drive demand for corrosion-resistant reinforcement.
- Construction firms are increasingly specifying galvanized rebar in high-value public and private projects to reduce lifecycle maintenance costs.
- Regulatory pressure is pushing builders to adopt materials that meet higher durability and sustainability benchmarks.
- Advancements in automated galvanization processes are streamlining production and lowering operational costs for manufacturers.
- Growing interest in green buildings is supporting the adoption of galvanized rebar due to its recyclability and environmental performance.
- Demand in Asia-Pacific and Latin America is accelerating, supported by major transport and energy infrastructure expansion.
- Suppliers are focusing on product innovation, such as dual-layer coatings and hybrid alloys, to enhance competitiveness.
- Industry players are forming partnerships with contractors and government bodies to secure long-term supply contracts.
- The market will continue to benefit from rising awareness among engineers and architects about galvanized rebar's benefits in extending structure lifespan.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Galvanized Rebar Market?
What factors are driving the growth of the Galvanized Rebar Market?
What are some challenges faced by the Galvanized Rebar Market?
Who are the major players in the Galvanized Rebar Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Galvanized Rebar Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Galvanized Rebar Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 282.28 million → 2032: USD 439.8 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Galvanized Rebar Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Galvanized Rebar Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Galvanized Rebar Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Galvanized Rebar Market Drivers
- 3.3 Galvanized Rebar Market Restraints & Challenges
- 3.4 Galvanized Rebar Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Galvanized Rebar Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Galvanized Rebar Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Galvanized Rebar category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Galvanized Rebar Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Galvanized Rebar Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Galvanized Rebar market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Galvanized Rebar Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Galvanized Rebar Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Galvanized Rebar Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Galvanized Rebar (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Galvanized Rebar Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Galvanized Rebar Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Galvanized Rebar Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Galvanized Rebar Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Galvanized Rebar Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Galvanized Rebar Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Galvanized Rebar Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Galvanized Rebar Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Galvanized Rebar Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
