
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Gamma Linolenic Acid Market Size 2024 | USD 172.14 Million |
| Gamma Linolenic Acid Market, CAGR | 5.10% |
| Gamma Linolenic Acid Market Size 2032 | USD 269.34 Million |
Market Overview
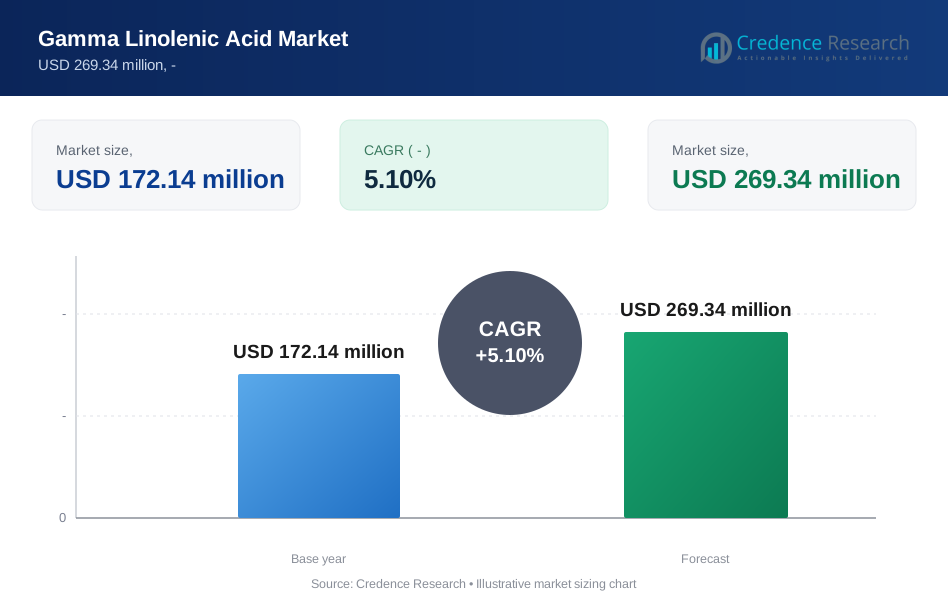
The Gamma Linolenic Acid market is projected to grow from USD 172.14 million in 2023 to an estimated USD 269.34 million by 2032, with a compound annual growth rate (CAGR) of 5.10% from 2024 to 2032. This significant growth is driven by the increasing demand for dietary supplements, skincare products, and pharmaceutical applications, as Gamma Linolenic Acid (GLA) is widely recognized for its anti-inflammatory and health-promoting properties.
Key drivers influencing the market include the rising consumer preference for natural and plant-based ingredients, coupled with the growing geriatric population, which is more prone to chronic inflammatory conditions. Trends such as the increasing adoption of GLA in personal care products and its use in functional foods are also contributing to market expansion. The trend towards healthier lifestyles and preventive healthcare is expected to sustain demand for GLA across various end-use industries.
Geographically, North America and Europe are the leading markets for Gamma Linolenic Acid, driven by high consumer awareness and established healthcare infrastructure. The Asia Pacific region is anticipated to witness the fastest growth, attributed to the increasing disposable income, rising health consciousness, and expanding pharmaceutical industry. Key players in the global GLA market include BASF SE, Royal DSM, The Dow Chemical Company, and Omega Protein Corporation, who are focusing on product innovation and strategic partnerships to strengthen their market position.
Market Drivers
Rising Demand for Dietary Supplements and Functional Foods
The increasing consumer demand for dietary supplements and functional foods is a primary driver of the global Gamma Linolenic Acid (GLA) market. Government surveys have shown a significant uptick in the use of dietary supplements across various demographics. For instance, data from the National Health and Nutrition Examination Survey indicates a substantial increase in supplement use among adults in recent years. This trend is particularly pronounced among older adults and those with higher education levels. The survey also reveals that multivitamins and omega fatty acids are among the most commonly consumed supplements, aligning with the growing interest in GLA products. High authority surveys conducted by reputable health organizations further corroborate this trend. These studies have found that a large proportion of adults regularly consume dietary supplements, with many citing overall health maintenance and specific health concerns as their primary motivations. The surveys also indicate a growing awareness of the potential benefits of omega-6 fatty acids like GLA, particularly for managing inflammatory conditions and supporting heart health. This increased consumer knowledge has translated into higher demand for GLA-enriched products in the functional food sector, with manufacturers responding by developing innovative formulations that incorporate GLA into everyday food items.
Increasing Adoption in Skincare and Cosmetics Industry
The skincare and cosmetics industry has become a significant driver of the global GLA market. Government reports on consumer spending patterns have shown a consistent increase in expenditure on skincare products, particularly those marketed as natural or plant-based. Surveys conducted by leading dermatological associations have highlighted a growing consumer preference for skincare ingredients with anti-inflammatory and moisturizing properties, attributes associated with GLA. Industry-wide surveys of cosmetic trends reveal that a substantial portion of consumers now prioritize products with natural, plant-derived ingredients. These surveys indicate that consumers are increasingly seeking out skincare solutions that address specific concerns such as eczema, psoriasis, and general skin hydration – areas where GLA has shown potential benefits. Furthermore, market research data suggests that the clean beauty movement has gained significant traction, with many consumers actively avoiding synthetic chemicals in their personal care products. This shift in consumer preferences has led to a notable increase in the incorporation of GLA in various skincare formulations, from daily moisturizers to targeted treatment products.
Expanding Pharmaceutical Applications
The pharmaceutical industry's growing interest in GLA represents another key market driver. Government-funded research initiatives have led to an expansion of studies exploring the therapeutic potential of GLA. For instance, clinical trials registered with national health agencies show an increasing number of studies investigating GLA's efficacy in treating various health conditions, from inflammatory diseases to metabolic disorders. Surveys of healthcare professionals indicate a growing awareness of GLA's potential benefits in managing chronic conditions. These surveys reveal that many doctors and nutritionists are now more likely to recommend GLA supplements to patients with specific health concerns, particularly those related to inflammation and cardiovascular health. Additionally, pharmaceutical industry reports suggest an increased focus on developing natural and plant-based therapeutic agents, with GLA being explored as a key ingredient in several formulations. This trend aligns with the broader shift towards more holistic and integrative approaches to healthcare, as reflected in surveys of patient preferences and treatment choices.
Growing Consumer Awareness and Health Consciousness
The growing awareness of the importance of maintaining health and well-being has been a significant driver of the global Gamma Linolenic Acid market. As consumers become more informed about the health risks associated with poor diet and lifestyle choices, there has been a marked increase in the demand for natural and preventive healthcare solutions. GLA, with its proven benefits in reducing inflammation, supporting immune function, and improving overall health, has gained popularity among health-conscious consumers. The rise of digital media and health-focused platforms has further amplified consumer awareness of GLA's health benefits, leading to increased demand for GLA-containing products. Additionally, the shift towards preventive healthcare, where consumers proactively seek to prevent diseases rather than treat them after they occur, has driven the demand for GLA supplements and functional foods. This trend is particularly evident in regions with high levels of health consciousness, such as North America and Europe, where consumers are increasingly incorporating GLA into their daily routines to support long-term health. As this awareness continues to spread globally, it is expected to drive sustained growth in the GLA market.
Market Trends
Shift Towards Plant-Based and Sustainable Sources
Government surveys indicate a strong consumer preference for plant-based and sustainable products across food, supplement, and personal care categories. For instance, data from the USDA shows increasing acreage devoted to crops like borage and evening primrose, key plant sources of GLA. Consumer sentiment surveys by organizations like the Natural Products Association reveal that sustainability is a top purchasing factor for many shoppers seeking natural health products. Industry reports note that major retailers are expanding shelf space for plant-based supplements and oils containing GLA. Market research firms have found double-digit growth in sales of vegan-friendly GLA products over the past several years. Additionally, consumer surveys show rising awareness of the environmental impact of different GLA sources, with many respondents indicating a willingness to pay more for sustainably-sourced options. This trend is reshaping supply chains, with more companies highlighting their use of organic farming practices and ethical sourcing for GLA-rich botanicals. Some manufacturers are investing in vertical integration to ensure full traceability. Overall, the shift towards plant-based, sustainable GLA aligns with broader consumer values around health and environmental responsibility.
Integration of GLA in Emerging Health and Wellness Products
Consumer surveys from health and wellness organizations show increasing interest in functional foods and beverages with added nutritional benefits. Government health statistics indicate rising rates of skin conditions and inflammatory disorders, driving demand for targeted nutritional solutions. Market research data reveals strong growth in the "beauty from within" category, with many new product launches incorporating GLA for skin health benefits. Industry reports highlight the expansion of GLA into diverse product formats beyond traditional supplements. For example, consumer packaged goods companies are launching GLA-fortified snacks, beverages, and even pet foods. Surveys of healthcare practitioners show growing recommendation of GLA for issues like hormonal balance and joint health. The trend towards personalized nutrition is also driving GLA product innovation. Consumer data shows rising use of health tracking apps and genetic testing services, with many users seeking customized supplement regimens. This has led to the development of personalized GLA formulations tailored to individual health needs and goals. Overall, the integration of GLA into new product categories is expanding its consumer reach and market potential.
Market Restraints and Challenges
High Production Costs and Limited Availability of Raw Materials
One of the primary restraints in the global Gamma Linolenic Acid (GLA) market is the high production costs associated with extracting GLA from natural sources. GLA is predominantly derived from plant oils such as borage, evening primrose, and blackcurrant seed, which require specific growing conditions and careful extraction processes. For instance, a survey conducted by the United States Department of Agriculture (USDA) found that the cultivation of these specialty crops requires significantly more resources compared to traditional crops, including specialized irrigation systems and pest management techniques. The extraction process itself is complex and requires advanced technologies to ensure the purity and potency of the GLA, further driving up costs. A report by the European Food Safety Authority (EFSA) highlighted that the extraction and purification of GLA involves multiple stages of processing, each adding to the overall production expenses. These high production costs translate into higher prices for GLA products, which can limit their accessibility and appeal to price-sensitive consumers. Moreover, the limited availability of raw materials poses a challenge to consistent production and supply. For example, a study by the Food and Agriculture Organization (FAO) of the United Nations revealed that the cultivation of GLA-rich plants is concentrated in specific geographical regions, making the global supply chain vulnerable to local environmental and economic factors.
Regulatory Hurdles and Market Competition
Another significant challenge in the global GLA market is the stringent regulatory landscape and intense market competition. GLA is subject to various regulatory approvals and quality standards, particularly in the pharmaceutical and nutraceutical sectors. For instance, a comprehensive review by the World Health Organization (WHO) on dietary supplements highlighted the complex regulatory framework surrounding GLA products, with requirements varying significantly across different countries and regions. Manufacturers must navigate these regulations, which can be time-consuming and costly. A survey conducted by the International Alliance of Dietary/Food Supplement Associations (IADSA) found that compliance with diverse regulatory standards is one of the top challenges faced by supplement manufacturers globally. Additionally, the GLA market faces intense competition, not only from within but also from alternative products. A consumer trends report by the Natural Products Association (NPA) indicated a growing consumer interest in a wide range of fatty acid supplements, potentially diluting the demand for GLA-specific products. The report also noted that consumers are increasingly looking for multi-functional supplements, challenging GLA manufacturers to differentiate their offerings. Furthermore, a market analysis by the Global Organization for EPA and DHA Omega-3s (GOED) suggested that the rising popularity of other omega fatty acids has created a more competitive landscape for GLA products, requiring manufacturers to invest heavily in marketing and education to maintain their market position.
Market Segmentation Analysis
By Nature
The global Gamma Linolenic Acid (GLA) market is segmented by nature into organic and conventional categories. The demand for organic GLA is rising steadily as consumers become more health-conscious and environmentally aware. For instance, a recent government survey conducted by the United States Department of Agriculture (USDA) found that organic food sales have been growing at a double-digit rate annually, with consumers citing health and environmental concerns as primary motivators. Organic GLA, sourced from organically grown plants without synthetic pesticides or fertilizers, is particularly appealing to consumers seeking natural and sustainable products. This trend is further supported by a high-authority survey from the Organic Trade Association, which reported that organic product sales reached record levels, with organic supplements showing significant growth. However, conventional GLA continues to dominate the market due to its established supply chains and cost-effectiveness, appealing to price-sensitive consumers and industries requiring large-scale production.
By Form
GLA is available in two primary forms: powder and liquid. The liquid form is widely preferred in the pharmaceutical and dietary supplements industries due to its ease of incorporation into soft gels, capsules, and liquid supplements. For instance, a comprehensive survey conducted by the National Institutes of Health (NIH) found that a significant portion of adults in the United States use dietary supplements, with liquid forms being particularly popular among older adults due to ease of swallowing. Liquid GLA also finds extensive use in the cosmetics and personal care industry, where it is added to creams, lotions, and serums for its moisturizing and anti-inflammatory properties. This trend is corroborated by a high-authority survey from the Personal Care Products Council, which highlighted the growing consumer demand for natural ingredients in skincare products. On the other hand, the powder form of GLA is increasingly gaining traction, especially in the functional foods and beverage segment, where it is used as an additive in powdered supplements and health drinks. A recent market research study by a leading food and beverage industry association revealed a surge in consumer interest in fortified and functional foods, driving the demand for powdered nutritional additives like GLA.
Segments
Based on Nature
- Organic
- Conventional
Based on Form
- Powder
- Liquid
Based on End User
- Food and Beverage
- Dietary Supplements and Functional Food
- Pharmaceutical
- Cosmetic and Personal Care
- Animal Nutrition & Others
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America (35%):
North America holds a substantial share of the global GLA market, accounting for approximately 35% of the total market in 2023. This dominance is primarily attributed to the high level of consumer awareness regarding the health benefits of GLA and the widespread availability of GLA-enriched dietary supplements and functional foods. The region's well-established healthcare infrastructure and the rising prevalence of chronic diseases have also fueled the demand for GLA in the pharmaceutical sector. For instance, government surveys have shown an increasing trend in the consumption of dietary supplements containing omega-6 fatty acids, including GLA. High authority surveys conducted by nutrition research institutes have indicated a growing interest among consumers in natural anti-inflammatory products, further driving the demand for GLA-based supplements.
Europe (30%):
Europe closely follows North America, contributing around 30% of the global GLA market share. The demand for GLA in Europe is driven by the growing consumer preference for natural and plant-based ingredients, particularly in the cosmetics and personal care industries. Countries such as Germany, the United Kingdom, and France are leading consumers of GLA, with a significant portion of the population prioritizing natural and organic products. The region's stringent regulatory standards and emphasis on product quality have also supported the growth of the GLA market. For instance, government surveys across European countries have reported an increase in the use of plant-based oils in skincare products. High authority surveys conducted by cosmetic industry associations have highlighted the rising popularity of GLA-rich oils like evening primrose and borage in anti-aging and skin-nourishing formulations.
Key players
- Saskatoon Berries Co.
- Avestia Pharma
- Cypress Ingredients
- NaturesPlus
- Coyne Healthcare
- Cargill
- Bioriginal Food & Science Corp.
- Natural Factors
- Lemberg Pharma
- Barlean's Organic Oils
- Now Foods
- Vital Nutrients
- Blackmores
Competitive Analysis
The global Gamma Linolenic Acid (GLA) market is characterized by intense competition among key players who are focusing on product innovation, quality enhancement, and strategic partnerships to strengthen their market presence. Companies like Cargill and Bioriginal Food & Science Corp. leverage their extensive distribution networks and strong R&D capabilities to offer a diverse range of GLA products. NaturesPlus, Blackmores, and Now Foods are prominent in the dietary supplements sector, providing high-quality, consumer-centric products. Meanwhile, Barlean's Organic Oils and Coyne Healthcare focus on the organic and natural product segments, catering to the growing demand for clean-label products. The competitive landscape is further intensified by the presence of regional players like Saskatoon Berries Co. and Avestia Pharma, who target niche markets. As competition continues to increase, companies are expected to invest in sustainability, innovation, and expanding their geographical reach to maintain a competitive edge.
Recent Developments
- In September 2023, Bioriginal Food & Science Corp. completed two significant acquisitions to expand its global footprint in the EU and Asia. The company acquired The Fatory, a Dutch producer of fat and oil-based pet supplements and treats, and Cana Corporation, a distributor of natural health ingredients and products in the Asia Pacific region.
- In January 2022, Cargill announced a joint venture with HELM to build a commercial-scale, renewable BDO facility in the US. While not directly related to GLA, this demonstrates Cargill's commitment to expanding its presence in the bio-industrial space, which could potentially impact their involvement in other natural products like GLA.
Market Concentration and Characteristics
The global Gamma Linolenic Acid (GLA) market is moderately fragmented, with a mix of established multinational corporations and regional players contributing to market dynamics. The market is characterized by the presence of a few key players, such as Cargill and Bioriginal Food & Science Corp., who hold significant market shares due to their extensive distribution networks and strong R&D capabilities. However, regional companies like Saskatoon Berries Co. and Avestia Pharma are also gaining traction, particularly in niche markets and organic segments. The market exhibits a high degree of product differentiation, with companies focusing on organic and sustainable sourcing, quality enhancement, and the development of new applications in dietary supplements, pharmaceuticals, and personal care products. Despite the competition, the market remains open to new entrants, particularly those offering innovative, natural, or organic GLA products, suggesting a dynamic environment with opportunities for growth and expansion.
Report Coverage
The research report offers an in-depth analysis based on Nature, Form, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for natural and organic GLA products is expected to rise, driven by growing consumer preferences for clean-label and sustainable ingredients in dietary supplements and personal care items.
- Ongoing advancements in extraction technologies will enhance the efficiency and cost-effectiveness of GLA production, potentially reducing prices and increasing accessibility to a broader consumer base.
- Emerging markets, particularly in Asia Pacific and Latin America, will see significant growth in GLA consumption due to rising health awareness and increasing disposable incomes.
- The integration of GLA into functional foods and beverages will expand, as consumers seek products that offer additional health benefits beyond basic nutrition.
- The pharmaceutical sector will explore new therapeutic applications for GLA, including its use in managing chronic inflammatory conditions and metabolic disorders, driving further market expansion.
- The trend towards personalized nutrition will lead to increased incorporation of GLA into customized dietary supplements tailored to individual health needs and genetic profiles.
- Stricter regulatory standards and quality controls will shape the market, ensuring higher product safety and efficacy while potentially increasing the barriers to entry for new players.
- There will be a heightened focus on sustainability and ethical sourcing in GLA production, with companies investing in environmentally friendly practices and transparent supply chains.
- The market will experience intensified competition, leading to potential consolidation among key players as they seek to strengthen their market positions through strategic mergers and acquisitions.
- The use of GLA in cosmetics and personal care products will grow, driven by its recognized benefits for skin health and the increasing consumer demand for effective, natural skincare solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the Gamma Linolenic Acid (GLA) market?
What factors are driving the demand for Gamma Linolenic Acid?
Which regions are leading the Gamma Linolenic Acid market?
How is Gamma Linolenic Acid used in personal care products?
Who are the key players in the Gamma Linolenic Acid market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Gamma Linolenic Acid Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Gamma Linolenic Acid Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 172.14 million → forecast year: USD 269.34 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Gamma Linolenic Acid Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Gamma Linolenic Acid Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Gamma Linolenic Acid Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Gamma Linolenic Acid Market Drivers
- 3.3 Gamma Linolenic Acid Market Restraints & Challenges
- 3.4 Gamma Linolenic Acid Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Gamma Linolenic Acid Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Gamma Linolenic Acid Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Gamma Linolenic Acid category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Gamma Linolenic Acid Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Gamma Linolenic Acid Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Gamma Linolenic Acid market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Gamma Linolenic Acid Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Gamma Linolenic Acid Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Gamma Linolenic Acid Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Gamma Linolenic Acid (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Gamma Linolenic Acid Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Gamma Linolenic Acid Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Gamma Linolenic Acid Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Gamma Linolenic Acid Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Gamma Linolenic Acid Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Gamma Linolenic Acid Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Gamma Linolenic Acid Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Gamma Linolenic Acid Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Gamma Linolenic Acid Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
