
Market Overview:
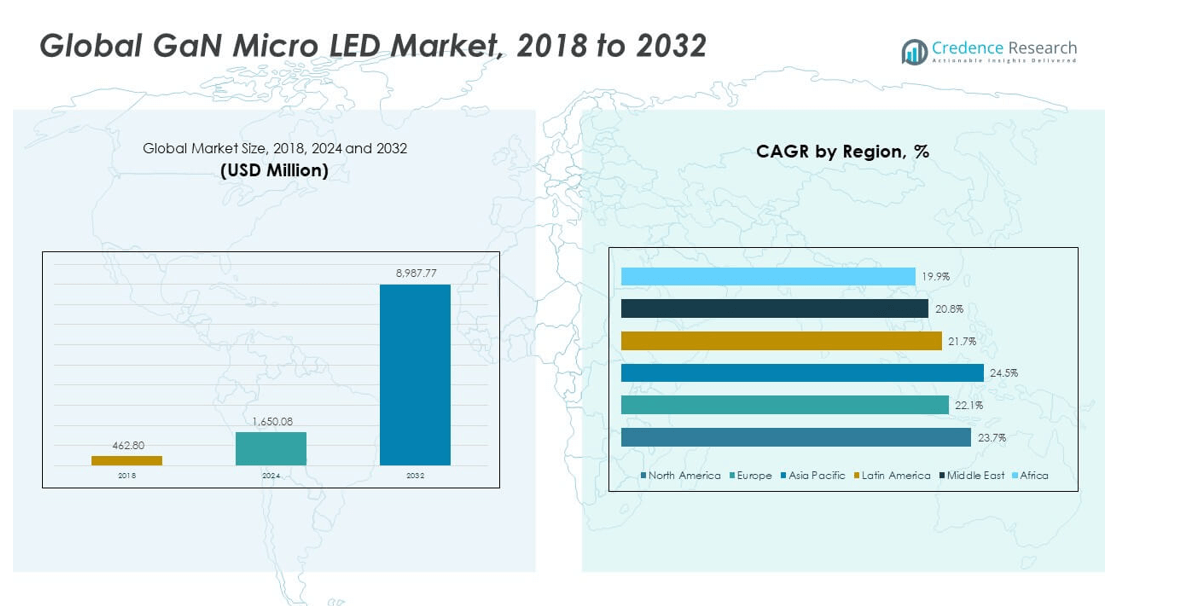
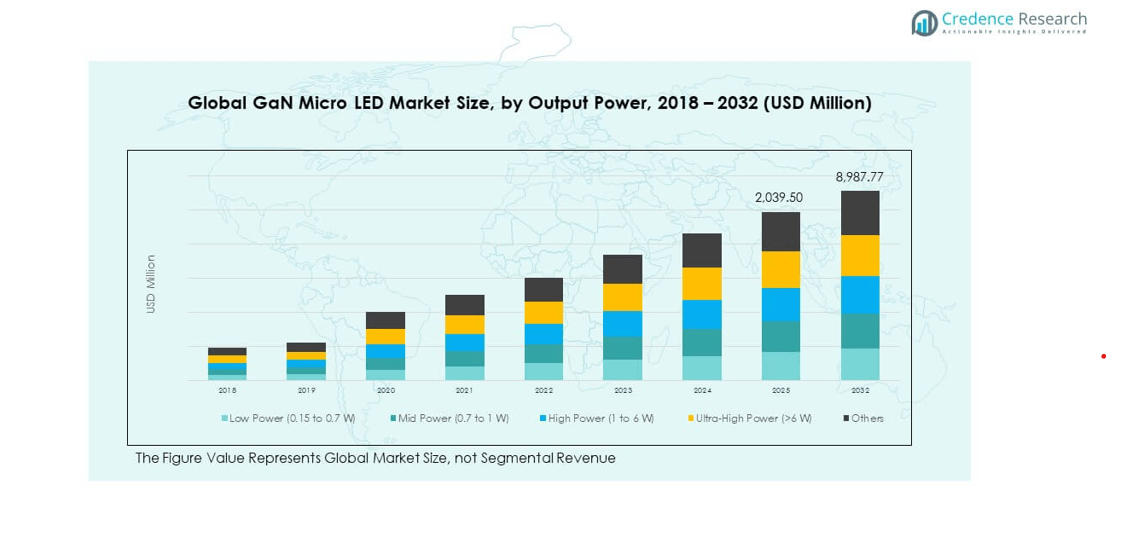
The Global GaN Micro LED Market size was valued at USD 462.80 million in 2018, reaching USD 1,650.08 million in 2024, and is anticipated to attain USD 8,987.77 million by 2032, at a CAGR of 23.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| GaN Micro LED Market Size 2024 | USD 1,650.08 million |
| GaN Micro LED Market, CAGR | 23.60% |
| GaN Micro LED Market Size 2032 | USD 8,987.77 million |
The GaN Micro LED market is driven by the rising demand for high-performance displays offering enhanced brightness, contrast, and energy efficiency. The adoption of gallium nitride technology in consumer electronics, automotive lighting, and wearable devices boosts product innovation. Manufacturers invest heavily in miniaturization and advanced wafer-level packaging to achieve superior pixel density. Growing applications in AR/VR devices and transparent displays further accelerate industry expansion, supported by continuous improvements in production yield and cost efficiency.
Regionally, North America leads the GaN Micro LED market due to strong R&D investments and early technology adoption by major display manufacturers. Asia Pacific is emerging rapidly, driven by large-scale production capabilities in China, Japan, and South Korea, coupled with expanding semiconductor fabrication facilities. Europe follows with increasing focus on energy-efficient lighting and automotive display integration. Meanwhile, developing regions are expected to witness rising adoption as device costs fall and manufacturing partnerships expand across new markets.
Market Insights:
- The Global GaN Micro LED Market size was valued at USD 462.80 million in 2018, USD 1,650.08 million in 2024, and is anticipated to reach USD 8,987.77 million by 2032, growing at a CAGR of 23.6% during the forecast period.
- The top three regions in 2024 are Asia Pacific (45.7%), North America (28.2%), and Europe (17.7%), driven by strong manufacturing ecosystems, technological advancements, and early adoption of micro LED technology.
- Asia Pacific, the fastest-growing region, holds a significant market share, driven by increased manufacturing capacity, government support, and a growing demand for advanced displays in consumer electronics and automotive applications.
- The segment share distribution from the image reveals that Low Power (0.15 to 0.7 W) and Mid Power (0.7 to 1 W) categories dominate the market, capturing the largest share in 2024.
- High Power (1 to 6 W) and Ultra-High Power (>6 W) segments also exhibit strong growth, with Ultra-High Power anticipated to play a critical role in industrial, aerospace, and automotive applications in the coming years.
Market Drivers:
Rising Demand for High-Resolution and Energy-Efficient Display Technologies
The demand for high-resolution and energy-efficient displays fuels growth in the Global GaN Micro LED Market. GaN-based micro LEDs offer higher brightness, better contrast, and lower power consumption compared to OLED and LCD technologies. Manufacturers in consumer electronics and automotive sectors prefer these LEDs for enhanced performance and durability. Strong penetration in smartphones, TVs, and wearable devices increases production capacity worldwide. The technology’s scalability supports both large and small display formats, improving market acceptance. Continuous product innovation strengthens supplier competition. Major display producers invest in new fabrication lines for better yield efficiency. The expanding application base in premium devices drives continuous revenue growth.
- For instance, a developer achieved microdisplays reaching 250,000 nits brightness using GaN‑based microLED chips. Manufacturers in consumer electronics and automotive sectors prefer these LEDs for enhanced performance and durability. Strong penetration in smartphones, TVs, and wearable devices increases production capacity worldwide.
Expanding Applications Across Consumer Electronics and Automotive Displays
The adoption of GaN micro LEDs accelerates across consumer and automotive segments. In the Global GaN Micro LED Market, manufacturers integrate micro LEDs into dashboards, infotainment systems, and head-up displays. Consumer brands deploy them in next-generation televisions, AR/VR devices, and smartwatches. The high brightness and energy efficiency of GaN improve outdoor visibility and device longevity. Electric vehicle manufacturers adopt these LEDs to enhance cockpit displays and lighting aesthetics. High thermal stability ensures performance under variable environmental conditions. Companies focus on flexible and transparent display formats to expand usage. The diversification of applications strengthens long-term demand stability.
- For instance, Nichia Corporation developed a micro‑LED matrix driver driving over 16,000 individual GaN microLEDs for automotive headlamp applications, enabling HDR adaptive lighting. Consumer brands deploy these LEDs in next‑generation televisions, AR/VR devices, and smartwatches.
Technological Advancements in Manufacturing and Wafer-Level Integration
Technological advancements in wafer-scale integration and epitaxy drive process efficiency. The Global GaN Micro LED Market benefits from innovations in chip transfer, yield management, and surface bonding. Wafer-level fabrication reduces defect rates and enhances consistency across pixels. Companies deploy advanced photolithography for submicron pixel structuring. Automated assembly lines improve uniformity in large-scale panels. Strategic collaboration between semiconductor firms and display manufacturers accelerates the development cycle. Miniaturization reduces cost barriers, enabling wider adoption across sectors. Continuous improvement in material quality ensures stable performance under high-luminance conditions.
Growing Investments and Strategic Collaborations Among Key Industry Players
Investment in research and capacity expansion enhances competitive advantage. The Global GaN Micro LED Market experiences strong capital inflow from display manufacturers and technology start-ups. Joint ventures between semiconductor companies and consumer electronics leaders accelerate commercialization. Governments support R&D through funding for energy-efficient technologies. Equipment suppliers develop specialized tools for precise wafer cutting and bonding. Supply chain partnerships streamline component delivery and reduce time-to-market. Cross-industry collaboration fosters innovation in optical design and energy control. The strengthening ecosystem supports the transition from pilot-scale to mass production globally.
Market Trends:
Rapid Commercialization of Micro LED Displays in Consumer Electronics
The consumer electronics sector leads innovation in micro LED commercialization. The Global GaN Micro LED Market sees higher adoption in televisions, tablets, and smartphones due to superior contrast and response time. Display makers enhance performance through smaller pixel sizes and advanced color uniformity. AR and VR devices integrate GaN micro LEDs for immersive visuals and reduced latency. Leading electronics firms launch prototypes with increased efficiency and flexible designs. Product miniaturization expands opportunities in compact wearables and portable displays. The continuous replacement of OLED panels strengthens long-term growth potential. Improved energy efficiency boosts product sustainability appeal.
- For instance, Samsung demonstrated a wearable micro‑LED panel with brightness reaching 6,000 nits and 326 ppi density, using approximately 700,000 microLED chips sized at 30 µm each. Display makers drive performance by reducing pixel pitch to under 0.5 mm and refining color uniformity across ultra‑large screens. AR/VR devices incorporate GaN micro‑LEDs to cut latency and boost immersion.
Adoption of Advanced Manufacturing Automation and Smart Production Lines
Automation transforms the production efficiency of micro LED fabrication. The Global GaN Micro LED Market benefits from robotic assembly, precision alignment systems, and AI-based inspection tools. Automated optical testing ensures pixel uniformity and reduces waste. Smart manufacturing environments integrate data analytics to enhance yield prediction and maintenance scheduling. Process optimization reduces labor costs and production errors. Semiconductor fabs implement real-time feedback systems for quality assurance. Scaling automation supports higher output for mass-market devices. Industry leaders deploy digital twins to simulate performance and optimize production throughput.
- For instance, industry studies note that laser‑based transfer techniques achieve transfer yields up to 99.99% and operating speeds around 100 million LEDs per hour. Robotic systems manage millions of micro‑LED chips with placement accuracy within 1 µm, enabling high‑density panels. Smart manufacturing environments capture real‑time data analytics for yield prediction and maintenance scheduling, reducing defects and downtime.
Integration of Micro LEDs into Automotive and Aerospace Applications
Automotive and aerospace industries embrace micro LEDs for advanced lighting and display solutions. The Global GaN Micro LED Market gains traction through adaptive headlights, digital dashboards, and cabin ambient systems. Aircraft manufacturers explore GaN LEDs for lightweight, high-luminance panels and cockpit instrumentation. Automotive OEMs use them in transparent displays and smart mirrors. Their longer lifespan and thermal resilience improve reliability under dynamic conditions. Integration into infotainment systems enhances visual clarity and energy control. Ongoing developments in flexible displays expand design possibilities for curved surfaces. Growing collaboration between LED manufacturers and vehicle brands reinforces innovation.
Emergence of Flexible and Transparent Micro LED Displays for Future Devices
Flexible and transparent display formats mark a key trend in next-generation electronics. The Global GaN Micro LED Market supports innovations in bendable substrates and transparent panels for wearables and AR applications. Thin-film encapsulation improves device flexibility without compromising performance. Manufacturers focus on low-defect epitaxy to enable seamless display curvature. Transparent micro LEDs open new use cases in smart windows and vehicle windshields. Flexible materials enhance product design freedom for consumer brands. Ongoing R&D reduces production complexity and improves mechanical durability. The convergence of materials science and display engineering accelerates adoption.
Market Challenges Analysis:
High Manufacturing Costs and Complex Production Processes Limiting Scalability
High production cost remains a primary challenge affecting large-scale deployment. The Global GaN Micro LED Market faces difficulties in achieving cost-effective manufacturing due to intricate chip transfer and bonding processes. Yield losses during mass production raise per-unit costs, discouraging early-stage adoption. The requirement for high-precision equipment and controlled cleanroom environments adds further expense. Maintaining pixel uniformity across large panels demands advanced inspection tools and skilled labor. Small production errors cause significant display defects, leading to rework and delays. The capital-intensive nature of fabrication facilities limits participation from small and mid-sized manufacturers. Continuous efforts in automation aim to mitigate these challenges over time.
Limited Supply Chain Integration and Technical Barriers in Mass Adoption
The fragmented supply chain structure slows commercial adoption. The Global GaN Micro LED Market relies on multiple vendors for substrates, epitaxy, and driver ICs, which complicates integration. Technical barriers in wafer-level testing and chip transfer impede large-volume production. Insufficient standardization across component suppliers affects compatibility. Dependence on a limited number of foundries for GaN epitaxy increases supply risks. Delays in material availability affect production cycles. Technology licensing and patent limitations restrict cross-industry collaboration. Strengthening supply chain cooperation and open innovation frameworks can help overcome these obstacles.
Market Opportunities:
Expanding Use in Wearable Electronics and AR/VR Applications Driving Innovation
The miniaturization of devices unlocks new possibilities for micro LED adoption. The Global GaN Micro LED Market finds significant opportunity in wearable devices and AR/VR headsets requiring lightweight, high-brightness displays. Micro LEDs offer superior optical efficiency, extending battery life in compact devices. Companies focus on optimizing color rendering for immersive experiences. Emerging start-ups collaborate with tech giants to develop next-generation optical engines. R&D investments target transparent and curved display modules for wearable form factors. Enhanced design flexibility broadens adoption across lifestyle and professional applications.
Rising Focus on Energy-Efficient Lighting and Sustainable Display Solutions
Growing awareness of energy efficiency supports expansion in sustainable lighting technologies. The Global GaN Micro LED Market aligns with eco-friendly initiatives emphasizing reduced carbon emissions. Industrial and architectural lighting sectors adopt GaN LEDs for longer life and reduced maintenance. Consumer brands promote sustainable electronics integrating recyclable materials and efficient components. Governments introduce incentives for energy-saving display technologies. Investments in renewable energy and smart city infrastructure increase deployment of GaN-based systems. Manufacturers benefit from rising green procurement policies across developed markets.
Market Segmentation Analysis:
By Output Power
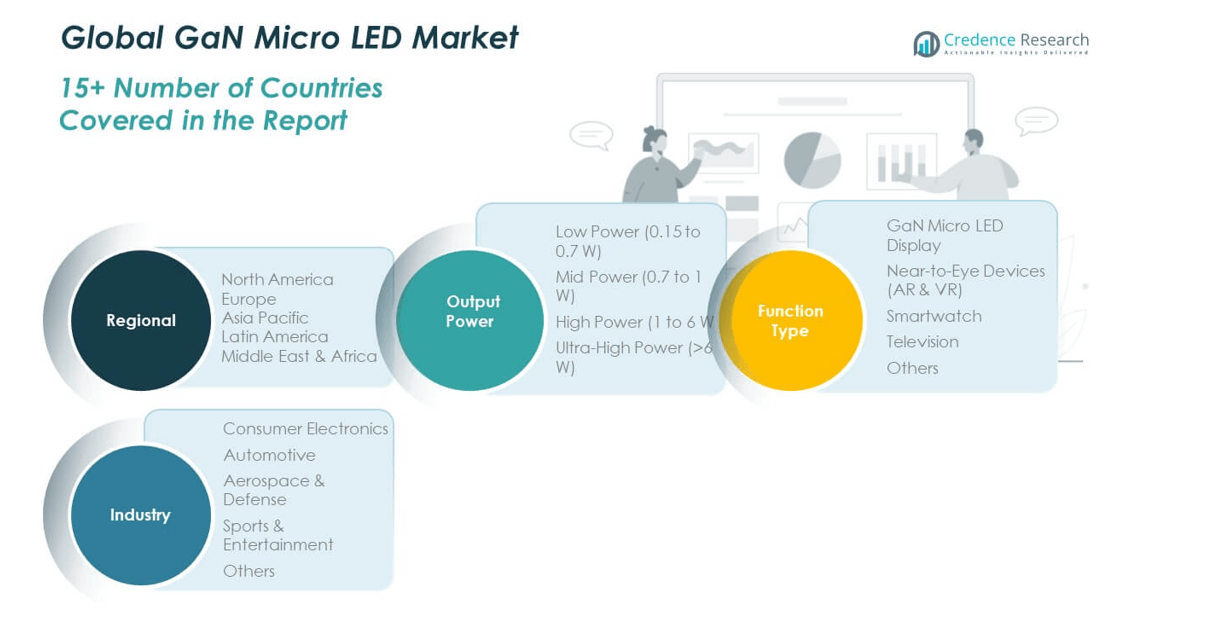
The Global GaN Micro LED Market is segmented by output power into low power, mid power, high power, and ultra-high power categories. Low power LEDs, ranging from 0.15 to 0.7 W, dominate wearable and portable devices due to compact size and low heat emission. Mid power LEDs between 0.7 and 1 W gain traction in smartphones and AR displays for balanced brightness and energy efficiency. High power LEDs from 1 to 6 W serve automotive lighting, outdoor signage, and large displays. Ultra-high power LEDs exceeding 6 W are used in industrial, aerospace, and defense systems demanding high luminance and durability.
- For instance, a team achieved GaN micro‑LED mesa sizes under 20 µm producing >3,000 nits luminance for near‑eye AR systems. High‑power LEDs (1 to 6 W) serve automotive lighting, outdoor signage and large displays; for instance, automotive lighting suppliers introduced modules exceeding 25,000 micro‑LED elements per lamp for adaptive high‑beam systems.
By Function Type
Functional segmentation includes GaN Micro LED displays, near-to-eye devices, smartwatches, televisions, and other emerging applications. Micro LED displays represent the leading function due to superior contrast, long life, and low power use. Near-to-eye devices such as AR and VR headsets show rapid adoption driven by immersive display demand. Smartwatches integrate these LEDs for better outdoor visibility, while televisions increasingly shift toward GaN-based screens for higher resolution and efficiency. Other functions include transparent panels and flexible displays used in smart environments.
- For instance, GaN micro‑LED arrays with pixel size of ~5 µm for AR glasses have been demonstrated, enabling >1,000 ppi resolution. Smartwatches integrate these LEDs for better outdoor visibility.
By Industry
By industry, the market covers consumer electronics, automotive, aerospace and defense, sports and entertainment, and others. Consumer electronics lead with wide adoption in premium devices. The automotive sector invests in advanced displays and adaptive lighting systems. Aerospace and defense use GaN LEDs for rugged, high-intensity illumination. Sports and entertainment industries deploy them in stadiums and broadcast displays, expanding the technology’s reach into dynamic visual applications.
Segmentation:
By Output Power
- Low Power (0.15 to 0.7 W)
- Mid Power (0.7 to 1 W)
- High Power (1 to 6 W)
- Ultra-High Power (>6 W)
By Function Type
- GaN Micro LED Display
- Near-to-Eye Devices (AR & VR)
- Smartwatch
- Television
- Others
By Industry
- Consumer Electronics
- Automotive
- Aerospace & Defense
- Sports & Entertainment
- Others
By Region
- North America
- S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America GaN Micro LED Market size was valued at USD 132.01 million in 2018, reaching USD 463.18 million in 2024, and is anticipated to attain USD 2,533.65 million by 2032, at a CAGR of 23.7% during the forecast period. The region holds around 28.2% share of the global revenue in 2024. The Global GaN Micro LED Market in North America benefits from strong R&D investment, advanced semiconductor infrastructure, and early adoption of display innovations. Leading companies in the U.S. and Canada integrate micro LEDs into premium televisions, AR/VR headsets, and automotive systems. It gains momentum through partnerships between display manufacturers and technology giants. Consumer demand for ultra-high-definition and energy-efficient screens strengthens adoption across entertainment and commercial sectors. The automotive industry incorporates micro LEDs for dashboards and adaptive lighting. Growing investments in pilot production facilities and local supply chains support market expansion. Continuous innovation in fabrication and packaging enhances the region’s competitive edge.
Europe
The Europe GaN Micro LED Market size was valued at USD 86.24 million in 2018, increasing to USD 290.61 million in 2024, and is projected to reach USD 1,439.11 million by 2032, at a CAGR of 22.1% during the forecast period. Europe accounts for nearly 17.7% of the global market in 2024. The Global GaN Micro LED Market in Europe is supported by robust manufacturing standards, sustainability goals, and advancements in automotive lighting systems. Germany, the UK, and France drive industrial adoption through smart display technologies and precision engineering. It experiences strong uptake across automotive, aerospace, and consumer sectors emphasizing eco-friendly production. European firms focus on integrating micro LEDs into high-end consumer displays and digital signage. The region benefits from supportive regulations encouraging low-energy and long-life components. Strategic R&D investments in miniaturization and flexible display formats enhance competitiveness. Collaboration among regional technology institutes and display manufacturers accelerates product commercialization.
Asia Pacific
The Asia Pacific GaN Micro LED Market size was valued at USD 204.20 million in 2018, reaching USD 754.69 million in 2024, and is expected to attain USD 4,359.15 million by 2032, at a CAGR of 24.5% during the forecast period. Asia Pacific commands the largest share of about 45.7% of the global market in 2024. The Global GaN Micro LED Market in this region thrives on large-scale manufacturing capabilities and significant government support for semiconductor production. China, Japan, and South Korea dominate fabrication due to established display industries and strong supply chains. It benefits from heavy investments in mass production and R&D for ultra-thin, high-brightness screens. Local firms expand production to meet demand in AR/VR devices and consumer electronics. Competitive pricing and material innovation reinforce regional dominance. India and Southeast Asia emerge as promising contributors with growing demand for advanced display solutions. Regional players emphasize partnerships and technology transfer to maintain scale and quality.
Latin America
The Latin America GaN Micro LED Market size was valued at USD 21.40 million in 2018, reaching USD 75.32 million in 2024, and is forecast to attain USD 362.09 million by 2032, at a CAGR of 21.7% during the forecast period. Latin America contributes around 4.6% of the global market in 2024. The Global GaN Micro LED Market in Latin America grows steadily, supported by expanding electronics imports and modernization of digital infrastructure. Brazil and Mexico lead demand through consumer electronics and automotive display integration. It benefits from the entry of global manufacturers establishing local distribution networks. Rising awareness of energy-efficient lighting and premium display features supports regional adoption. Governments emphasize technological innovation and digital transformation initiatives. Local assembly operations and reseller networks strengthen accessibility. The entertainment and advertising sectors drive display upgrades in urban centers, enhancing long-term demand.
Middle East
The Middle East GaN Micro LED Market size was valued at USD 12.19 million in 2018, growing to USD 39.50 million in 2024, and is anticipated to reach USD 179.20 million by 2032, at a CAGR of 20.8% during the forecast period. The region holds nearly 2.4% of the global share in 2024. The Global GaN Micro LED Market in the Middle East is influenced by increasing adoption of smart city technologies and digital signage solutions. GCC countries invest in luxury retail, hospitality, and entertainment applications utilizing advanced micro LED displays. It gains traction through infrastructure modernization and growing smart device penetration. Regional partnerships with global suppliers enhance technology accessibility. Automotive and aviation industries deploy micro LEDs for high-performance lighting. Governments encourage diversification into high-tech manufacturing to reduce import dependency. Expanding demand for premium visual systems supports market potential.
Africa
The Africa GaN Micro LED Market size was valued at USD 6.76 million in 2018, rising to USD 26.78 million in 2024, and is projected to attain USD 114.57 million by 2032, at a CAGR of 19.9% during the forecast period. The region represents roughly 1.6% of the global market share in 2024. The Global GaN Micro LED Market in Africa is at an early stage of development but shows promise with growing urbanization and consumer electronics demand. South Africa leads adoption with smart retail displays and commercial lighting projects. It benefits from government incentives promoting energy-efficient technology. The expansion of telecom and entertainment sectors supports gradual penetration of micro LED solutions. Partnerships with international brands aid knowledge transfer and local assembly capabilities. Regional focus on renewable energy aligns with the low-power advantages of GaN LEDs. Rising disposable incomes and digital transformation initiatives strengthen long-term market outlook.
Key Player Analysis:
- Osram Opto Semiconductors
- Cree (now Wolfspeed)
- Sanan Optoelectronics
- Rohinni
- Aledia
- Samsung
- LG Display
- Sony
- Nichia Corporation
Competitive Analysis:
The Global GaN Micro LED Market features a moderately consolidated structure led by major players such as Samsung, Sony, LG Display, Nichia Corporation, Osram Opto Semiconductors, and Cree (Wolfspeed). These companies emphasize R&D investments to enhance brightness, color uniformity, and production yield. It gains competitive intensity through patent-driven innovation and scaling of wafer-level manufacturing. Strategic alliances between semiconductor suppliers and consumer electronics brands accelerate commercialization. Startups like Rohinni and Aledia introduce cost-efficient transfer technologies, strengthening innovation diversity. The focus on premium displays, automotive lighting, and wearable electronics continues to define the competitive landscape.
Recent Developments:
- In October 2025, LG Electronics introduced the LG MAGNIT Active Micro LED, a 136-inch home-cinema display leveraging active-matrix control of micro LEDs with enhanced contrast and ultra-premium positioning.
- In August 2025, Samsung Electronics launched its “Micro RGB” display featuring sub-100-μm red, green and blue micro LEDs behind a 115-inch screen. The new model aims to set a new premium-display standard.
- In February 2024, ams OSRAM revised its micro LED strategy including impairment charges worth EUR 600-900 million following cancellation of a cornerstone micro LED project at its Malaysia facility.
Report Coverage:
The research report offers an in-depth analysis based on Output Power, Function Type, and Industry segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing adoption in AR/VR devices will strengthen demand for ultra-bright, miniaturized LEDs.
- Mass production advancements are expected to reduce manufacturing costs and improve yield.
- Automotive applications will expand, focusing on adaptive lighting and digital displays.
- Transparent and flexible displays will emerge as key innovations for consumer products.
- Collaborations between semiconductor and display manufacturers will accelerate commercialization.
- Energy-efficient technologies will gain importance under global sustainability goals.
- Investments in AI-driven manufacturing automation will enhance production scalability.
- Asia Pacific will continue leading due to strong manufacturing ecosystems and government support.
- Integration in aerospace and defense systems will broaden industrial applications.
- Continuous R&D efforts will shape the transition from pilot-scale to mass-market products.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global GaN Micro LED Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global GaN Micro LED Market projected to grow between 2025 and 2032?
Which Global GaN Micro LED Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global GaN Micro LED Market?
Who are the leading companies in the Global GaN Micro LED Market?
Which region commanded the largest share of the Global GaN Micro LED Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,650.08 million → 2032: USD 8,987.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global GaN Micro LED Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global GaN Micro LED Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global GaN Micro LED Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global GaN Micro LED Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global GaN Micro LED Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global GaN Micro LED Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global GaN Micro LED Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global GaN Micro LED Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,650.08 million → 2032: USD 8,987.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global GaN Micro LED Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global GaN Micro LED Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global GaN Micro LED Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global GaN Micro LED Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

