
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Germany Data Center Renovation Market Size 2024 | USD 1,146.73 million |
| Germany Data Center Renovation Market, CAGR | 14.11% |
| Germany Data Center Renovation Market Size 2032 | USD 3,296.68 million |
Market Overview
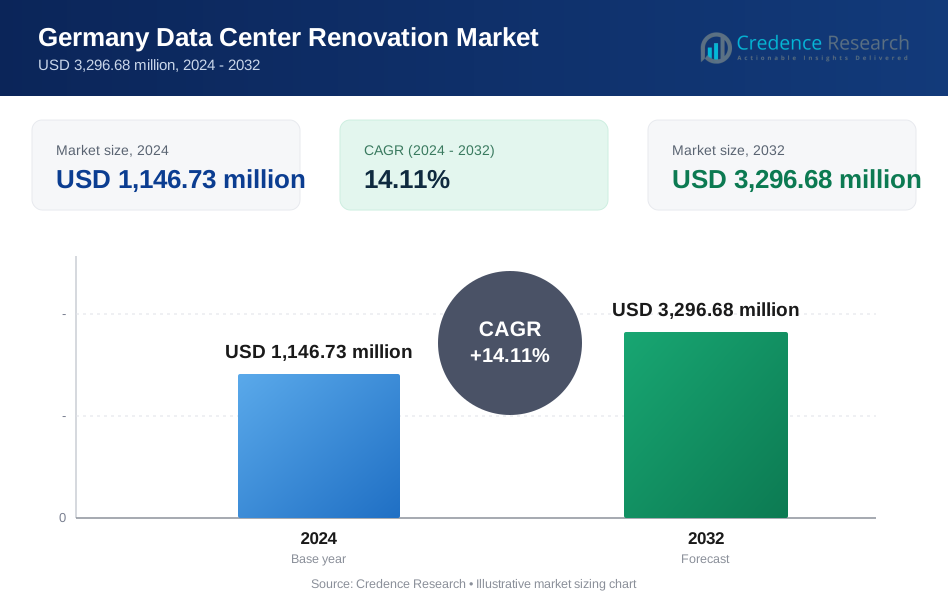
Germany Data Center Renovation market size was valued at USD 1,146.73 million in 2024 and is anticipated to reach USD 3,296.68 million by 2032, at a CAGR of 14.11% during the forecast period (2024-2032).
The Germany data center renovation market is driven by the increasing demand for energy-efficient and sustainable infrastructure, stringent government regulations on carbon emissions, and the growing adoption of advanced cooling and power management solutions. Companies are investing in modernizing existing data centers to enhance operational efficiency, reduce energy consumption, and comply with environmental standards. Additionally, the rise of cloud computing, edge computing, and AI-driven workloads is prompting organizations to upgrade legacy systems to support higher processing capabilities. The trend toward modular and prefabricated data center solutions is gaining traction, offering cost-effective and scalable renovation options. Furthermore, the integration of automation and AI-based monitoring systems is enhancing predictive maintenance and optimizing resource utilization. The need for enhanced cybersecurity measures is also fueling the demand for upgraded IT infrastructure. Overall, the market is experiencing steady growth as businesses prioritize modernization to meet evolving technological and regulatory requirements.
Germany’s data center renovation market is witnessing significant growth across key cities such as Berlin, Frankfurt, Munich, and Hamburg, driven by increasing digitalization, cloud adoption, and the need for energy-efficient infrastructure. These regions serve as critical hubs for data processing and connectivity, attracting substantial investments in modernization efforts. Government initiatives promoting green energy and sustainability further accelerate renovation activities, with companies integrating advanced cooling solutions, AI-driven energy management, and modular designs to enhance efficiency. Key players driving the market include Hewlett Packard Enterprise, Emerson Electric, Eaton, ABB, Honeywell, Cisco Systems, Dell Technologies, Lenovo, Schneider Electric, Microsoft, Siemens, IBM, Google, Vertiv, and Johnson Controls. These companies offer innovative solutions for power management, cooling, security, and automation, supporting the transformation of legacy data centers. As businesses increasingly prioritize scalability, energy efficiency, and security, Germany’s data center renovation market is set to expand, catering to the evolving demands of cloud computing and high-performance IT infrastructure.
Market Insights
- The Germany data center renovation market was valued at USD 1,146.73 million in 2024 and is projected to reach USD 3,296.68 million by 2032, growing at a CAGR of 14.11% from 2024 to 2032.
- Increasing demand for energy-efficient and sustainable data centers is driving renovation activities across key regions.
- Rising adoption of cloud computing, AI-driven automation, and edge computing fuels modernization efforts in data centers.
- Major players such as Hewlett Packard Enterprise, Emerson Electric, Cisco Systems, and Schneider Electric are investing in innovative solutions for power and cooling upgrades.
- High renovation costs and concerns over downtime during infrastructure upgrades pose challenges for market growth.
- Frankfurt, Berlin, Munich, and Hamburg are the leading cities witnessing substantial investments in data center renovation.
- The market is expected to benefit from government initiatives promoting green data center infrastructure and energy efficiency.
Market Drivers
Regulatory Compliance and Cybersecurity Enhancements
Strict data protection regulations and cybersecurity concerns are driving the need for data center renovation in Germany. The General Data Protection Regulation (GDPR) and other national security frameworks require organizations to implement stringent security measures to protect sensitive data. According to a report published by the German Federal Office for Information Security, Germany has been experiencing a significant increase in cyber threats, with the risk of ransomware attacks considered exceptionally high among SMEs, which account for a large part of the German economy. As cyber threats continue to evolve, data centers must be equipped with robust security infrastructure, including advanced firewalls, biometric access controls, and AI-powered threat detection systems. Renovation projects often involve upgrading legacy security protocols, implementing zero-trust architectures, and enhancing disaster recovery capabilities to minimize downtime and mitigate potential cyber risks. Companies are prioritizing infrastructure modernization to ensure compliance with industry regulations while safeguarding critical business data.
Growing Demand for Energy-Efficient and Sustainable Infrastructure
The increasing focus on sustainability and energy efficiency is a major driver of the Germany data center renovation market. As data centers consume vast amounts of power, organizations are under pressure to reduce their carbon footprint and operational costs. Government regulations, such as the European Union’s Green Deal and Germany’s Climate Protection Act, are pushing businesses to adopt energy-efficient solutions, including liquid cooling systems, advanced airflow management, and renewable energy integration. Modernizing existing data centers with energy-efficient technologies not only ensures regulatory compliance but also enhances long-term cost savings. Moreover, the rising adoption of carbon-neutral and green data center initiatives is further accelerating renovation activities across the country.
Rising Adoption of Advanced Technologies and Cloud Computing
The rapid growth of cloud computing, artificial intelligence (AI), and edge computing is prompting organizations to upgrade their legacy data center infrastructure. Businesses are increasingly modernizing their facilities to support high-performance computing and accommodate the rising data processing requirements. Traditional data centers often struggle with scalability and efficiency, leading to higher operational costs and performance limitations. Renovation efforts focus on integrating high-density server racks, advanced networking equipment, and AI-driven monitoring solutions to enhance operational efficiency. Additionally, the increasing shift toward hybrid and multi-cloud environments necessitates infrastructure upgrades to ensure seamless connectivity, data security, and scalability.
Increasing Investments in Modular and Prefabricated Data Centers
The growing adoption of modular and prefabricated data center solutions is fueling the renovation market in Germany. These solutions offer faster deployment, reduced construction costs, and enhanced flexibility compared to traditional data centers. Many businesses are opting to retrofit existing facilities with prefabricated modular components to improve scalability and efficiency. Modular designs allow for phased renovations, minimizing disruptions to ongoing operations while ensuring a seamless transition to modern infrastructure. Additionally, the rising demand for edge data centers to support real-time processing is encouraging companies to upgrade their existing infrastructure with modular configurations. This trend is particularly significant in sectors such as finance, healthcare, and telecommunications, where data processing speed and reliability are critical.
Market Trends
Increasing Focus on Sustainable and Green Data Center Renovation
Sustainability is becoming a central focus in Germany’s data center renovation market, driven by stringent environmental regulations and corporate sustainability goals. Companies are adopting green initiatives such as energy-efficient cooling systems, renewable energy integration, and carbon-neutral operations to reduce their environmental impact. For instance, the German Energy Efficiency Act (EnEfG) mandates that data centers derive an increasing proportion of their electricity consumption from renewable sources and reuse waste heat, feeding it into district heating networks. The shift toward liquid cooling, advanced airflow management, and waste heat recovery systems is gaining traction as businesses seek to improve energy efficiency. Additionally, government incentives and regulations, including Germany’s Climate Protection Act and the European Green Deal, are pushing data centers to modernize their infrastructure to meet strict carbon reduction targets. As sustainability remains a key priority, renovations focused on energy optimization and eco-friendly infrastructure upgrades will continue to rise.
Growing Adoption of AI-Driven Monitoring and Automation
Automation and artificial intelligence (AI) are transforming data center operations, leading to an increased focus on AI-driven monitoring systems and predictive maintenance. Organizations are upgrading their facilities with smart sensors, machine learning algorithms, and AI-powered analytics to optimize resource utilization and prevent downtime. These technologies enable real-time monitoring of power consumption, cooling efficiency, and equipment health, allowing for proactive maintenance and improved operational efficiency. AI-driven automation also enhances security by detecting anomalies and responding to potential cyber threats in real time. As businesses seek to reduce operational costs and improve resilience, AI-powered renovations are becoming an integral part of data center modernization efforts.
Rise in Modular and Prefabricated Data Center Solutions
The demand for modular and prefabricated data center solutions is increasing as businesses prioritize flexibility and scalability in their renovation strategies. Unlike traditional renovations that require extensive construction and downtime, modular solutions offer faster deployment and cost-effective upgrades. Companies are integrating prefabricated cooling units, power distribution systems, and server modules to enhance efficiency while minimizing disruptions to ongoing operations. These solutions are particularly beneficial for businesses expanding their edge computing capabilities, as modular data centers can be deployed closer to end-users for faster processing. As organizations seek more agile and scalable renovation options, the adoption of modular infrastructure is expected to grow significantly.
Strengthening Security Measures Through Infrastructure Upgrades
Cybersecurity threats are becoming more sophisticated, prompting data center operators to invest in enhanced security measures during renovation projects. Organizations are implementing biometric access controls, AI-based threat detection systems, and zero-trust security frameworks to safeguard sensitive data. The need for compliance with strict regulations, such as the General Data Protection Regulation (GDPR), is also driving security-focused upgrades. Additionally, the rise of remote work and cloud-based applications has increased the need for stronger data protection measures within renovated facilities. As cyber risks evolve, data centers are prioritizing security upgrades to ensure resilience against potential threats while maintaining compliance with industry standards.
Market Challenges Analysis
High Capital Investment and Complex Renovation Processes
One of the primary challenges in Germany’s data center renovation market is the high capital investment required for modernization. Upgrading legacy infrastructure with energy-efficient cooling systems, advanced power management, and AI-driven automation involves significant upfront costs. Many businesses, particularly small and medium-sized enterprises (SMEs), struggle to allocate sufficient budgets for large-scale renovations. For instance, data center developers have, in some instances, decided to construct some of the required infrastructure themselves to ensure the necessary and timely power supply, such as building substations on site, installing their own regional power supply lines, or even producing their own electricity. Additionally, integrating new technologies into existing data center frameworks requires careful planning and execution to avoid operational disruptions. Renovation projects often involve complex processes, such as migrating critical workloads, ensuring uninterrupted power supply, and maintaining network security during upgrades. The need for specialized expertise further adds to the cost and complexity, making it challenging for companies to undertake large-scale modernization initiatives.
Regulatory Compliance and Sustainability Constraints
Strict environmental regulations and data security laws pose additional challenges for data center renovation in Germany. Compliance with the General Data Protection Regulation (GDPR), Germany’s Climate Protection Act, and other industry-specific standards requires significant investment in infrastructure upgrades and cybersecurity enhancements. Meeting sustainability targets, such as reducing carbon emissions and improving energy efficiency, often necessitates costly retrofitting of older facilities. Additionally, sourcing eco-friendly materials and renewable energy solutions can be expensive and time-consuming. While government incentives support green data center initiatives, the complexity of compliance and certification processes slows down renovation efforts. Businesses must navigate evolving regulatory frameworks while balancing operational efficiency and cost-effectiveness, making compliance a critical challenge in the data center renovation landscape.
Market Opportunities
Germany’s data center renovation market presents significant opportunities driven by the increasing demand for energy-efficient and sustainable infrastructure. As businesses strive to meet stringent environmental regulations and reduce operational costs, the adoption of advanced cooling systems, renewable energy integration, and carbon-neutral initiatives is accelerating. Government incentives promoting green data centers further encourage companies to invest in sustainable renovations. Additionally, the rise of hyperscale and edge computing is creating opportunities for upgrading legacy data centers with high-density server racks and AI-driven energy management systems. Businesses that embrace these innovations can enhance efficiency, scalability, and long-term cost savings while aligning with Germany’s climate goals.
Another key opportunity lies in the growing adoption of modular and prefabricated data center solutions. These solutions enable faster deployment, reduced capital expenditure, and improved scalability, making them attractive for enterprises looking to upgrade their infrastructure with minimal disruption. The increasing reliance on cloud computing and AI-driven workloads also drives demand for enhanced security and automation, creating opportunities for integrating biometric access controls, AI-powered threat detection, and predictive maintenance systems. Additionally, as businesses shift toward hybrid and multi-cloud environments, the need for seamless connectivity and optimized networking infrastructure continues to grow. Companies that invest in modernizing data centers to meet these evolving technological demands can gain a competitive edge while supporting the digital transformation of Germany’s economy.
Market Segmentation Analysis:
By Renovation Type:
Germany’s data center renovation market is segmented into mechanical, electrical, and infrastructure renovations, each addressing critical aspects of modernization. Mechanical renovation focuses on upgrading cooling systems, airflow management, and HVAC solutions to enhance energy efficiency and operational reliability. As data centers require efficient temperature control to prevent overheating, businesses are investing in advanced cooling technologies such as liquid cooling and free-air cooling systems. Electrical renovation involves upgrading power distribution units (PDUs), backup power solutions, and uninterruptible power supply (UPS) systems to ensure reliability and prevent downtime. The integration of energy-efficient power management solutions is becoming a priority as companies seek to optimize power consumption and reduce operational costs. Infrastructure renovation includes structural enhancements, improved cabling systems, and security upgrades to support higher computing loads and advanced technologies. With the increasing shift toward high-density server configurations and hybrid cloud environments, businesses are investing in robust infrastructure upgrades to enhance scalability, resilience, and security. These renovations are essential to support the growing demand for data processing and storage capabilities.
By Renovation Goal:
The market is also categorized based on renovation goals, including improved energy efficiency, increased capacity and density, and modernization. Improved energy efficiency is a key driver, with businesses focusing on adopting energy-saving technologies such as AI-driven monitoring systems, renewable energy integration, and high-efficiency cooling solutions to meet stringent environmental regulations and reduce operational expenses. Increased capacity and density renovations are gaining traction as data centers need to accommodate rising workloads driven by cloud computing, AI, and edge computing. Companies are upgrading their facilities with high-density racks, efficient cooling mechanisms, and scalable infrastructure to enhance performance and reliability. Modernization and upgrading initiatives are essential for integrating next-generation technologies, strengthening cybersecurity measures, and ensuring compliance with evolving regulatory frameworks. As businesses transition to hybrid and multi-cloud environments, they require infrastructure that supports seamless connectivity, automation, and enhanced security. These renovation goals are shaping the growth of the Germany data center renovation market as companies prioritize efficiency, scalability, and future-proofing their operations.
Segments:
Based on Renovation Type:
- Mechanical Renovation
- Electrical Renovation
- Infrastructure Renovation
Based on Renovation Goal:
- Improved Energy Efficiency
- Increased Capacity and Density
- Modernization and Upgrading
Based on Component:
- Cooling Systems
- Power Systems
- Racks and Enclosures
- Security Systems
Based on Age:
- 0-5 Years
- 6-10 Years
- 11-15 Years
- 16-20 Years
- Over 20 Years
Based on the Geography:
- Berlin
- Munich
- Hamburg
- Frankfurt
Regional Analysis
Berlin
Berlin holds around 24% of the market share, driven by its status as a major technology hub and the presence of numerous enterprises and government institutions. The city is witnessing extensive renovation activities aimed at improving energy efficiency and integrating advanced cooling and power management systems. With Germany’s strong focus on sustainability, data centers in Berlin are adopting renewable energy solutions and AI-driven monitoring technologies to optimize operations and reduce carbon footprints. The growing demand for cloud computing and colocation services further accelerates infrastructure modernization efforts, enabling data centers to enhance scalability, security, and operational efficiency.
Frankfurt
Frankfurt, Germany’s financial hub, also holds approximately 24% of the market share, largely due to the high volume of data traffic facilitated by DE-CIX, one of the world’s largest internet exchange points. The increasing presence of financial institutions, multinational corporations, and cloud service providers has fueled significant renovation investments. Data center operators in Frankfurt are prioritizing infrastructure upgrades focused on cybersecurity, regulatory compliance, and high-performance computing capabilities. Additionally, the rapid adoption of modular and prefabricated data center solutions is gaining momentum, allowing businesses to enhance scalability while minimizing operational disruptions. Sustainability is also a key focus, with growing investments in energy-efficient cooling systems and green power solutions to meet strict environmental regulations and reduce operational costs.
Munich
Munich, a prominent center for technology and innovation, holds around 15% of Germany’s data center renovation market. The city’s strong IT and automotive industries contribute to the rising demand for modernized data centers, particularly for high-performance computing applications. Renovation efforts in Munich emphasize improved energy efficiency, expanded data center capacity, and strengthened security infrastructure. The increasing adoption of AI-driven automation, edge computing, and liquid cooling technologies is further driving modernization efforts. Additionally, the presence of leading research institutions and technology firms is accelerating the demand for advanced IT infrastructure, positioning Munich as a key location for future data center renovations.
Hamburg
Hamburg accounts for approximately 13% of the data center renovation market, fueled by its status as a major logistics and maritime hub. The city’s growing digital economy and demand for real-time data processing are driving investments in upgraded power and cooling systems, as well as enhanced cybersecurity measures. With a strong focus on sustainability, data centers in Hamburg are increasingly integrating renewable energy sources and green data center initiatives to meet carbon reduction goals. The rising adoption of cloud computing and colocation services is also prompting modernization efforts, enabling businesses to enhance operational efficiency and data security. As the demand for cloud-based services grows, Hamburg’s data center renovation market is expected to expand further.
Key Player Analysis
- Hewlett Packard Enterprise
- Emerson Electric
- Eaton
- ABB
- Honeywell
- Cisco Systems
- Dell Technologies
- Lenovo
- Schneider Electric
- Microsoft
- Siemens
- IBM
- Vertiv
- Johnson Controls
Competitive Analysis
The Germany data center renovation market is highly competitive, with key players such as Hewlett Packard Enterprise, Emerson Electric, Eaton, ABB, Honeywell, Cisco Systems, Dell Technologies, Lenovo, Schneider Electric, Microsoft, Siemens, IBM, Google, Vertiv, and Johnson Controls driving innovation and infrastructure upgrades. These companies are focusing on energy-efficient solutions, advanced cooling technologies, and AI-driven automation to enhance data center performance. Leading firms are investing in modular and prefabricated solutions to ensure scalability while minimizing operational disruptions. Additionally, the integration of renewable energy sources and sustainable power management systems is becoming a crucial differentiator among competitors. Strategic partnerships, mergers, and acquisitions are also shaping the market landscape as companies seek to expand their service offerings and market presence. For example, collaborative ventures are enabling firms to combine their expertise, fostering innovation and delivering more comprehensive solutions to clients. With increasing demand for cloud computing, edge data centers, and cybersecurity enhancements, players are continuously upgrading their technologies to maintain a competitive edge. As sustainability and efficiency become key priorities, the market is expected to witness rapid advancements in infrastructure modernization.
Recent Developments
- In December 2024, Microsoft announced the completion of construction on three Azure availability zones in Saudi Arabia, with availability expected in 2026. These zones are part of Microsoft's ongoing investments in the Kingdom, focusing on providing highly secure and globally trusted cloud services to governments and key industries.
- In October 2024, Johnson Controls announced its participation in Data Centre World Asia 2024, where it will showcase its integrated solutions for smarter, safer, and more resilient data center operations. The company aims to highlight its commitment to sustainable infrastructure and advanced technology.
- In October 2024, Dell's founder and CEO, Michael Dell, predicted that data center capacity will need to increase by 100 times over the next 10 years due to the rising demand for AI services.
- In June 2024, Schneider Electric opened a new 105,000-square-foot integration facility in Red Oak, Texas, designed to build pre-engineered and prefabricated IT infrastructure to meet the growing demand for data centers in the U.S. This facility will accelerate the production of integrated modular data center solutions, reducing production costs and expediting delivery.
- In May 2024, Dell Technologies unveiled enhancements to its Dell AI Factory, combining its XE 9680 with direct liquid cooling to support AI workloads. The company also introduced new storage capabilities with PowerStore 4.0, offering greater efficiency and better speeds.
Market Concentration & Characteristics
The Germany data center renovation market exhibits a moderate to high market concentration, with a few dominant players driving innovation and infrastructure upgrades. Companies such as Hewlett Packard Enterprise, Emerson Electric, Cisco Systems, Schneider Electric, and Vertiv hold significant market positions due to their extensive product portfolios, technological expertise, and strong client base. The market is characterized by a strong focus on energy efficiency, modular infrastructure, and AI-driven automation, as data center operators prioritize sustainability and performance optimization. Competitive differentiation is largely based on technological advancements, service reliability, and compliance with stringent environmental regulations. Additionally, strategic collaborations, mergers, and acquisitions are shaping the competitive landscape, allowing companies to expand their market presence. With rising demand for cloud computing, edge computing, and enhanced security infrastructure, the market is witnessing continuous advancements. The presence of both global corporations and specialized regional firms ensures a dynamic competitive environment, fostering ongoing innovation and modernization.
Report Coverage
The research report offers an in-depth analysis based on Renovation Type, Renovation Goal, Component, Age and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Germany data center renovation market is expected to experience significant growth, driven by increasing digitalization and cloud adoption.
- Energy efficiency and sustainability will remain key priorities, with growing investments in green data center initiatives.
- AI-driven automation and predictive maintenance will enhance operational efficiency and reduce downtime.
- Modular and prefabricated data center solutions will gain traction, enabling faster deployment and scalability.
- Edge computing expansion will drive the need for localized data center upgrades and modernization.
- Cybersecurity enhancements will become a major focus, with increased investments in advanced security infrastructure.
- Government regulations and environmental policies will influence renovation strategies, promoting low-carbon technologies.
- The integration of renewable energy sources and liquid cooling systems will continue to shape infrastructure upgrades.
- Strategic partnerships and mergers among key players will strengthen market competitiveness and service offerings.
- Emerging technologies such as quantum computing and 5G networks will drive future data center renovation needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Germany Data Center Renovation market?
What factors are driving the growth of the Germany Data Center Renovation market?
What are some challenges faced by the Germany Data Center Renovation market?
Who are the major players in the Germany Data Center Renovation market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Data Center Renovation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Data Center Renovation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,146.73 million → 2032: USD 3,296.68 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Data Center Renovation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Data Center Renovation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Data Center Renovation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Data Center Renovation Market Drivers
- 3.3 Germany Data Center Renovation Market Restraints & Challenges
- 3.4 Germany Data Center Renovation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Data Center Renovation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Data Center Renovation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Data Center Renovation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Data Center Renovation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Data Center Renovation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Data Center Renovation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Data Center Renovation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Data Center Renovation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Data Center Renovation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Data Center Renovation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Data Center Renovation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Data Center Renovation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Data Center Renovation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Data Center Renovation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Data Center Renovation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Data Center Renovation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Data Center Renovation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Data Center Renovation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Data Center Renovation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
