
Search, Detection and Navigation Instruments Market Overview:
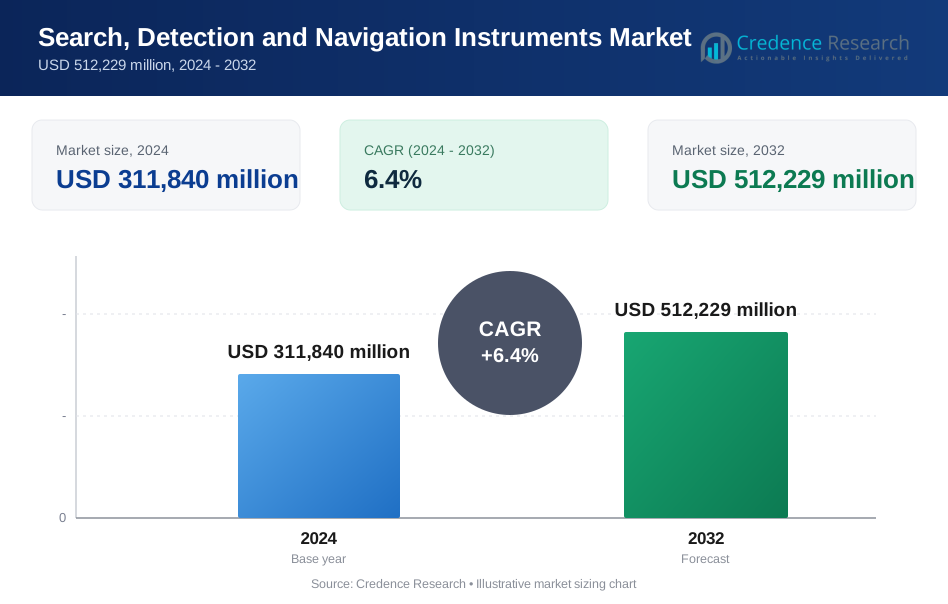
Search, Detection and Navigation Instruments market size was valued at USD 311,840 million in 2024 and is anticipated to reach USD 512,229 million by 2032, at a CAGR of 6.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Search, Detection and Navigation Instruments Market Size 2024 | USD 311,840 million |
| Search, Detection and Navigation Instruments Market, CAGR | 6.4% |
| Search, Detection and Navigation Instruments Market Size 2032 | USD 512,229 million |
Search, Detection and Navigation Instruments Market Insights
- Rising global defense expenditure, modernization of military navigation systems, and increasing investments in homeland security, surveillance, and electronic warfare are major growth drivers, supporting sustained demand for high-precision detection and navigation instruments.
- Technological trends include growing adoption of satellite-based navigation, remote sensing services, real-time kinematic positioning, and integrated multi-sensor systems, while leading players such as BAE Systems, Raytheon, Thales, Leonardo, and Northrop Grumman strengthen competition through R&D and long-term defense contracts.
- High system development costs, complex regulatory requirements, and vulnerabilities related to signal interference and cybersecurity act as key restraints, particularly affecting adoption in cost-sensitive commercial applications.
- North America leads with 38.4% market share, followed by Europe at 26.7% and Asia Pacific at 22.9%, while by segment, aeronautical and space navigation instruments dominate with 38.6% share, supported by aviation growth and defense demand.

Search, Detection and Navigation Instruments Market Segmentation Analysis:
By Type
The Search, Detection and Navigation Instruments market by type is led by Aeronautical and Space Navigation Instruments, which accounted for 38.6% market share in 2024, driven by rising commercial aircraft deliveries, satellite-based navigation upgrades, and increasing defense aviation spending. These instruments are critical for precise positioning, flight management, and safety compliance. Nautical navigation instruments followed with 26.1% share, supported by maritime trade growth and offshore activities. Radio navigational aid apparatus held 22.4% share, benefiting from airport modernization programs, while compasses represented the remaining share, driven mainly by defense and recreational navigation demand.
- For instance, Boeing delivered 528 commercial aircraft in 2023, each equipped with advanced flight management and navigation suites that rely on integrated avionics and inertial reference systems.
By Technology
By technology, Remote Sensing Services dominated the Search, Detection and Navigation Instruments market with a 34.9% share in 2024, supported by strong adoption in defense surveillance, geospatial mapping, and environmental monitoring. Integration of satellite imagery, LiDAR, and radar technologies enhances real-time situational awareness and accuracy. Real Time Kinetic (RTK) technology followed with 21.7% share, driven by precision navigation requirements in aviation, marine surveying, and autonomous systems. RFID- and cellular-based technologies jointly accounted for 28.6% share, benefiting from logistics tracking and smart navigation applications, while Bluetooth and network-based solutions supported short-range positioning use cases.
- For instance, Maxar Technologies supplies high-resolution satellite imagery for U.S. defense and intelligence customers, supporting mission planning and broad-area surveillance.
By Application
The Military application segment dominated the Search, Detection and Navigation Instruments market, capturing 41.3% market share in 2024, driven by sustained investments in defense modernization, electronic warfare, and advanced navigation systems for air, land, and naval forces. Aviation held 29.5% share, supported by air traffic growth, fleet upgrades, and stringent navigation safety standards. Marine applications accounted for 18.2% share, benefiting from port digitization, naval fleet expansion, and offshore energy operations. Other applications, including land surveying and autonomous navigation, contributed the remaining share, supported by smart infrastructure and unmanned system deployments.
Key Growth Drivers
Rising Defense and Homeland Security Expenditure
Growing global defense budgets remain a primary growth driver for the Search, Detection and Navigation Instruments market. Governments are prioritizing modernization of surveillance, reconnaissance, and navigation systems to enhance situational awareness and national security. Increased investments in radar systems, inertial navigation, electronic warfare, and satellite-based navigation technologies are strengthening demand across air, land, and naval forces. Border security upgrades, maritime domain awareness initiatives, and counter-terrorism programs further accelerate adoption. Additionally, rising geopolitical tensions and asymmetric warfare threats are pushing armed forces to deploy advanced navigation and detection instruments with higher accuracy, resilience, and interoperability, supporting sustained market expansion across military and defense applications.
- For instance, NATO members have been increasing spending toward the 2% of GDP guideline, channeling funds into integrated air and missile defense systems, upgraded C4ISR networks, and secure navigation capabilities.
Growth in Aviation and Maritime Transportation
Expanding global air traffic and maritime trade are significantly driving demand for advanced navigation and detection instruments. Airlines are investing in next-generation flight management and navigation systems to improve safety, fuel efficiency, and regulatory compliance. Similarly, growth in commercial shipping, offshore energy exploration, and port digitization is boosting adoption of nautical navigation instruments and radio navigational aids. Modern vessels increasingly rely on integrated navigation suites for collision avoidance, route optimization, and real-time tracking. These developments, combined with stricter international safety standards, are reinforcing the need for precise and reliable navigation technologies across aviation and marine sectors.
- For instance, Wärtsilä and Kongsberg supply integrated bridge systems combining ECDIS, radar, autopilot, and AIS to support safe navigation on large cargo and offshore vessels.
Technological Advancements and System Integration
Rapid technological innovation is accelerating market growth by enhancing performance, accuracy, and reliability of navigation and detection systems. Advancements in satellite navigation, remote sensing, real-time kinematic positioning, and sensor fusion are enabling precise positioning even in challenging environments. Integration of navigation instruments with digital platforms, analytics software, and autonomous systems is further expanding application scope. Defense, aviation, and marine operators increasingly prefer integrated, multi-sensor solutions that reduce operational complexity and improve decision-making. Continuous R&D investments and system upgrades are therefore strengthening long-term demand across both commercial and defense end-users.
Key Trends & Opportunities
Adoption of Advanced Satellite-Based and Remote Sensing Technologies
A key trend shaping the Search, Detection and Navigation Instruments market is the growing adoption of satellite-based navigation and remote sensing technologies. Enhanced GNSS systems, Earth observation satellites, and sensor-rich platforms are improving navigation accuracy, coverage, and resilience. These technologies support critical applications such as military surveillance, aviation navigation, maritime monitoring, and environmental assessment. Opportunities are expanding in multi-constellation GNSS receivers and hybrid navigation systems that combine satellite data with inertial and terrestrial inputs. This trend is creating strong growth prospects for manufacturers offering high-precision, interference-resistant navigation solutions.
- For instance, Europe’s Galileo, the U.S. GPS, Russia’s GLONASS, and China’s BeiDou constellations now provide multi-constellation, multi-frequency signals that enable centimeter-level positioning when combined with augmentation services.
Expansion of Autonomous and Smart Navigation Applications
The increasing deployment of autonomous systems represents a major opportunity for the market. Unmanned aerial vehicles, autonomous ships, and smart defense platforms require highly accurate and reliable navigation and detection instruments. Integration of navigation systems with artificial intelligence, machine learning, and real-time communication networks is enabling autonomous decision-making and route optimization. Civil infrastructure projects, smart ports, and intelligent transportation systems are also driving adoption. As autonomy becomes central to defense and commercial operations, demand for advanced navigation instruments with real-time positioning and redundancy capabilities is expected to rise steadily.
- For instance, the U.S. Navy’s Sea Hunter unmanned surface vessel relies on advanced sensors, collision-avoidance systems, and autonomous navigation software to operate over long ranges without onboard crew.
Key Challenges
High Development and Deployment Costs
High costs associated with the development, testing, and deployment of advanced navigation and detection instruments remain a significant challenge. Sophisticated systems require substantial investments in R&D, specialized components, and compliance with stringent regulatory and defense standards. For smaller operators and emerging economies, high acquisition and maintenance costs can limit adoption. Additionally, upgrading legacy systems to modern integrated platforms involves complex retrofitting and operational downtime. These cost pressures can slow procurement cycles and restrict market penetration, particularly in price-sensitive commercial applications.
Signal Interference and Cybersecurity Risks
Signal vulnerability and cybersecurity threats pose critical challenges to the Search, Detection and Navigation Instruments market. Navigation systems are increasingly exposed to jamming, spoofing, and cyberattacks, particularly in defense and aviation environments. Dependence on satellite signals makes systems susceptible to disruptions caused by natural events or hostile actions. Ensuring signal integrity, resilience, and secure data transmission requires continuous technological upgrades and protective measures. Addressing these risks adds complexity and cost, compelling manufacturers and end-users to invest heavily in robust, secure, and redundant navigation solutions.
Regional Analysis
North America
North America dominated the Search, Detection and Navigation Instruments market with a 38.4% market share in 2024, driven by strong defense spending, advanced aerospace manufacturing, and early adoption of next-generation navigation technologies. The United States accounts for the majority of regional demand due to large-scale investments in military modernization, satellite navigation systems, and homeland security infrastructure. High deployment of advanced avionics, unmanned systems, and integrated navigation platforms across defense and commercial aviation further supports growth. Presence of major technology providers and continuous R&D investments reinforce North America’s leadership in high-precision detection and navigation solutions.
Europe
Europe accounted for 26.7% market share in 2024, supported by robust aerospace and defense industries, maritime trade activity, and regional security initiatives. Countries such as the UK, France, Germany, and Italy are investing heavily in modern navigation instruments for military, aviation, and naval applications. Growth is further supported by fleet upgrades, air traffic management modernization, and adoption of satellite-based navigation under regional space programs. Increasing focus on border surveillance and maritime safety enhances demand for advanced detection and navigation instruments across both defense and commercial sectors.
Asia Pacific
Asia Pacific captured 22.9% market share in 2024 and represents the fastest-growing regional market, driven by rising defense budgets, expanding aviation infrastructure, and increasing maritime trade. China, India, Japan, and South Korea are investing significantly in military navigation systems, satellite programs, and airport modernization projects. Rapid growth in commercial shipping and offshore activities is boosting demand for nautical navigation instruments. Additionally, regional focus on indigenous defense manufacturing and smart transportation systems is accelerating adoption of advanced detection and navigation technologies across diverse applications.
Latin America
Latin America held 6.1% market share in 2024, supported by gradual modernization of defense systems and growth in commercial aviation and maritime activities. Countries such as Brazil and Mexico are investing in airport upgrades, naval fleet enhancement, and border security infrastructure. Increasing adoption of navigation instruments in offshore energy exploration and port operations further supports market growth. However, budget constraints and slower technology adoption compared to developed regions limit rapid expansion. Despite this, ongoing infrastructure development and regional security initiatives continue to create steady demand for navigation and detection solutions.
Middle East & Africa
The Middle East & Africa region accounted for 5.9% market share in 2024, driven primarily by defense modernization programs and strategic investments in surveillance and navigation systems. Gulf countries are deploying advanced detection and navigation instruments to strengthen military capabilities, border security, and maritime surveillance. Growth is also supported by expanding aviation hubs and port infrastructure development. In Africa, demand remains moderate but is gradually increasing with investments in aviation safety and maritime monitoring. High reliance on imports and limited local manufacturing remain key constraints across the region.
Search, Detection and Navigation Instruments Market Segmentations:
By Type
- Compasses
- Aeronautical and Space Navigation Instruments
- Nautical Navigation Instruments
- Radio Navigational Aid Apparatus
By Technology
- Radio Frequency Identification based (RFID)
- Cellular
- Network
- Bluetooth
- Remote Sensing Services
- Real Time Kinetic
- Other Technologies
By Application
- Marine
- Aviation
- Military
- Other Applications
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Search, Detection and Navigation Instruments market is characterized by the presence of established global defense, aerospace, and technology companies competing on precision, reliability, and system integration capabilities. Leading players such as BAE Systems PLC, Raytheon, Thales Group, Leonardo S.p.A, Northrop Grumman Corporation, and Elbit Systems Ltd. dominate the market through strong defense contracts, advanced navigation portfolios, and continuous R&D investments. Companies including Honeywell International Inc., Garmin International Inc., Moog Inc., Smiths, and Ultra Electronics Holdings PLC focus on avionics, marine navigation, and high-accuracy positioning systems for both commercial and military applications. Market competition is driven by innovation in satellite navigation, remote sensing, and multi-sensor integration, along with long-term government procurement programs. Strategic partnerships, technology upgrades, and expansion into autonomous and smart navigation solutions remain key competitive strategies across the market.
Key Player Analysis
- Thales Group
- Garmin International Inc.
- Northrop Grumman Corporation
- Elbit Systems Ltd.
- Honeywell International Inc.
- Leonardo S.p.A
- Smiths
- Moog Inc.
- Raytheon
- BAE Systems PLC
Recent Developments
- In October 2025, SPARC AI Inc. launched the ATLAS module within its Overwatch platform, a new breakthrough for GPS-denied target acquisition, autonomous navigation technology, and enhanced mission planning and situational awareness.
- In October 2025, Maxar Intelligence rebranded to Vantor and Lanteris as part of a strategic repositioning in spatial intelligence; alongside the rebrand, the company launched Tensorglobe, an AI-powered spatial intelligence platform that integrates sensor and navigation data into a comprehensive 3D Earth model.
- In March 2025, the UAE’s Mohammed bin Rashid Space Centre, in partnership with Satrec Initiative, launched the Etihad-SAT radar-imaging Earth observation satellite, enhancing maritime navigation support, environmental monitoring, and detection capabilities under varied conditions.
Report Coverage
The research report offers an in-depth analysis based on Type, Technology, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Search, Detection and Navigation Instruments market will continue to expand driven by sustained defense modernization and security investments worldwide.
- Adoption of advanced satellite-based navigation and multi-constellation GNSS systems will improve accuracy and operational resilience.
- Integration of remote sensing, inertial navigation, and sensor fusion technologies will enhance real-time situational awareness.
- Demand from aviation will rise with fleet modernization, air traffic growth, and stricter navigation safety regulations.
- Maritime navigation systems will gain traction due to port digitization, offshore energy activities, and naval fleet upgrades.
- Military applications will remain the largest revenue contributor supported by electronic warfare and surveillance requirements.
- Growth of autonomous platforms will increase demand for high-precision and redundant navigation instruments.
- Manufacturers will focus on cybersecurity, anti-jamming, and spoofing-resistant solutions to protect navigation signals.
- Strategic partnerships and long-term government contracts will shape competitive positioning and technology development.
- Emerging economies will offer new opportunities through infrastructure development and expanding defense capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Search, Detection and Navigation Instruments market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Search, Detection and Navigation Instruments market projected to grow between 2024 and 2032?
Which Search, Detection and Navigation Instruments market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Search, Detection and Navigation Instruments market?
Who are the leading companies in the Search, Detection and Navigation Instruments market?
Which region commanded the largest share of the Search, Detection and Navigation Instruments market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Search, Detection and Navigation Instruments Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Search, Detection and Navigation Instruments Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 311,840 million → 2032: USD 512,229 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Search, Detection and Navigation Instruments Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Search, Detection and Navigation Instruments Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Search, Detection and Navigation Instruments Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Search, Detection and Navigation Instruments Market Drivers
- 3.3 Search, Detection and Navigation Instruments Market Restraints & Challenges
- 3.4 Search, Detection and Navigation Instruments Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Search, Detection and Navigation Instruments Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Search, Detection and Navigation Instruments Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Search, Detection and Navigation Instruments category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Search, Detection and Navigation Instruments Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Search, Detection and Navigation Instruments Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Search, Detection and Navigation Instruments market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Search, Detection and Navigation Instruments Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Search, Detection and Navigation Instruments Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Search, Detection and Navigation Instruments Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Search, Detection and Navigation Instruments (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Search, Detection and Navigation Instruments Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Search, Detection and Navigation Instruments Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Search, Detection and Navigation Instruments Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Search, Detection and Navigation Instruments Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Search, Detection and Navigation Instruments Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Search, Detection and Navigation Instruments Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Search, Detection and Navigation Instruments Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Search, Detection and Navigation Instruments Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Search, Detection and Navigation Instruments Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
