
Market Overview:
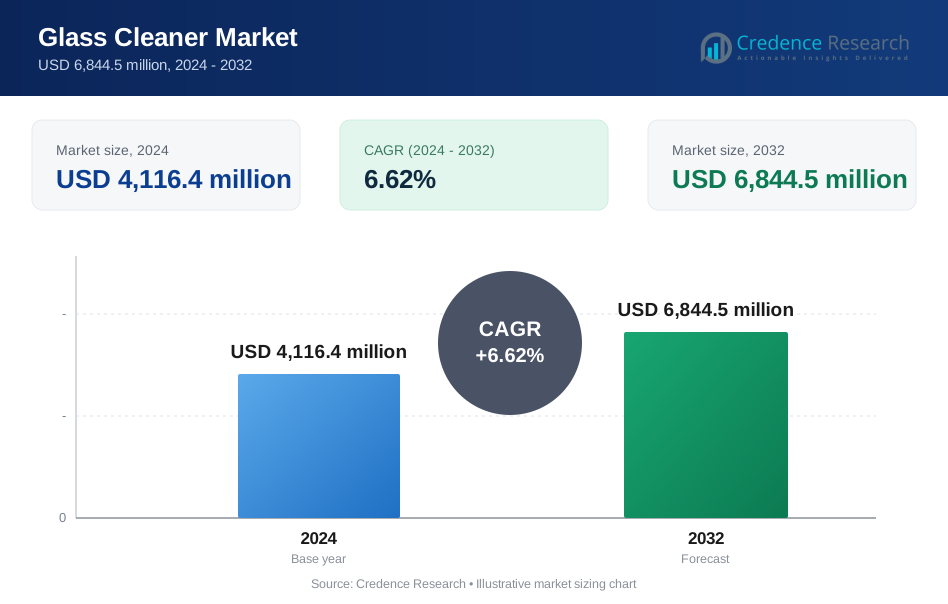
The Global Glass Cleaner Market size was valued at USD 2,926.6 million in 2018 to USD 4,116.4 million in 2024 and is anticipated to reach USD 6,844.5 million by 2032, at a CAGR of 6.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Glass Cleaner Market Size 2024 | USD 4,116.4 million |
| Glass Cleaner Market, CAGR | 6.62% |
| Glass Cleaner Market Size 2032 | USD 6,844.5 million |
The market is propelled by increased demand for hygiene maintenance across homes, offices, and commercial spaces. Growing awareness around cleanliness, health, and aesthetics fuels regular use of glass cleaners. Product innovations such as streak-free formulations, plant-based ingredients, and multi-surface compatibility are expanding consumer appeal. Commercial institutions, including malls, airports, and hospitals, continue driving large-volume consumption. Packaging innovation, such as ergonomic spray bottles and refill pouches, improves user convenience and reduces wastage. Retailers promote eco-certified variants to meet rising sustainability expectations. Manufacturers also focus on value-tier and premium segments to capture diverse buyers. E-commerce supports recurring household purchases through auto-delivery models.
Asia Pacific leads the market due to rapid urbanization, increasing disposable income, and widespread use of glass in buildings. North America and Europe show steady growth supported by high awareness, mature retail networks, and demand for sustainable products. Latin America and the Middle East are emerging, driven by commercial real estate expansion and evolving hygiene practices. Africa represents early-stage demand growth, supported by urban development and rising household income. Product availability through offline and online channels continues to expand market penetration across all regions.

Market Insights:
- The Global Glass Cleaner Market was valued at USD 2,926.6 million in 2018, reached USD 4,116.4 million in 2024, and is projected to hit USD 6,844.5 million by 2032, growing at a CAGR of 6.62%.
- Asia Pacific led with 37.8% market share in 2024, followed by Europe at 23.9%, and North America at 18.5%, driven by high urban density, mature retail networks, and consistent demand for hygiene products.
- The Middle East is the fastest-growing region with a CAGR of 7.1%, supported by expanding commercial infrastructure, rising disposable income, and institutional demand.
- In 2024, the residential segment accounted for approximately 58% of the Global Glass Cleaner Market, with strong recurring demand from households across both emerging and developed economies.
- The commercial segment represented about 42% of the market in 2024, supported by facility management operations across retail, healthcare, airports, and hospitality sectors.
Market Drivers
Rising Demand for Surface Hygiene Across Residential and Commercial Buildings
Consumers prioritize visible cleanliness in homes, offices, and public buildings. The shift toward aesthetic interiors with large glass windows and facades supports regular cleaning cycles. Hospitality and retail facilities depend on spotless glass surfaces to enhance guest experience. The Global Glass Cleaner Market benefits from consistent demand across sectors that require visual appeal. Urban living has increased the number of high-rise buildings using glass extensively. Frequent usage of elevators, partitions, and display panels with glass creates daily cleaning needs. Institutional buyers invest in bulk purchases for routine facility maintenance. Product availability in both traditional and modern retail channels drives consistent sales.
- For instance, 3M's Glass Cleaner with Scotchgard Protection dries faster than other tested cleaners and provides a protective barrier after repeated use that removes fingerprints and smudges more effectively than leading competitors, as verified in 3M's product testing.
Increased Product Development in Eco-Friendly and Non-Toxic Cleaning Formulations
Manufacturers develop glass cleaners with fewer harmful chemicals to meet environmental and health concerns. These products gain traction among consumers with children or respiratory sensitivities. Brands introduce plant-based, alcohol-free, or biodegradable variants without compromising performance. The Global Glass Cleaner Market supports this innovation trend through growing demand for sustainable solutions. Eco-labeled products gain shelf visibility and brand trust in regulated markets. Governments push for safer formulations through regulatory policies and green certifications. End users prefer fragrance-free or naturally scented cleaners with low VOC emissions. The shift aligns product development with rising environmental and wellness values.
- For instance, SC Johnson's Windex line features trigger spray bottles with precision nozzles that minimize overspray and support targeted application for spot cleaning, as detailed in their product specifications for user convenience.
Growing Urbanization Driving Higher Consumption of Glass Cleaning Products
Expanding urban populations increase the density of infrastructure using glass in interior and exterior design. High-rise buildings and commercial plazas use wide glass panels, doors, and partitions. Regular cleaning is necessary to preserve transparency, aesthetics, and hygiene. The Global Glass Cleaner Market gains momentum with large-scale urban development in Asia, the Middle East, and Latin America. The proliferation of shopping malls, airports, and hospitals with glass architecture raises product usage. Cleaning service providers rely on high-efficiency solutions to meet demand from large contracts. Product range expansion supports small and large area applications. Demand remains strong across professional and household users.
Increased Focus on Efficient Packaging and User-Friendly Dispensing Mechanisms
Consumers value ease of use and packaging that supports safe and quick application. Trigger sprays, foam tops, and refill pouches become more common. These features enhance control and reduce wastage, especially in residential use. The Global Glass Cleaner Market shows strong adoption of ergonomic packaging in competitive segments. Commercial buyers also favor formats that simplify cleaning routines. Brands invest in leak-proof, recyclable packaging to address cost and sustainability goals. Innovative formats help smaller brands gain traction in mature markets. Packaging differentiation influences buyer preferences at both retail and institutional levels.
Market Trends
Adoption of Smart Cleaning Tools Integrated with Glass Cleaner Applications
The industry witnesses rising integration of glass cleaners with robotic and automated cleaning devices. Smart window-cleaning robots use specialized formulations for stain-free operation. These systems support cleaning in tall buildings and hard-to-reach surfaces. The Global Glass Cleaner Market adapts to this demand with compatibility-based solutions. Industrial and high-rise facility managers seek time-efficient tools to reduce labor. Brands partner with automation vendors to develop robot-ready sprays and cartridges. Urban cities lead the use of robotic tools in commercial settings. Future product lines are expected to be customized for sensor-driven equipment.
- For instance, Ecovacs WINBOT X provides 50 minutes of continuous cleaning on a single charge for high-rise glass surfaces using its four-stage microfiber and squeegee system.
Rising Influence of E-Commerce Platforms and Subscription-Based Refill Services
E-commerce expands access to a broader product range with detailed comparisons and reviews. Consumers explore new brands offering eco or performance-based value. The Global Glass Cleaner Market benefits from direct-to-consumer sales channels and bundled offers. Subscription services for monthly or quarterly refills gain attention in urban homes. Users seek convenience with auto-delivery, especially for daily-use household items. Platforms promote new packaging formats like concentrated sachets or pods. Brand loyalty grows through digital engagement and customer retention programs. Smaller companies use online-only models to bypass traditional retail barriers.
- For instance, Blueland's glass cleaner tablets create one 24 oz bottle per tablet through their direct-to-consumer subscription platform.
Growing Popularity of Fragrance-Infused and Multi-Surface Cleaning Products
Consumers seek glass cleaners with dual benefits such as pleasant aroma and multi-surface usability. Products that clean mirrors, tiles, and appliances besides glass surfaces attract interest. The Global Glass Cleaner Market responds to this trend with multipurpose variants. Formulations include essential oils, floral scents, or citrus extracts to enhance appeal. Scented products dominate the household segment, especially in premium categories. Commercial buyers show interest in neutral-scent or odorless options to meet workplace standards. Fragrance innovation supports brand differentiation in crowded markets. Packaging often highlights the dual functionality and fragrance appeal.
Sustainability and Circular Economy Principles in Product Design and Branding
Brands move toward sustainable manufacturing and packaging practices to meet evolving buyer expectations. Post-consumer recycled plastic and biodegradable labels gain market traction. The Global Glass Cleaner Market increasingly reflects circular economy values. Consumers favor brands with transparent supply chains and sustainability claims. Refill stations and concentrate packs reduce plastic waste in urban centers. Companies incorporate carbon-reduction strategies into product positioning. Regional brands gain relevance by aligning with local recycling infrastructure. Sustainability labels now influence purchasing decisions in both developed and developing regions.

Market Challenges Analysis
Price Competition from Unorganized Players and Store Brands in Price-Sensitive Markets
The Global Glass Cleaner Market faces intense competition from local, unbranded, or store-brand products. These options often undercut premium offerings by focusing on basic cleaning utility. Price-sensitive consumers in emerging economies prefer lower-cost alternatives with minimal packaging. This trend reduces margins for established brands and limits premium adoption. Private labels from large retailers gain share by leveraging shelf access and price control. It faces difficulty in differentiating products where performance parity is perceived. Small brands adopt aggressive pricing strategies to acquire volume. Market fragmentation slows brand consolidation in mid-income regions.
Logistical and Regulatory Challenges in Hazardous Ingredient Handling and Cross-Border Trade
Compliance with safety, labeling, and transportation rules creates friction in global supply chains. Some ingredients used in glass cleaners fall under restricted chemical lists in key markets. The Global Glass Cleaner Market must align with evolving rules around VOC limits and environmental safety. Delays in customs clearance, changes in packaging mandates, and safety certifications increase cost. Regulatory divergence between countries complicates multi-region launches. Smaller exporters struggle to adapt to frequent compliance updates. Product recalls due to non-compliance harm brand reputation. Complex logistics in developing regions also limit efficient product delivery.
Market Opportunities
Expansion Potential in Underserved Rural and Tier-2 Urban Clusters Globally
Untapped markets in rural zones and smaller cities present growth scope for organized players. Awareness campaigns, affordability innovations, and retail partnerships can drive penetration. The Global Glass Cleaner Market can grow through sachet packaging, regional languages, and co-branded promotions. Rural infrastructure and urban spillover contribute to new demand pockets. Brands that localize distribution and reduce costs can expand share in these segments.
Product Innovation with Bio-Based Formulations and Concentrated Refill Formats
Companies can lead by introducing plant-based or bioenzyme formulas that support safe usage and sustainability. It can also benefit from water-efficient formats like concentrated drops or refillable sprays. Demand rises for green-certified and child-safe variants. Urban professionals value space-saving, multi-use packaging. Competitive advantage lies in merging efficacy with eco-value.
Market Segmentation Analysis:
By Type
Liquid glass cleaners dominate due to their broad usage in households and institutions. Their ease of application and compatibility with various surfaces make them the first choice. Spray glass cleaners follow closely, favored for precision and convenience in daily cleaning tasks. Foam variants gain traction in commercial settings where controlled spread and reduced dripping matter. Powder glass cleaners serve niche industrial users but face limited consumer adoption.
- For instance, Method's glass cleaner uses Powergreen® technology in 28 oz spray bottles designed to adhere effectively to vertical glass surfaces. The plant-based formula supports streak-free cleaning and aligns with eco-conscious consumer preferences in the U.S. and European markets.
By Distribution Channel
The offline segment holds a significant share driven by supermarket chains, hardware stores, and institutional suppliers. Physical retail enables consumers to compare brands and access instant purchases. The Global Glass Cleaner Market also shows steady growth in the online segment. E-commerce offers easy availability, subscription refills, and product variety. Emerging brands use digital channels to bypass traditional distribution, expanding reach across regions.
- For instance, Colin glass cleaners distributed in 500 ml trigger spray bottles across Indian hardware stores.
By End Use
The residential segment accounts for the bulk of product consumption due to daily cleaning needs in homes and apartments. Rising urbanization and glass-heavy home designs push steady demand. It also sees sustained use in the commercial segment, especially across malls, hospitals, airports, and office buildings. Facility managers require consistent supply of large-volume cleaners to maintain aesthetics and hygiene. The commercial end-use drives innovation in performance and packaging efficiency.
Segmentation:
By Type
- Liquid Glass Cleaner
- Spray Glass Cleaner
- Foam Glass Cleaner
- Powder Glass Cleaner
By Distribution Channel
- Offline
- Online
By End Use
- Residential
- Commercial
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Regional Analysis:
North America
The North America Global Glass Cleaner Market size was valued at USD 553.13 million in 2018 to USD 762.48 million in 2024 and is anticipated to reach USD 1,233.38 million by 2032, at a CAGR of 6.3% during the forecast period. North America accounted for approximately 18.5% of the global market in 2024. It is driven by widespread adoption of glass-based architecture in residential and commercial properties. High consumer awareness around hygiene supports recurring purchases. Leading brands dominate retail shelves across supermarkets and hypermarkets. Institutional buyers in sectors like healthcare, education, and hospitality maintain bulk procurement. The region also benefits from early adoption of eco-friendly and non-toxic formulations. Online channels continue gaining traction due to ease of subscription and delivery. Regulatory support for sustainable cleaning solutions further accelerates market maturity.
Europe
The Europe Global Glass Cleaner Market size was valued at USD 705.90 million in 2018 to USD 986.88 million in 2024 and is anticipated to reach USD 1,627.62 million by 2032, at a CAGR of 6.5% during the forecast period. Europe represented 23.9% of the global market share in 2024. It is shaped by strong environmental regulations and a high preference for green-certified products. Countries like Germany, the UK, and France lead in volume and innovation. Retailers actively promote concentrated, refillable, and biodegradable variants. The market favors brands with clear sustainability credentials and safety testing. Demand remains high in institutional and commercial cleaning services. Cross-border e-commerce enhances accessibility for niche and premium offerings. Product formulation and labeling must align with EU chemical directives.
Asia Pacific
The Asia Pacific Global Glass Cleaner Market size was valued at USD 1,098.95 million in 2018 to USD 1,555.41 million in 2024 and is anticipated to reach USD 2,607.75 million by 2032, at a CAGR of 6.7% during the forecast period. Asia Pacific held 37.8% of the global market share in 2024, making it the largest regional segment. It is propelled by rapid urban development and expanding middle-class consumer base. Rising construction of malls, airports, and residential towers fuels demand. China, India, Japan, and Southeast Asia are key contributors. Organized retail and online channels enable wide product reach. Demand spans both low-cost and premium glass cleaners. Local brands compete on price while global players push innovation. Shifting focus toward eco-conscious packaging is shaping future product strategies.
Latin America
The Latin America Global Glass Cleaner Market size was valued at USD 315.49 million in 2018 to USD 447.81 million in 2024 and is anticipated to reach USD 753.58 million by 2032, at a CAGR of 6.8% during the forecast period. Latin America comprised 10.9% of the global market in 2024. It is driven by growth in commercial construction, hospitality, and urban housing sectors. Brazil and Mexico remain key consumption centers. The retail sector supports product availability across tier-1 and tier-2 cities. Consumer preference leans toward affordable and multipurpose formulations. Informal markets still play a role, but organized players are expanding presence. Awareness around hygiene continues rising post-pandemic. Brands leverage local partnerships to improve distribution efficiency and visibility.
Middle East
The Middle East Global Glass Cleaner Market size was valued at USD 198.43 million in 2018 to USD 287.03 million in 2024 and is anticipated to reach USD 494.86 million by 2032, at a CAGR of 7.1% during the forecast period. The region accounted for 7.0% of the global market in 2024. It is supported by demand from commercial buildings, luxury hotels, and high-rise residential properties. GCC countries, particularly the UAE and Saudi Arabia, lead in consumption. Institutional cleaning contracts dominate bulk usage. It also sees growing residential use as awareness and disposable income improve. Import reliance shapes brand availability in retail. Sustainable product variants gain attention in premium segments. E-commerce and direct-to-home models are expanding across urban centers.
Africa
The Africa Global Glass Cleaner Market size was valued at USD 54.73 million in 2018 to USD 76.80 million in 2024 and is anticipated to reach USD 127.31 million by 2032, at a CAGR of 6.6% during the forecast period. Africa represented 1.9% of the global market share in 2024. It is at an early growth stage, with demand concentrated in South Africa, Egypt, and Nigeria. Urbanization and rising health awareness support uptake of branded cleaners. Informal players dominate rural markets, while organized retail grows in cities. The market favors affordable SKUs and small packs. Infrastructure growth and commercial construction increase institutional demand. Brands invest in awareness and distribution through partnerships. Opportunities remain strong in expanding regional access and product education.
Key Player Analysis:
- PPG Industries, Inc.
- 3M
- The Clorox Company
- Reckitt Benckiser
- Stoner Inc
- Zep Inc
- ITW Global Brands Inc
- Diversey Inc
- Weiman Products LLC
- Other Key Players
Competitive Analysis:
The Global Glass Cleaner Market features a mix of multinational corporations and regional brands competing across pricing, innovation, and distribution. It is led by companies such as 3M, The Clorox Company, Reckitt Benckiser, PPG Industries, and Zep Inc. These players maintain strong retail presence, broad product portfolios, and established supply chains. Private labels and local manufacturers intensify competition in cost-sensitive markets by offering value-driven options. Product differentiation relies on eco-friendly ingredients, packaging design, and multi-surface compatibility. Mergers, acquisitions, and new product launches shape the strategic landscape. Market leaders invest in R&D, marketing, and sustainability to retain brand loyalty and meet evolving consumer demands. E-commerce and D2C channels create space for emerging players to scale quickly. Competitive intensity remains high due to low switching costs and broad product availability across offline and online formats. Brands focus on balancing performance, price, and safety to gain share in a fragmented environment.
Recent Developments:
- In January 2026, SC Johnsoncontinues to advance its commitment to a circular economy, having met its 2025 goal to make 100% of its plastic packaging recyclable, reusable, or compostable. The company has successfully integrated 25% post-consumer recycled (PCR) materials across its product lines, including its flagship Windex glass cleaner, representing a significant increase in recycled content since 2018.
Report Coverage:
The research report offers an in-depth analysis based on Type, Distribution Channel, End Use, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise with growing urban construction and widespread use of glass in modern architecture.
- Eco-friendly and biodegradable formulations will gain traction across retail and institutional channels.
- Liquid and spray glass cleaners will continue dominating due to broad application and consumer familiarity.
- E-commerce and D2C models will expand reach, especially in Asia Pacific and Latin America.
- Smart packaging and concentrated refills will support brand differentiation and reduce logistics cost.
- Commercial and industrial end users will drive bulk demand, especially in the hospitality and healthcare sectors.
- Regional brands will expand share in price-sensitive markets through localized offerings.
- Market entry barriers will remain low, increasing competition from private labels and new entrants.
- Product safety, VOC compliance, and sustainability certifications will influence purchasing behavior.
- The market will evolve with automated cleaning tools, requiring compatible glass cleaning formulations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Glass Cleaner Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Glass Cleaner Market projected to grow between 2024 and 2032?
Which Global Glass Cleaner Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Glass Cleaner Market?
Who are the leading companies in the Global Glass Cleaner Market?
Which region commanded the largest share of the Global Glass Cleaner Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,116.4 million → 2032: USD 6,844.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Glass Cleaner Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Glass Cleaner Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Glass Cleaner Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Glass Cleaner Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Glass Cleaner Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Glass Cleaner Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Glass Cleaner Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Glass Cleaner Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,116.4 million → 2032: USD 6,844.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Glass Cleaner Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Glass Cleaner Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Glass Cleaner Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Glass Cleaner Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

