
Market Overview
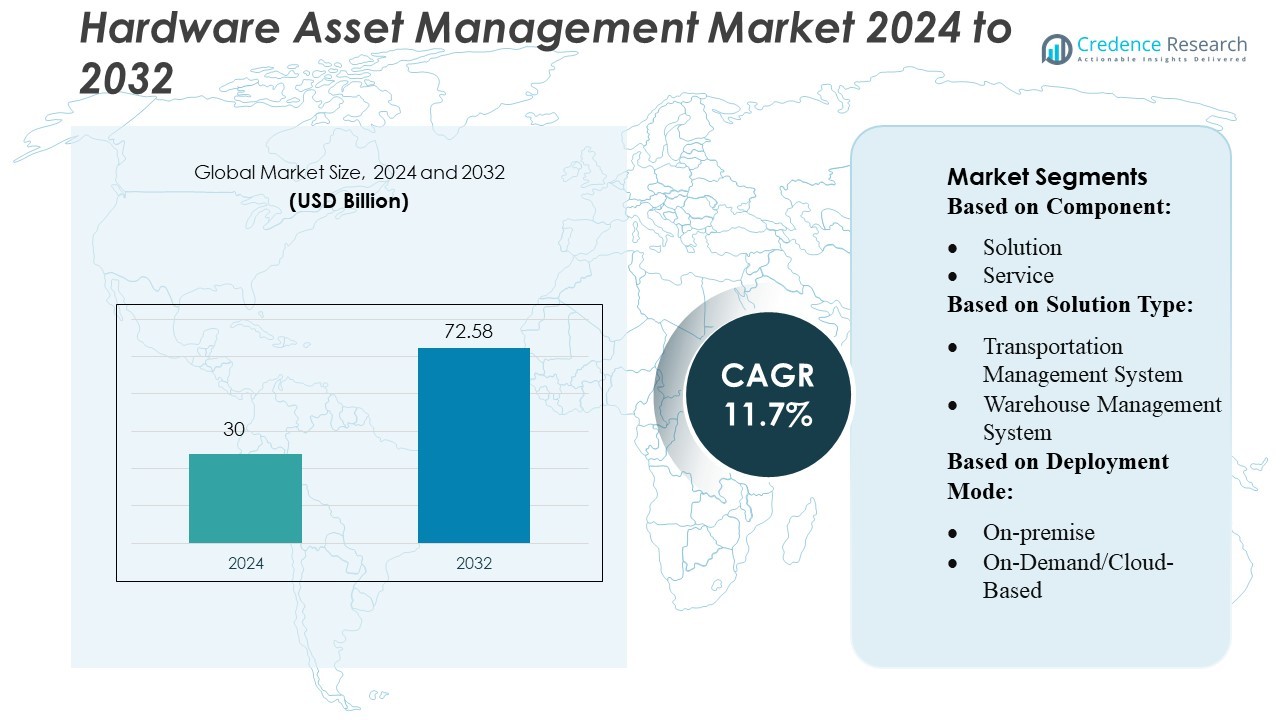
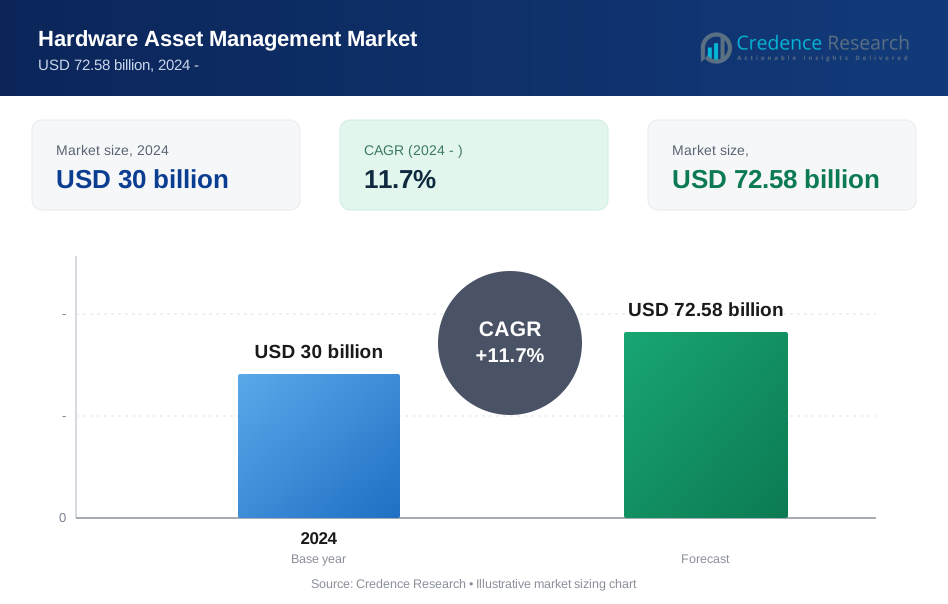
Hardware Asset Management Market size was valued USD 30 billion in 2024 and is anticipated to reach USD 72.58 billion by 2032, at a CAGR of 11.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hardware Asset Management Market Size 2024 | USD 30 Billion |
| Hardware Asset Management Market, CAGR | 11.7% |
| Hardware Asset Management Market Size 2032 | USD 72.58 Billion |
The hardware asset management market is shaped by strong competition among major global technology providers that offer advanced lifecycle tracking, cloud-based platforms, and AI-driven analytics. Leading players continuously enhance their solutions with integrated IoT capabilities, predictive maintenance tools, and automated compliance features to support large, distributed enterprise environments. The market’s growth is further supported by strategic partnerships, product expansions, and industry-specific implementations across manufacturing, energy, IT services, and government sectors. North America leads the global hardware asset management market with an estimated 35–38% share, driven by mature digital infrastructure, high cloud adoption, and strong regulatory compliance requirements across enterprises.
Market Insights
- The Hardware Asset Management Market was valued at USD 30 billion in 2024 and is projected to reach USD 72.58 billion by 2032, registering a strong CAGR of 11.7% during the forecast period.
- Growing demand for real-time asset visibility, automated lifecycle tracking, and cloud-enabled management platforms is driving adoption across large enterprises, particularly in asset-intensive sectors.
- AI-driven analytics, IoT-integrated monitoring, and predictive maintenance are emerging as key market trends, improving operational accuracy and reducing downtime.
- The market remains highly competitive as vendors invest in product innovation, strategic collaborations, and industry-specific solutions, while integration complexity and high deployment costs act as notable restraints.
- North America leads with a 35–38% share, supported by advanced digital infrastructure; the solution segment dominates with the largest share, driven by rising enterprise demand for centralized, scalable asset intelligence systems.
Market Segmentation Analysis:
By Component
The hardware asset management market remains dominated by the solution segment, accounting for the largest market share due to growing enterprise demand for automated tracking, lifecycle management, and compliance auditing. Organizations increasingly prioritize integrated platforms that consolidate asset visibility, reduce operational risk, and enhance ROI. The service segment continues to grow steadily, driven by rising outsourcing of maintenance, configuration, and system optimization tasks. However, solutions hold the lead as enterprises favor scalable, AI-enabled asset intelligence tools that streamline inventory accuracy and reduce downtime across distributed IT and operational environments.
- For instance, Bentley Systems’ AssetWise ALIM enables users to link over 1 million engineering documents and asset records within its connected data environment. By consolidating this wealth of information, organizations reduce operational risk and improve ROI.
By Solution Type
Within solution types, the Warehouse Management System (WMS) segment holds the dominant share, supported by its critical role in real-time inventory tracking, equipment utilization monitoring, and automated data capture. WMS adoption accelerates across manufacturing, logistics, and retail due to rising pressure for faster inventory turns and reduced operational inefficiencies. Transportation Management Systems and Supply Chain Planning follow, driven by the need for synchronized logistics and predictive planning. Procurement and sourcing tools gain traction through spend optimization, while Manufacturing Execution Systems expand with Industry 4.0-driven connectivity and factory-floor asset control.
- For instance, Oracle’s Fusion Cloud Warehouse Management (23C) supports serial-number tracking of up to 25 alphanumeric characters per item, ensuring precise tracking of individual units.
By Deployment Mode
The on-demand/cloud-based segment leads the market with the highest share, propelled by its scalability, lower upfront investment, and seamless integration with multi-site operations. Cloud platforms enable organizations to centralize asset tracking, automate updates, and leverage advanced analytics without complex infrastructure demands. This model also supports rapid deployment and remote access, making it suitable for distributed workforces and global enterprises. While on-premise solutions retain significance among highly regulated sectors seeking greater data control, cloud-based systems dominate due to enhanced flexibility, cost efficiency, and continual innovation through AI, IoT, and automated reporting capabilities.
Key Growth Drivers
- Rising Demand for Real-Time Asset Visibility and Tracking
Organizations increasingly invest in hardware asset management solutions to gain real-time visibility into asset utilization, location, and lifecycle performance. Growing device proliferation across IT, telecom, manufacturing, and logistics intensifies the need for automated tracking systems that reduce downtime, prevent asset loss, and optimize resource allocation. Advanced technologies such as RFID, IoT sensors, and AI-driven analytics further accelerate adoption by enabling continuous monitoring, predictive maintenance, and accurate inventory mapping—significantly improving operational efficiency and cost savings across large, distributed enterprises.
- For instance, ABB’s AC500 CMS module supports up to 16 condition-monitoring sensors per module, enabling continuous tracking of vibration, temperature, and signal data to detect faults before they escalate.
- Expanding Digital Transformation and Cloud Adoption
Accelerated digital transformation initiatives across industries are driving higher investments in centralized asset management platforms that support cloud-based deployment. Enterprises adopt cloud-native solutions to streamline asset data consolidation, automate updates, and scale operations without heavy infrastructure costs. The shift toward hybrid and remote work environments further emphasizes the need for unified asset intelligence systems. As organizations modernize their IT infrastructure, cloud-enabled hardware asset management tools provide enhanced accessibility, integration capabilities, and real-time analytics—positioning them as core components of digital modernization strategies.
- For instance, SAP Asset & Service Manager app empowers more than 500 technicians with persona-based, offline-capable workflows and voice-to-text, camera, and LiDAR scanning functionality.
- Increasing Compliance Requirements and IT Governance Mandates
Growing regulatory and security requirements compel enterprises to implement structured hardware asset management practices that ensure audit readiness, data integrity, and risk mitigation. Industries such as BFSI, healthcare, and government face stringent compliance obligations related to asset ownership, software licensing, data protection, and lifecycle documentation. Automated asset tracking helps organizations maintain accurate audit trails, eliminate unauthorized devices, and reduce vulnerabilities linked to outdated hardware. The rising importance of governance frameworks and cybersecurity resilience continues to strengthen demand for disciplined asset management systems.
Key Trends & Opportunities
1. Integration of AI, Automation, and Predictive Analytics
AI-driven automation is emerging as a major trend, transforming the hardware asset management landscape through predictive analytics, anomaly detection, and automated reconciliation. Organizations increasingly utilize machine learning models to forecast asset failures, optimize refresh cycles, and analyze usage patterns. Automated workflows reduce manual effort and enhance data accuracy, creating opportunities for vendors to develop intelligent asset ecosystems. These advancements also support strategic decision-making, improve lifecycle planning, and unlock new service models that appeal to enterprises seeking next-generation operational optimization.
- For instance, Hexagon AB recently introduced its HxGN APM, which embeds an Asset Twin Library comprising over 200 predefined industrial asset models, covering 1,761 failure modes, 3,928 condition triggers, and 1,375 prescriptive actions.
2. Growing Adoption of IoT-Enabled Asset Ecosystems
IoT integration presents significant opportunity as enterprises deploy sensor-equipped hardware to track environmental conditions, performance metrics, and movement patterns. IoT-enabled ecosystems provide granular insights that enhance asset traceability and maintenance efficiency across warehouses, data centers, and industrial facilities. This trend drives demand for interoperable platforms capable of aggregating vast real-time data streams. As businesses embrace Industry 4.0 and smart infrastructure initiatives, IoT connectivity enables end-to-end asset intelligence, supporting predictive operations and strengthening cross-functional decision-making.
- For instance, GE Digital’s SmartSignal software includes a “time-to-action” forecast analytics model built on over 340 Digital Twin blueprints, enabling users to predict when a piece of equipment will hit alarm thresholds and require remediation.
3. Rising Opportunities in Multi-Site and Remote Workforce Management
The expansion of remote and hybrid work models creates new opportunities for hardware asset management providers. Enterprises face increased complexity in monitoring distributed devices, ensuring secure configurations, and maintaining visibility across geographically dispersed teams. Cloud platforms, automated audit tools, and remote provisioning systems allow organizations to strengthen governance while reducing operational overhead. As multi-site operations expand across global supply chains, solutions supporting remote onboarding, asset delivery tracking, and centralized lifecycle management gain strong market traction.
Key Challenges
- High Implementation Costs and System Complexity
Despite strong demand, many organizations—especially SMEs—face challenges due to the high cost of deploying advanced hardware asset management platforms. Integration with legacy systems, customization needs, and infrastructure upgrades contribute to substantial upfront investment. Additionally, complex IT environments require skilled personnel to manage configuration, data migration, and training. These factors can slow adoption and reduce ROI in the early stages. Vendors must address cost barriers through modular solutions, flexible pricing models, and simplified deployment frameworks.
- Data Accuracy Issues and Integration Limitations
Achieving accurate, unified asset data remains a major challenge due to inconsistent tracking practices, siloed systems, and manual data entry. Inadequate integration between hardware asset management tools and existing IT service management (ITSM), ERP, and procurement platforms leads to duplicated records and incomplete inventories. These issues undermine operational visibility and compliance. Organizations require seamless interoperability and standardized data models to maintain accurate lifecycle information. Vendors that provide robust APIs, automated discovery tools, and real-time synchronization can help overcome these limitations and strengthen.
Regional Analysis
North America
North America holds the largest share of the hardware asset management market at approximately 35–38%, driven by early technology adoption, strong IT governance frameworks, and high demand for automated asset lifecycle solutions. Enterprises across sectors such as BFSI, telecom, and healthcare invest heavily in cloud-based asset intelligence tools to meet compliance and cybersecurity requirements. The region benefits from advanced digital infrastructure, widespread IoT integration, and strong vendor presence, enabling organizations to optimize asset utilization and reduce operational risk. Growing emphasis on remote workforce management further accelerates adoption across mid- and large-scale enterprises.
Europe
Europe accounts for around 25–28% of the global market, supported by stringent regulatory requirements, growing digitalization initiatives, and the rapid expansion of asset-intensive industries. Countries such as Germany, the U.K., and France lead adoption, driven by the need for centralized tracking, audit readiness, and enhanced lifecycle governance. The region’s focus on data protection, sustainability reporting, and IT standardization boosts the demand for automated asset inventory systems. Increasing investments in Industry 4.0, IoT-enabled operations, and cloud transformation continue to strengthen market penetration across manufacturing, automotive, and public sector organizations.
Asia-Pacific
Asia-Pacific represents approximately 22–25% of the market and stands as the fastest-growing region, propelled by rapid industrialization, expanding digital infrastructure, and rising technology investments across China, India, Japan, and Southeast Asia. Enterprises in manufacturing, logistics, and IT services increasingly adopt asset management solutions to enhance operational visibility and support large-scale device deployments. Government-backed digital transformation programs and the proliferation of cloud services further accelerate adoption. As regional businesses modernize their operations and embrace IoT-enabled asset ecosystems, Asia-Pacific is expected to sharply increase its global market share over the forecast period.
Latin America
Latin America captures around 6–8% of the hardware asset management market, with growth driven by increasing digital adoption, modernization of enterprise IT infrastructure, and rising demand for cost-efficient asset tracking solutions. Countries such as Brazil, Mexico, and Chile lead the market, supported by expanding telecom networks and improvements in industrial operations. Organizations focus on reducing asset-related losses and improving budget planning through automated lifecycle monitoring. Although adoption is slower due to economic constraints and limited IT modernization in some regions, growing cloud adoption and digital workforce expansion present strong long-term opportunities.
Middle East & Africa
The Middle East & Africa region holds approximately 4–6% market share, supported by digital transformation initiatives, smart city projects, and rising IT investments across the GCC nations. Organizations in energy, utilities, and government increasingly deploy hardware asset management tools to improve asset utilization and enhance operational transparency. Cloud migration and the expansion of managed service models also contribute to adoption. While some African markets face infrastructure limitations, improved connectivity and enterprise modernization efforts are gradually driving interest. The region’s growing focus on cybersecurity and regulatory compliance will further strengthen market uptake.
Market Segmentations:
By Component:
- Solution
- Service
By Solution Type:
- Transportation Management System
- Warehouse Management System
By Deployment Mode:
- On-premise
- On-Demand/Cloud-Based
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the hardware asset management market features a strong mix of global technology leaders and specialized solution providers, including Bentley Systems, Incorporated; Oracle; ABB; AssetWorks, Inc.; SAP SE; Hexagon AB; General Electric Company; Hitachi, Ltd.; Honeywell International Inc.; and International Business Machines Corporation. the hardware asset management market remains highly dynamic, shaped by rapid technological innovation, increasing digital transformation, and expanding enterprise demand for automated asset lifecycle solutions. Vendors compete by enhancing platform capabilities through AI-driven analytics, IoT integration, and cloud-native architectures that provide real-time visibility, predictive maintenance, and improved compliance tracking. The market also benefits from rising adoption of remote workforce support tools and scalable asset intelligence systems tailored for complex, multi-site operations. Companies strengthen their market presence through strategic partnerships, product enhancements, and industry-specific solutions, creating an environment of continuous innovation and intensifying competition across global industries.
Key Player Analysis
- Bentley Systems, Incorporated
- Oracle
- ABB
- AssetWorks, Inc.
- SAP SE
- Hexagon AB
- General Electric Company
- Hitachi, Ltd.
- Honeywell International Inc.
- International Business Machines Corporation
Recent Developments
- In June 2024, International Business Machines Corporation and Telefónica Tech, a digital transformation company, announced a new collaboration agreement to advance the deployment of analytics, AI, and data governance solutions, addressing the constantly evolving needs of enterprises.
- In April 2024, Rockwell Automation, Inc. announced plans to showcase its collaboration with Ericsson through a demonstration of Plex Asset Performance Management (APM) at the Hannover Messe 2024 trade fair. The system, powered by industrial private 5G connectivity, facilitates real-time decision-making and the management of emerging assets, such as Autonomous Mobile Robots (AMRs).
- In March 2024, Cloudera, Inc. unveiled enhancements to its open data lakehouse on the private cloud, aimed at transforming on-premises data capabilities for scalable analytics and AI with enhanced trust. The latest updates would make Cloudera, Inc.
- In March 2024, Adobe Inc. launched a new set of suites aimed at the enterprise sector, enabling brands to achieve individualized personalization on a large scale by leveraging generative AI and instantaneous insights.
Report Coverage
The research report offers an in-depth analysis based on Component, Solution Type, Deployment Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will increasingly adopt AI-driven automation to enhance predictive maintenance and lifecycle optimization.
- Cloud-based asset management platforms will continue to gain dominance due to scalability and lower infrastructure dependency.
- IoT-enabled asset ecosystems will expand, improving real-time tracking and operational visibility across industries.
- Integration with IT service management and ERP systems will strengthen to support unified asset governance.
- Remote and hybrid workforce growth will drive demand for centralized, remotely accessible asset management tools.
- Cybersecurity-focused asset monitoring will become a critical priority for regulated industries.
- Digital twins will be used more widely to simulate asset performance and optimize replacement cycles.
- Industry 4.0 adoption will accelerate investment in automated hardware monitoring across manufacturing and logistics.
- Vendors will focus on modular and customizable platforms to support diverse enterprise requirements.
- Emerging markets will witness rising adoption as digital infrastructure and cloud readiness continue to improve.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Hardware Asset Management Market, and what is its projected size in 2032?
At what Compound USD 72.58 billion by 2032.Annual Growth Rate is the Hardware Asset Management Market projected to grow between 2025 and 2032?
Which Hardware Asset Management Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hardware Asset Management Market?
Who are the leading companies in the Hardware Asset Management Market?
Which region commanded the largest share of the Hardware Asset Management Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hardware Asset Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hardware Asset Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 30 billion → forecast year: USD 72.58 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hardware Asset Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hardware Asset Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hardware Asset Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hardware Asset Management Market Drivers
- 3.3 Hardware Asset Management Market Restraints & Challenges
- 3.4 Hardware Asset Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hardware Asset Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hardware Asset Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hardware Asset Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hardware Asset Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Hardware Asset Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Hardware Asset Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hardware Asset Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hardware Asset Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Hardware Asset Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hardware Asset Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Hardware Asset Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hardware Asset Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Hardware Asset Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hardware Asset Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hardware Asset Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hardware Asset Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hardware Asset Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hardware Asset Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hardware Asset Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
