
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Heat Transfer Fluid (HTF) Market Size 2024 | USD 8509.8 million |
| Heat Transfer Fluid (HTF) Market, CAGR | 8.7% |
| Heat Transfer Fluid (HTF) Market Size 2032 | USD 16586.54 million |
Market Overview:
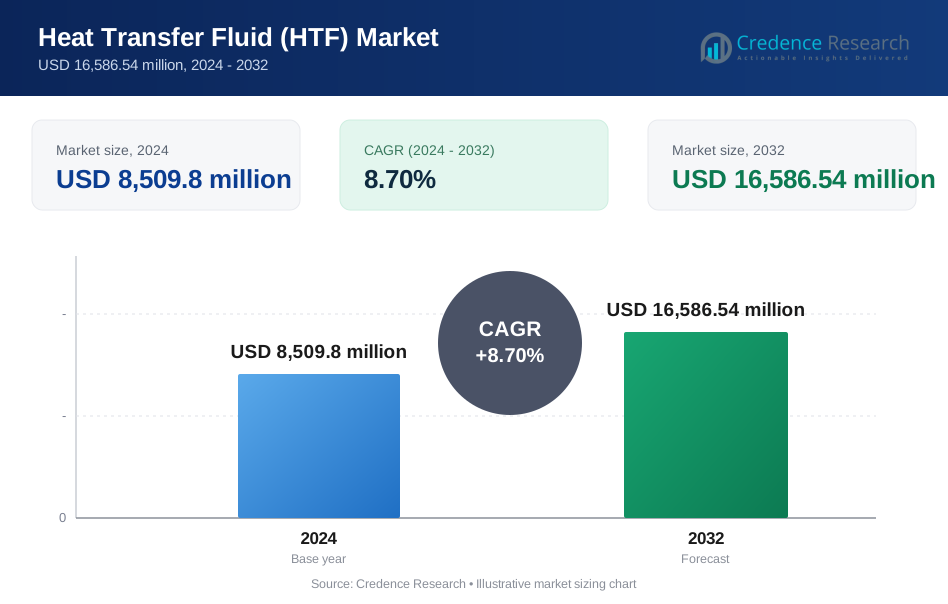
Heat Transfer Fluid (HTF) Market size was valued at USD 8509.8 million in 2024 and is anticipated to reach USD 16586.54 million by 2032, at a CAGR of 8.7% during the forecast period (2024-2032).
The HTF market is driven by several key factors, including the growing demand for renewable energy, particularly solar power, which requires effective heat transfer solutions. The widespread adoption of HTFs in concentrated solar power (CSP) plants, where they play a critical role in energy storage and heat transfer, is a major growth driver. As CSP plants gain prominence for their ability to store energy and provide uninterrupted power, HTFs are crucial in maintaining the system's efficiency. Furthermore, advancements in synthetic and bio-based HTFs that offer better temperature stability, enhanced performance, and lower environmental impact are accelerating market growth. These innovative HTFs are setting new industry standards, driving the shift towards more sustainable energy solutions. Additionally, the increasing demand for temperature regulation in industries like automotive, food and beverage, and pharmaceuticals contributes to the market's expansion, with HTFs becoming integral in temperature-sensitive processes.
Regionally, North America and Europe are the dominant markets for HTFs, driven by the increasing demand for efficient heating and cooling systems in industrial applications and renewable energy. The continuous push for greener energy solutions in these regions has led to higher investments in HTF-based technologies. However, the Asia Pacific region is expected to register the highest growth rate during the forecast period, fueled by rapid industrialization, particularly in China and India, and the rising adoption of renewable energy solutions. These countries are integrating HTFs into their infrastructure to meet growing energy demands and address environmental concerns. The market in Latin America and the Middle East & Africa is also projected to grow, albeit at a slower pace, as these regions gradually increase their focus on energy efficiency and sustainability. Strategic investments in renewable energy infrastructure are expected to further boost the HTF market in these regions.
Market Insights:
- The global Heat Transfer Fluid (HTF) market was valued at USD 8,509.8 million in 2024 and is projected to reach USD 16,586.54 million by 2032.
- The market is expected to grow at a CAGR of 8.7% from 2024 to 2032, driven by increasing demand for renewable energy solutions, particularly in solar power.
- HTFs are essential in concentrated solar power (CSP) plants, where they help store and transfer thermal energy, enabling continuous power generation.
- Advancements in synthetic and bio-based HTFs are setting new industry standards, improving temperature stability, and offering lower environmental impact.
- The demand for HTFs is expanding in industries such as automotive, food and beverage, pharmaceuticals, and chemicals, where precise temperature control is crucial.
- North America holds the largest market share of 35%, driven by high demand for energy-efficient solutions and renewable energy projects, especially in CSP.
- The Asia Pacific region is expected to experience the highest growth, driven by rapid industrialization and increased adoption of renewable energy, particularly in China and India.
Market Drivers:
Rising Demand for Renewable Energy Solutions:
The increasing shift towards renewable energy sources is a significant driver for the Heat Transfer Fluid (HTF) market. As governments, industries, and businesses around the world work to reduce their carbon footprints, renewable energy systems, especially solar power, have gained prominence. HTFs play a crucial role in concentrated solar power (CSP) plants, where they are used to transfer heat generated by solar radiation to power generation systems. The ability of HTFs to store and transfer heat effectively enhances the efficiency and output of solar power systems, leading to the growing adoption of CSP technology. This demand for renewable energy solutions is expected to remain strong as sustainability and environmental goals continue to drive investments in green energy technologies.
Technological Advancements in HTF Performance:
Technological advancements in HTF formulations and compositions are also accelerating market growth. The development of synthetic and bio-based HTFs that offer enhanced performance, greater temperature stability, and lower environmental impact has expanded the applications of HTFs in a variety of industries. For instance, SunLab, a research initiative under Sandia Corporation, has developed innovative molten salt formulations with reduced freezing points, which are particularly useful for advanced solar power plant applications. These innovative fluids are designed to operate effectively at higher temperatures, ensuring improved thermal efficiency in processes such as heat exchange, industrial heating, and cooling systems. As companies seek to optimize energy usage and reduce costs, the demand for HTFs that offer superior thermal performance is rising. The continued innovation and development of HTFs will help fuel the market's growth in the coming years.
Industrial Growth and Process Heating Demands:
The rapid growth of industries such as automotive, food and beverage, pharmaceuticals, and chemicals is driving the demand for HTFs. For example, Germany has seen a notable rise in HTF applications within modular refineries, supported by investments aimed at improving process efficiency. These industries require precise temperature control in various production processes, such as sterilization, drying, and mixing, which rely on efficient heat transfer systems. The HTFs provide a reliable and cost-effective solution to meet these temperature requirements, enabling smooth and efficient operations. Additionally, in manufacturing processes where high temperature regulation is critical, such as in automotive manufacturing and semiconductor production, HTFs are increasingly being used to optimize energy consumption and improve overall process efficiency.
Global Industrialization and Infrastructure Development:
The ongoing industrialization in emerging economies, particularly in the Asia Pacific region, is a significant driver for the HTF market. Countries such as China, India, and Southeast Asia are witnessing rapid growth in industrial activities and infrastructure development. The demand for energy-efficient solutions is rising as these nations work to meet the energy needs of their expanding manufacturing sectors and populations. HTFs are essential for enhancing the performance and efficiency of thermal systems in these regions, particularly in renewable energy and industrial applications. As these countries increase their focus on sustainable energy sources, the demand for HTFs will continue to rise, contributing to the overall growth of the market.
Market Trends:
Shift Towards Renewable Energy Applications:
The HTF market is experiencing a significant shift towards renewable energy applications, particularly in concentrated solar power (CSP) systems. HTFs are critical in CSP plants, where they store and transfer thermal energy, enabling electricity generation even during non-sunny periods. This trend aligns with the global emphasis on sustainable energy solutions and has led to increased investments in CSP technologies. As renewable energy adoption continues to rise, HTFs are becoming indispensable in ensuring the efficiency and reliability of solar power systems.
Technological Advancements in HTF Formulations:
There is ongoing research and development in HTF formulations, focusing on improving thermal stability, enhancing performance, and reducing environmental impact. The development of synthetic and bio-based HTFs is a key trend, as they meet the growing demand for more environmentally friendly solutions. For instance, Dow's DOWTHERM synthetic fluids have been recognized for their superior thermal stability and environmental benefits, making them a preferred choice in industries such as automotive and food processing. These advancements are crucial for industries such as automotive, food processing, and chemicals, where temperature regulation plays a vital role in ensuring process efficiency and sustainability. The trend toward more efficient and sustainable HTFs is expected to continue as industries seek to optimize energy usage while minimizing environmental footprints.
Integration of HTFs in Electric Vehicle (EV) Thermal Management:
The rise of electric vehicles (EVs) has introduced new applications for HTFs in thermal management systems. For example, Marelli's integrated Thermal Management Module (iTMM) combines multiple thermal circuits into one efficient system, optimizing energy management across EV batteries, e-powertrains, and cabins. Maintaining the optimal temperature of EV batteries is essential for performance, efficiency, and longevity. HTFs are increasingly being utilized in managing these temperatures, ensuring that EVs operate efficiently in various environmental conditions. As the automotive industry continues its transition towards electrification, the use of HTFs in EV systems is expected to grow, providing a new avenue for market expansion in this sector.
Expansion in Emerging Markets:
Rapid industrialization and urbanization in emerging economies, particularly in the Asia Pacific region, are driving the demand for HTFs. Countries such as China and India are seeing significant growth in manufacturing, energy production, and infrastructure development. As these markets expand, the need for efficient heat transfer solutions in sectors like chemicals, pharmaceuticals, and HVAC is growing. This presents substantial opportunities for HTF manufacturers to tap into these developing markets, where demand for sustainable and energy-efficient solutions is on the rise.
Market Challenges Analysis:
High Cost of Advanced HTFs:
One of the primary challenges in the Heat Transfer Fluid (HTF) market is the high cost of advanced HTF formulations, particularly synthetic and bio-based fluids. For instance, Eastman Chemical's Therminol® 66 was successfully implemented at SAIB, an Italian chipboard producer, to upgrade its plant technology. While these fluids offer superior thermal stability and environmental benefits, their production and processing costs are significantly higher than traditional HTFs. This cost disparity can limit the widespread adoption of advanced HTFs, particularly in price-sensitive industries. Smaller companies and organizations in developing regions may face budget constraints, making it difficult for them to invest in more expensive HTFs despite the long-term performance and efficiency benefits. Additionally, the higher initial costs may delay the return on investment, further discouraging potential adopters. The high initial investment required for these advanced solutions poses a barrier to market growth, especially for businesses operating on tight margins. As a result, companies may opt for less expensive but less efficient alternatives, impacting the overall market expansion.
Regulatory and Environmental Compliance:
Another challenge in the HTF market is navigating the increasingly stringent regulatory and environmental standards. As global sustainability initiatives tighten, HTF manufacturers must ensure that their products meet various environmental regulations regarding chemical composition and disposal. Compliance with these standards requires continuous investment in research and development to formulate HTFs that are both efficient and eco-friendly. Manufacturers may also face challenges in obtaining the necessary certifications for their products to ensure market acceptance. Additionally, the proper disposal of used HTFs and managing their environmental impact remain crucial concerns for manufacturers and end-users. The need for continuous innovation to meet regulatory demands, coupled with the costs associated with ensuring compliance, adds complexity to the market landscape. These challenges can slow down market adoption, particularly in regions where regulations are rapidly evolving, increasing operational costs and creating potential market barriers.
Market Opportunities:
The Heat Transfer Fluid (HTF) market presents significant growth opportunities, particularly in the renewable energy sector. As global emphasis on sustainability intensifies, the demand for efficient energy solutions, especially in concentrated solar power (CSP) plants, is on the rise. HTFs play a critical role in storing and transferring thermal energy in CSP systems, which enables continuous power generation even during non-sunny periods. The growing adoption of solar energy, driven by governmental policies and corporate sustainability goals, is expected to fuel demand for advanced HTFs. As more countries invest in renewable energy infrastructure, HTF manufacturers have an opportunity to expand their offerings, particularly with bio-based and synthetic fluids that offer enhanced performance and environmental benefits.
Furthermore, emerging markets present substantial opportunities for HTF growth. Rapid industrialization in regions like Asia Pacific, particularly in countries such as China and India, is driving the need for efficient heat transfer solutions across various industries, including automotive, chemicals, and food processing. These regions are witnessing an increase in manufacturing activities, which is further accelerating the demand for HTFs to support energy-efficient processes. As these markets continue to grow, HTF manufacturers can capitalize on the rising demand for reliable thermal management solutions. Additionally, the integration of HTFs in new technologies, such as electric vehicle thermal management systems, offers another promising avenue for market expansion. The continuous push for greener, more energy-efficient solutions positions HTFs as a crucial component in various sectors, providing manufacturers with abundant growth prospects.
Market Segmentation Analysis:
By Product
The Heat Transfer Fluid (HTF) market is segmented by product type, which includes synthetic, mineral oils, and bio-based fluids. Synthetic HTFs dominate the market due to their superior thermal stability and performance in high-temperature applications, particularly in renewable energy and industrial processes. Mineral oils hold a significant share due to their cost-effectiveness and reliability in medium-temperature operations. Bio-based HTFs are gaining traction due to their environmentally friendly properties and lower environmental impact, making them an attractive option for industries focused on sustainability. The increasing demand for greener solutions and the growing regulatory push for eco-friendly products are expected to drive the adoption of bio-based HTFs in the coming years.
By Application
The HTF market is also segmented by application, including solar power, chemical processing, HVAC, and others. The solar power segment is the largest, driven by the need for HTFs in concentrated solar power (CSP) plants where they help store and transfer thermal energy. The chemical processing and HVAC segments also represent significant portions of the market, with HTFs used for efficient temperature control in manufacturing and commercial systems. As industrial and renewable energy applications grow, the demand for HTFs in these sectors will continue to rise, supporting the overall market expansion. Additionally, the increasing integration of HTFs in electric vehicle thermal management systems further broadens the scope of applications.
Segmentations:
By Product
- Synthetic HTFs
- Mineral Oils
- Bio-based HTFs
By Application
- Solar Power
- Chemical Processing
- HVAC Systems
- Food and Beverage Processing
- Pharmaceuticals
- Automotive
- Other Industrial Applications
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global Heat Transfer Fluid (HTF) market, with a market share of 35%. This region’s dominance is primarily driven by the increasing demand for energy-efficient solutions in industries such as chemicals, automotive, and renewable energy. The United States, in particular, has seen a steady rise in the deployment of concentrated solar power (CSP) plants, which utilize HTFs for energy storage and heat transfer. The region's commitment to sustainability and renewable energy development, coupled with a growing interest in energy-efficient industrial applications, contributes to the market’s growth. Furthermore, advancements in HTF formulations and technology innovations in the automotive sector, including electric vehicle (EV) thermal management, are expected to sustain North America's leadership in the market. The high investment in clean energy and government incentives further support the region’s position as a market leader in HTF adoption.
Europe
Europe holds a significant share of the HTF market, accounting for 30% of the global market. The region's robust commitment to renewable energy initiatives, such as solar power and geothermal systems, is one of the key drivers of HTF adoption. The European Union's stringent environmental regulations and targets for reducing carbon emissions have led to substantial investments in energy-efficient solutions, particularly in CSP and industrial heat transfer applications. Countries like Germany, Spain, and France have been at the forefront of integrating HTFs in renewable energy projects, making the region a key player in the market. Additionally, the growth of industries requiring temperature regulation in food processing, pharmaceuticals, and chemicals further boosts the demand for HTFs in Europe. The region's established infrastructure and focus on sustainability ensure that Europe remains a significant market for HTFs.
Asia Pacific
The Asia Pacific region is witnessing the highest growth in the HTF market, with a market share of 25%. This region’s rapid industrialization, particularly in countries such as China and India, is driving significant demand for HTFs across various sectors, including manufacturing, automotive, and chemicals. The increasing focus on renewable energy, especially in solar power, is another key factor contributing to the growth in this region. The adoption of CSP plants and the growing need for energy-efficient industrial applications are boosting the demand for HTFs. Furthermore, as governments in the Asia Pacific region continue to implement policies promoting energy efficiency and sustainable practices, the HTF market is expected to experience robust growth. The region’s rising manufacturing base, coupled with increasing investments in renewable energy, positions it as a rapidly expanding market for HTFs, making it an attractive region for market participants to explore.
Key Player Analysis:
- BASF SE
- Exxon Mobil
- Dynalene, Inc.
- Indian Oil Corporation Ltd. (IOCL)
- Phillips 66
- Chevron Co.
- KOST USA, Inc.
- Hindustan Petroleum Corporation Ltd. (HPCL)Delta Western, Inc. (DWI)
- British Petroleum (BP)
- Huntsman Corporation
- Royal Dutch Shell Plc
- DowDuPont Chemicals
- Dalian Richfortune Chemicals Ltd.
- GJ Chemical
- Eastman Chemical Company
Competitive Analysis:
The Heat Transfer Fluid (HTF) market is highly competitive, with several key players striving to capture significant market share through product innovation, strategic partnerships, and geographic expansion. Major companies in the market include Dow Inc., BASF SE, and Paratherm, which offer a wide range of HTF solutions across various industries, including renewable energy, chemicals, and automotive. These companies focus on developing advanced HTFs with superior thermal stability, higher efficiency, and lower environmental impact to cater to the increasing demand for sustainable energy solutions. Additionally, regional players are increasingly focusing on expanding their offerings in emerging markets, particularly in Asia Pacific, where industrialization and renewable energy adoption are growing rapidly. Strategic acquisitions, collaborations, and investments in R&D are common strategies to enhance product offerings and gain a competitive edge. As the market evolves, companies that can deliver both performance and sustainability will likely maintain a competitive advantage.
Recent Developments:
- In February 2025, BASF SE announced an 18% increase in EBITDA for its core businesses in 2024, which include heat transfer fluids used in chemical processing and manufacturing. BASF attributed this growth to higher volumes and improved operational efficiencies.
- In January 2025, Eastman Chemical Company reported strong cash flow generation and adjusted EBIT margin improvements for 2024. The company continued operating its Kingsport methanolysis facility efficiently, positioning itself as a leader in sustainable chemical solutions, including heat transfer fluids.
- In October 2024, Eastman Chemical Company revealed its third-quarter financial results, emphasizing growth in specialty product lines that include heat transfer solutions for automotive and other industries. The company also announced plans for a second methanolysis facility in Texas to support circular economy initiatives.
Market Concentration & Characteristics:
The Heat Transfer Fluid (HTF) market is moderately concentrated, with a few key players dominating the market share, while a large number of regional and niche players also contribute to the competitive landscape. Leading companies such as Dow Inc., BASF SE, and Paratherm drive market innovation, focusing on advanced HTF formulations that offer improved thermal stability, efficiency, and lower environmental impact. These companies leverage extensive research and development capabilities, strong distribution networks, and strategic partnerships to maintain their market position. While the market is led by established players in North America and Europe, there is significant competition from regional manufacturers in emerging markets such as Asia Pacific and Latin America. The market is characterized by continuous innovation, with companies focusing on the development of bio-based and synthetic HTFs to cater to the growing demand for sustainable and high-performance solutions. Additionally, pricing strategies and customer-centric solutions are critical competitive factors.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for Heat Transfer Fluids (HTFs) will continue to grow due to the increasing adoption of renewable energy solutions, particularly in solar power systems.
- Technological advancements in HTF formulations will drive the development of fluids with improved thermal stability and higher efficiency, supporting diverse industrial applications.
- The expansion of electric vehicle (EV) production will create new opportunities for HTFs in battery thermal management systems.
- The increasing focus on sustainability and eco-friendly solutions will lead to higher adoption of bio-based HTFs, reducing the environmental impact of industrial processes.
- As industrial sectors such as automotive, chemicals, and food processing expand, the need for effective heat transfer solutions will drive HTF demand.
- Asia Pacific will experience rapid growth in HTF adoption due to industrialization, renewable energy projects, and increased energy efficiency initiatives in countries like China and India.
- Regulatory pressures and environmental standards will continue to influence HTF formulations, encouraging the development of more environmentally friendly options.
- The increasing integration of HTFs in concentrated solar power (CSP) systems will remain a major driver for market growth.
- Strategic partnerships and collaborations between HTF manufacturers and energy companies will be key to strengthening market positions.
- The market will see heightened competition, particularly from regional players offering cost-effective solutions tailored to emerging market needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Heat Transfer Fluid (HTF) market?
What are the key drivers of the HTF market growth?
Which regions are leading the HTF market?
What industries are driving the demand for HTFs?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Heat Transfer Fluid (HTF) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Heat Transfer Fluid (HTF) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,509.8 million → 2032: USD 16,586.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Heat Transfer Fluid (HTF) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Heat Transfer Fluid (HTF) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Heat Transfer Fluid (HTF) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Heat Transfer Fluid (HTF) Market Drivers
- 3.3 Heat Transfer Fluid (HTF) Market Restraints & Challenges
- 3.4 Heat Transfer Fluid (HTF) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Heat Transfer Fluid (HTF) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Heat Transfer Fluid (HTF) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Heat Transfer Fluid (HTF) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Heat Transfer Fluid (HTF) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Heat Transfer Fluid (HTF) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Heat Transfer Fluid (HTF) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Heat Transfer Fluid (HTF) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Heat Transfer Fluid (HTF) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Heat Transfer Fluid (HTF) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Heat Transfer Fluid (HTF) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Heat Transfer Fluid (HTF) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Heat Transfer Fluid (HTF) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Heat Transfer Fluid (HTF) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Heat Transfer Fluid (HTF) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Heat Transfer Fluid (HTF) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Heat Transfer Fluid (HTF) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Heat Transfer Fluid (HTF) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Heat Transfer Fluid (HTF) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Heat Transfer Fluid (HTF) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
