
Market Overview:
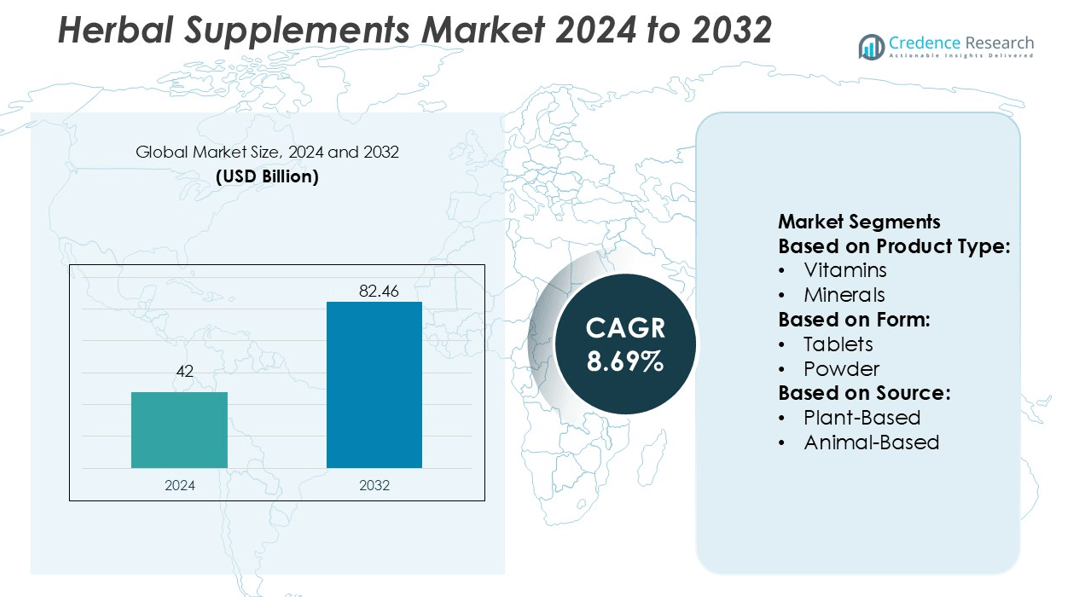
Herbal Supplements Market size was valued USD 42 billion in 2024 and is anticipated to reach USD 82.46 billion by 2032, at a CAGR of 8.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Herbal Supplements Market Size 2024 | USD 42 billion |
| Herbal Supplements Market, CAGR | 8.69% |
| Herbal Supplements Market Size 2032 | USD 82.46 billion |
The Herbal Supplements Market is shaped by strong competition among established and emerging companies offering diverse natural wellness solutions. Prominent players such as Gaia Herbs, Swanson, Solgar, Inc., Jarrow Formulas, Inc., Nature’s Bounty, Amway, Ancient GreenFields PVT LTD, NOW Foods, Herbalife, and Nature's Way dominate through innovation, product expansion, and strategic marketing. These companies focus on herbal-based formulations addressing immunity, stress, and digestion to cater to shifting consumer preferences toward preventive healthcare. Asia-Pacific leads the global market with a 24.9% share, driven by traditional medicine systems, rising disposable income, and expanding local production capabilities. The region’s cost-effective manufacturing and rich herbal resources further strengthen its leadership in the market.
Market Insights
- The Herbal Supplements Market was valued at USD 42 billion in 2024 and is projected to reach USD 82.46 billion by 2032, growing at a CAGR of 8.69%.
- Rising demand for natural and preventive healthcare products is driving market growth, supported by increasing awareness of herbal nutrition and organic wellness.
- The market is witnessing trends toward clean-label, plant-based, and research-backed formulations, with digital retail platforms expanding global reach.
- Intense competition among leading players focusing on innovation, product expansion, and sustainability shapes the competitive landscape and influences pricing strategies.
- Asia-Pacific dominates the market with a 24.9% share, fueled by traditional medicine practices and cost-effective production, while the vitamins and minerals segment holds the largest product share due to widespread usage in daily health management.
Market Segmentation Analysis:
By Product Type
In the herbal supplements market, single‑herb products lead the product‑type segment with approximately 52.6% share in 2024. This dominance occurs as consumers prefer focused botanical ingredients with defined benefits, rather than broad multicomponent formulations. The adoption of single‑herb products is driven by growing interest in targeted health outcomes-such as immunity, stress relief and digestion-and expanded availability of certified herbal extracts through wellness and e‑commerce channels. Vendors are emphasizing standardized herbals with validated bioactivity to build trust and bolster uptake.
- For instance, Swanson's Echinacea Standardized delivers 200 mg of Echinacea angustifolia root extract (standardized to 4% echinacosides) plus 200 mg of Echinacea purpurea (aerial parts) whole herb, with lot-level QC and third-party lab verification.
By Form
In terms of product form, the capsules & tablets sub‑segment held the dominant share of about 44.6% in 2024. Tablets and capsules benefit from ease of dosing, portability and familiarity, which resonates with mainstream consumers seeking simple supplement routines. The preference for this form is also supported by manufacturers’ capacity to deliver standardized doses, ensure long shelf life and leverage existing packaging infrastructure. The wider availability through pharmacies and mass‑retail channels accelerates growth of this form segment in the herbal category.
- For instance, Jarrow Formulas, Inc. QH-absorb® ubiquinol formulation, plasma total CoQ10 levels rose from 0.70 µg/mL to 6.14 µg/mL, and reduced CoQ10 rose from 0.62 µg/mL to 5.75 µg/mL.
By Source
Within the source segment, plant‑based ingredients dominate, driven by the strong consumer demand for natural, botanical and vegan‑friendly solutions. Although distinct share numbers vary, the broader plant‑based supplements market (which overlaps with herbal) accounted for about 34% of product‑type share in 2024. The driver is the rising preference for clean‑label, ethical and sustainable wellness options among younger cohorts. Manufacturers are responding with 100% herb‑derived formulations, improved supply‑chain transparency and certifications around origin and extraction to support this shift.Top of Form
Key Growth Drivers
Rising Health Awareness and Preventive Healthcare
Increasing consumer focus on health and preventive care is significantly driving herbal supplement demand. People are shifting from synthetic medications to natural remedies for overall wellness and immunity enhancement. For instance, companies like Nature’s Bounty have launched immunity-boosting herbal blends with standardized extracts, reinforcing consumer trust. The trend spans across age groups, particularly among millennials and middle-aged populations who prefer natural health solutions. This shift boosts sales across multiple channels, including e-commerce, retail pharmacies, and wellness stores, expanding market penetration globally.
- For instance, Immune 24 Hour + softgels deliver 1,000 mg of a clinically studied form of Vitamin C (Ester-C®) per serving, which the company states “stays in your white blood cells for up to 24 hours” and lasts up to 2× longer than regular Vitamin C.
Expanding E-commerce and Digital Sales Channels
The growth of online retail platforms is enhancing accessibility and visibility for herbal supplements. Consumers increasingly purchase herbal products through digital marketplaces, benefiting from detailed product information, reviews, and doorstep delivery. For instance, Himalaya Wellness reported a 27% increase in online sales after launching its e-commerce platform with targeted digital campaigns. This expansion reduces geographic limitations, allowing global reach, and supports small and medium-sized brands to enter the market. The convenience of online access encourages repeat purchases, driving sustained market growth.
- For instance, Amway states that its online sales (via the e-commerce platform empowering its business-owners and direct customers) contributed 45% of total sales, down from 51% in FY 2023.
Government Support and Regulatory Approvals
Supportive regulations and government initiatives promoting herbal and traditional medicine contribute to market expansion. Regulatory bodies are streamlining approval processes for herbal supplements, ensuring safety and efficacy, which increases consumer confidence. For instance, Dabur India received regulatory clearance for its new herbal digestive supplement, enabling nationwide distribution. Such approvals enhance market credibility and attract international exports. Additionally, government campaigns emphasizing natural health remedies boost public awareness and adoption. These factors collectively encourage manufacturers to innovate and expand product portfolios.
Key Trends & Opportunities
Product Innovation and Formulation Advances
Herbal supplement manufacturers are increasingly developing innovative formulations to meet diverse consumer needs. This includes blends targeting immunity, stress relief, digestive health, and beauty. For instance, Amway launched a plant-based supplement combining turmeric and probiotics, offering enhanced bioavailability and efficacy. Such product innovation allows differentiation in a competitive market and encourages higher adoption among health-conscious consumers. Continued R&D investment provides opportunities for personalized supplements, nutraceutical blends, and functional foods, further expanding market potential across multiple demographics.
- For instance, NOW’s in-house laboratories perform over 31,000 analyses and tests each month on raw materials, in-process ingredients and finished goods, employing 23 high-performance liquid chromatography (HPLC) instruments, 2 ion-chromatography systems, and multiple gas-chromatography units.
Rising Popularity of Plant-Based and Organic Products
Consumers are showing a strong preference for plant-based and organic herbal supplements due to perceived safety and environmental benefits. For instance, Gaia Herbs offers certified organic supplements, attracting environmentally conscious buyers. This trend aligns with the growing vegan and clean-label movement, creating opportunities for premium product lines. Companies can leverage certifications and transparent sourcing to build brand loyalty. Increased consumer willingness to pay for high-quality, natural ingredients stimulates growth in niche segments, enhancing profitability and encouraging market entrants to adopt sustainable sourcing practices.
- For instance, Winston-Salem spans approximately 800,000 square feet, and together their HIM (Herbalife Innovation & Manufacturing) facilities produce about 47% of their “inner nutrition” products sold globally.
Digital Wellness and Personalized Nutrition
The integration of technology with wellness offers opportunities for tailored herbal supplement solutions. Personalized recommendations via apps and AI-driven platforms help consumers select supplements based on lifestyle, health goals, and genetic profiles. For instance, Nutrigenomix collaborates with supplement brands to provide gene-based product suggestions, improving efficacy. This convergence of technology and herbal wellness allows brands to engage customers more effectively, increase adherence, and enhance perceived value. The personalized nutrition trend is projected to drive premium segment growth and attract tech-savvy, health-conscious consumers globally.
Key Challenges
Quality Control and Standardization Issues
Ensuring consistency, safety, and efficacy of herbal supplements remains a significant challenge. Variability in raw materials, extraction processes, and ingredient sourcing can affect product quality. For instance, some small-scale manufacturers have faced recalls due to contamination or inaccurate labeling of herbal content. Lack of global standardization complicates cross-border trade and regulatory compliance, impacting market credibility. Companies must invest in advanced testing, GMP-certified production, and transparent quality reporting to maintain consumer trust and mitigate risks associated with substandard products.
Regulatory Complexity and Compliance Barriers
Navigating diverse regulatory frameworks across regions poses challenges for herbal supplement manufacturers. Different countries enforce varying labeling, health claims, and safety requirements. For instance, exporting an Ayurvedic supplement from India to the EU requires compliance with stringent European safety standards and documentation. Non-compliance can result in delays, fines, or market exclusion, particularly for small and mid-sized companies. Companies must maintain robust regulatory intelligence, legal support, and adaptive manufacturing processes to ensure smooth international expansion while meeting evolving local and global compliance standards.
Regional Analysis
North America
North America leads the Herbal Supplements Market with a 36.2% share in 2024. The region benefits from a strong consumer shift toward preventive health and natural remedies. High awareness of dietary supplements and an established nutraceutical industry further drive demand. The U.S. dominates due to widespread retail availability, advanced product formulations, and FDA-approved herbal supplement regulations. Increasing integration of herbal products in mainstream pharmacy chains and e-commerce platforms supports market penetration. Moreover, rising demand for organic and clean-label formulations continues to propel market expansion across North America.
Europe
Europe holds a 28.6% share of the Herbal Supplements Market, supported by strong demand for botanical and natural health solutions. Countries such as Germany, France, and the UK are major contributors due to well-established herbal traditions and consumer trust in phytomedicine. The European Medicines Agency (EMA) regulates herbal products, enhancing safety and market credibility. Rising adoption among aging populations seeking natural alternatives to pharmaceuticals further boosts sales. Additionally, growing consumer preference for plant-based wellness products contributes to Europe’s steady market growth trajectory.
Asia-Pacific
Asia-Pacific accounts for a 24.9% share of the Herbal Supplements Market and exhibits the fastest growth. The region’s dominance stems from rich traditional medicine systems like Ayurveda, Traditional Chinese Medicine, and Kampo. China, India, and Japan are key markets due to abundant herbal resources and strong local manufacturing bases. Rising disposable incomes and health awareness among urban consumers increase supplement consumption. The expansion of nutraceutical startups and government initiatives promoting traditional medicine also enhance market potential across Asia-Pacific.
Latin America
Latin America captures a 6.4% share of the Herbal Supplements Market, driven by increasing awareness of preventive healthcare and the growing middle-class population. Brazil and Mexico lead due to the popularity of traditional plant-based remedies and expanding retail networks. Consumers increasingly favor herbal supplements for immunity, digestion, and energy enhancement. Regional producers focus on using indigenous herbs such as guarana and maca root. Improved distribution through pharmacies and e-commerce platforms strengthens accessibility, supporting continuous market growth across Latin America.
Middle East & Africa (MEA)
The Middle East & Africa region represents a 3.9% share of the Herbal Supplements Market and shows steady expansion. Growing preference for natural therapies and preventive care, especially in the Gulf Cooperation Council (GCC) countries, drives regional adoption. South Africa and the UAE are key contributors, with rising herbal product imports and expanding wellness centers. Increasing consumer education and healthcare spending also enhance market penetration. Additionally, government efforts to diversify healthcare products and promote local herbal manufacturing support MEA’s long-term market growth.
Market Segmentations:
By Product Type:
- Vitamins
- Minerals
By Form:
- Tablets
- Powder
By Source:
- Plant-Based
- Animal-Based
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Herbal Supplements Market features leading players such as Gaia Herbs, Swanson, Solgar, Inc., Jarrow Formulas, Inc., Nature’s Bounty, Amway, Ancient GreenFields PVT LTD, NOW Foods, Herbalife, and Nature's Way. The Herbal Supplements Market is highly competitive, marked by continuous innovation and diversification of product portfolios. Companies focus on developing science-backed formulations, organic sourcing, and sustainable production to strengthen consumer trust and meet regulatory standards. Expansion into digital and e-commerce channels has become a key growth strategy, allowing brands to reach health-conscious consumers more effectively. Manufacturers invest in R&D to create herbal blends addressing immunity, stress, and digestive health, aligning with global wellness trends. Moreover, strategic collaborations, clean-label certifications, and region-specific product adaptations play a vital role in expanding brand presence. The competition is further intensified by increasing private-label participation and continuous product differentiation aimed at maintaining market relevance.
Key Player Analysis
- Gaia Herbs
- Swanson
- Solgar, Inc.
- Jarrow Formulas, Inc.
- Nature’s Bounty
- Amway
- Ancient GreenFields PVT LTD
- NOW Foods
- Herbalife
- Nature's Way
Recent Developments
- In April 2025, The Vitamin Shoppe launched GLP-1 Support from Whole Health Rx was launched by the Vitamin Shoppe. The aim behind this launch was to address the health and nutritional needs of people taking GLP-1 medications for weight management.
- In February 2025, GetHealthy and Vitaboom partner to offer practitioners daily-dosed supplement packs, enhancing client convenience, compliance, and branding consumers.
- In September 2024, Tata Tea Gold unveiled a limited edition of Kumartuli-themed packs to celebrate the Durga Puja festival. The packs incorporate five symbolic elements: Dhunuchi dance, Shankho Dhwani, Dhaki, Ashtami Pujarin, and Sindoor Khela.
- In April 2024, Naturacare will be demonstrating its full manufacturing capabilities and launching four brand new products at Vitafoods Europe. The new offerings include Vital Extend, a bilayer tablet for energy and vitality; Bacti Serenity, targeting stress and gut-brain health.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Form, Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for plant-based supplements will continue to rise due to health awareness.
- Companies will focus more on organic certifications to build consumer trust.
- E-commerce and online distribution will play a greater role in product sales.
- Research-backed formulations will drive product differentiation in global markets.
- Clean-label and non-GMO products will dominate future product development trends.
- The aging population will create consistent demand for herbal supplements targeting chronic conditions.
- Asia-Pacific will emerge as a key production and consumption hub for herbal products.
- Collaborations with healthcare professionals will enhance brand credibility and consumer confidence.
- Technological integration in manufacturing will improve product quality and shelf stability.
- Regulatory harmonization across regions will encourage global expansion of herbal supplement brands.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health Awareness and Preventive Healthcare
Increasing consumer focus on preventive health and natural wellness is driving the adoption of herbal supplements, as people seek alternatives to synthetic medications for immunity, stress relief, and overall well-being.
Expanding E-commerce and Digital Sales Channels
The growth of online retail platforms and digital marketplaces has made herbal supplements more accessible, allowing consumers to easily compare products, read reviews, and receive home delivery, which expands market reach and supports smaller brands.
Government Support and Regulatory Approvals
Streamlined regulatory processes and government initiatives promoting herbal and traditional medicine are boosting consumer confidence and enabling wider distribution, both domestically and internationally.
Product Innovation and Clean-Label Trends
Manufacturers are investing in research-backed, clean-label, and plant-based formulations to meet consumer demand for transparency, safety, and efficacy, which differentiates products and encourages higher adoption rates.
Rising Popularity of Plant-Based and Organic Products
A growing preference for vegan, organic, and sustainably sourced herbal supplements is fueling market growth, as consumers are willing to pay a premium for products perceived as safer and more environmentally friendly.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global herbal supplements market?
What is the expected growth rate of the herbal supplements market between 2023 and 2030?
Which End-User segment governs the demand for herbal supplementss in the world?
Which region is fueling the growth of the herbal supplements industry?
Who are the major players in the global herbal supplements market?
What are the major market drivers of the herbal supplements industry?
What are the major market restraints of the herbal supplements industry?
What are the major market opportunities of the herbal supplements industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Tablets
- 1.2.2 Capsules
- 1.2.3 Powder
- 1.2.4 Liquid
- 1.2.5 Softgels
- 1.3 By Source
- 1.3.1 Plant-Based
- 1.3.2 Animal-Based
- 1.3.3 Fungi-Based
- 1.4 By Product Type
- 1.4.1 Vitamins
- 1.4.2 Minerals
- 1.4.3 Single-Herb Products
- 1.4.4 Multi-Herb Blends
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 42 billion → 2032: USD 82.46 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Herbal Supplements Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Herbal Supplements Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Herbal Supplements Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Herbal Supplements Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Herbal Supplements Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Herbal Supplements Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Herbal Supplements Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Herbal Supplements Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 42 billion → 2032: USD 82.46 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Herbal Supplements Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Tablets
- 12.3.7.2 Capsules
- 12.3.7.3 Powder
- 12.3.7.4 Liquid
- 12.3.7.5 Softgels
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plant-Based
- 12.4.7.2 Animal-Based
- 12.4.7.3 Fungi-Based
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Vitamins
- 12.5.7.2 Minerals
- 12.5.7.3 Single-Herb Products
- 12.5.7.4 Multi-Herb Blends
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Herbal Supplements Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Herbal Supplements Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Herbal Supplements Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Gaia Herbs
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Swanson
- 17.4 Solgar, Inc.
- 17.5 Jarrow Formulas, Inc.
- 17.6 Nature’s Bounty
- 17.7 Amway
- 17.8 Ancient GreenFields PVT LTD
- 17.9 NOW Foods
- 17.10 Herbalife
- 17.11 Nature's Way
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

