
Market Overview
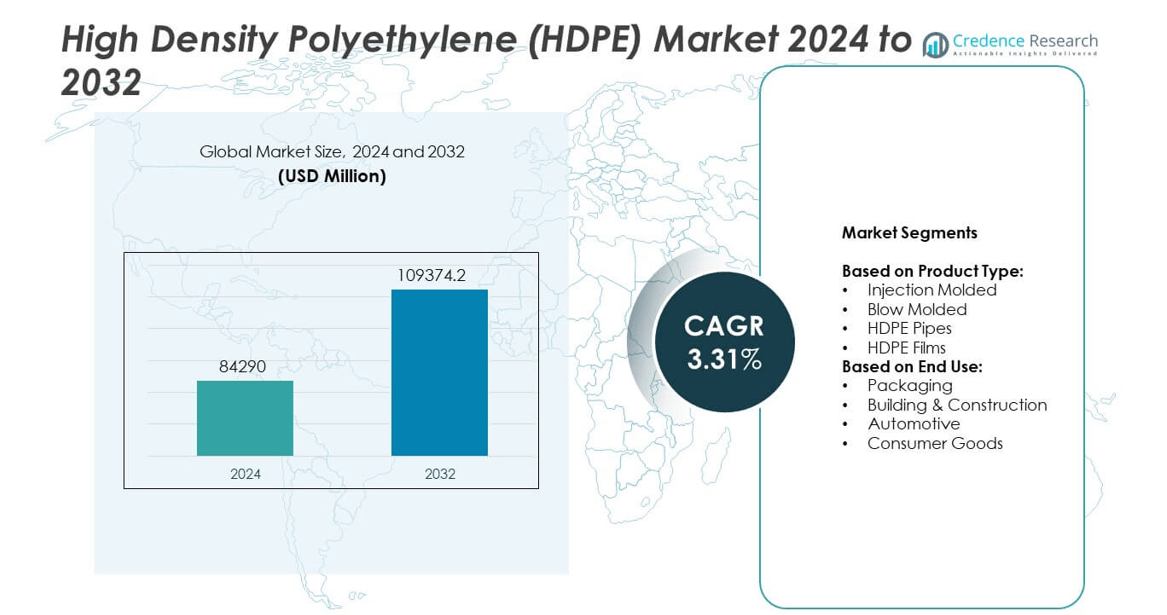
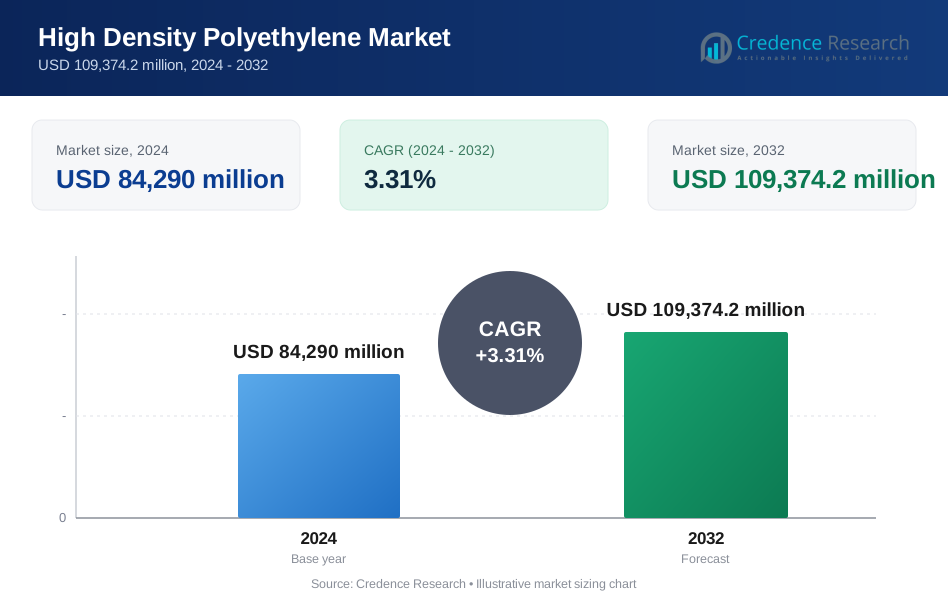
High Density Polyethylene (HDPE) Market size was valued at USD 84,290 million in 2024 and is anticipated to reach USD 109,374.2 million by 2032, at a CAGR of 3.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High Density Polyethylene (HDPE) Market Size 2024 | USD 84,290 million |
| High Density Polyethylene (HDPE) Market, CAGR | 3.31% |
| High Density Polyethylene (HDPE) Market Size 2032 | USD 109,374.2 million |
The High Density Polyethylene (HDPE) market grows through strong demand in packaging, construction, and automotive industries, supported by its durability, lightweight properties, and recyclability. Rising urbanization and infrastructure projects increase use in pipes and fittings, while automakers adopt HDPE to enhance fuel efficiency. Sustainability initiatives encourage higher integration of recycled HDPE in consumer and industrial applications. Advances in processing technology improve product performance and expand applications. Growing retail and e-commerce activities further strengthen market momentum across global regions.
The High Density Polyethylene (HDPE) market shows strong presence across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with Asia Pacific leading growth due to rapid industrialization and infrastructure projects. North America and Europe emphasize sustainability and advanced packaging solutions, while Latin America and the Middle East expand through construction and utilities. Key players shaping the market include Dow, Exxon Mobil Corporation, SABIC, and LyondellBasell Industries Holdings BV, all focusing on innovation and capacity expansion.
Market Insights
- The High Density Polyethylene (HDPE) market was valued at USD 84,290 million in 2024 and is projected to reach USD 109,374.2 million by 2032, growing at a CAGR of 3.31%.
- Rising demand in packaging drives growth due to durability, safety, and recyclability, supported by expansion of e-commerce and retail sectors.
- Construction and infrastructure projects increase use of HDPE pipes and fittings, strengthened by urbanization and government investments in water management and sanitation.
- Key trends include higher adoption of recycled HDPE, digital manufacturing technologies, and innovation in material properties for advanced applications.
- Leading players such as Dow, Exxon Mobil Corporation, SABIC, LyondellBasell, and Braskem compete through research, capacity expansion, and partnerships focused on sustainability.
- Market restraints include volatile raw material prices linked to crude oil fluctuations and growing competition from biodegradable alternatives under stricter environmental policies.
- Asia Pacific leads growth with rapid industrialization, while North America and Europe emphasize sustainable packaging, and Latin America and the Middle East & Africa expand through infrastructure and utilities.
Market Drivers
Growing Demand in Packaging Applications
High Density Polyethylene (HDPE) market expands due to its strong use in packaging. Its lightweight, durable, and resistant nature makes it ideal for bottles, containers, and films. It serves the food, beverage, and personal care industries where safety and shelf life matter. Manufacturers prefer it because of cost efficiency and recyclability. The packaging sector pushes demand with rising e-commerce and consumer goods consumption. It becomes a reliable choice for industries seeking both performance and sustainability. Growing retail activities worldwide strengthen its role further.
- For instance, Coca-Cola HBC, a bottling partner of The Coca-Cola Company, reported saving 300 metric tonnes of HDPE in one year by light-weighting bottle closures on its juice and tea portfolios in the Czech Republic, Hungary, Poland, and Romania. The initiative, which also included sparkling soft drinks in Nigeria, reduced CO2 emissions by over 600 tonnes
Rising Adoption in Construction and Infrastructure
The construction industry creates steady growth for the High Density Polyethylene (HDPE) market. It is used in pipes, fittings, and geomembranes for durability and chemical resistance. Its flexibility and strength make it suitable for water supply and sewage systems. Infrastructure expansion in emerging economies drives higher consumption. It offers long service life, reducing replacement and maintenance costs for projects. Government investments in housing, sanitation, and urban utilities enhance adoption. The building sector continues to rely on it for performance-driven solutions.
- For instance, GAIL (India) doubled its polymer plant capacity to 810,000 tonnes per year to serve PE pipe demand
Increasing Use in Automotive and Industrial Applications
High Density Polyethylene (HDPE) market benefits from rising use in automotive and industrial parts. It is lightweight, strong, and chemical resistant, making it ideal for fuel tanks and containers. Automakers prefer it to reduce vehicle weight and improve fuel efficiency. Industrial players use it in chemical storage, packaging, and machinery components. Growing emphasis on cost control and durability drives its penetration in these segments. The shift toward lighter and efficient materials supports growth. Its adaptability ensures steady preference in complex applications.
Sustainability and Recycling Initiatives Driving Adoption
The High Density Polyethylene (HDPE) market grows with global focus on sustainability. Recycling initiatives strengthen demand by reducing environmental impact. It is widely recycled, which improves acceptance among regulators and manufacturers. Governments set stricter rules on plastics, pushing industries to adopt recyclable solutions. Companies invest in circular economy programs, promoting recycled HDPE use. Sustainable packaging and green infrastructure rely heavily on it for compliance. The strong eco-friendly profile increases long-term relevance across industries.
Market Trends
Advancements in Packaging Solutions and Material Innovation
High Density Polyethylene (HDPE) market experiences notable trends through innovation in packaging. It gains preference in food, beverage, and personal care packaging due to safety and strength. Companies invest in advanced barrier properties to extend product shelf life. Lightweight and flexible HDPE designs address growing consumer convenience needs. E-commerce growth further accelerates packaging demand with secure and durable materials. It helps manufacturers balance cost efficiency with sustainability. The packaging trend continues to shape demand patterns globally.
- For instance, Incoplas introduced lightweight HDPE bottles up to 5 liters using ISBM resin SB 1359 from Total - these bottles feature significantly lower weight than traditional blow-molded bottles, while maintaining mechanical strength, their parnership are from 2012 to 2015.
Integration of Recycled Content and Circular Economy Practices
Sustainability drives a strong trend within the High Density Polyethylene (HDPE) market. Companies focus on recycled content to reduce environmental footprints. It finds wider use in consumer goods, pipes, and packaging with recycled blends. Global brands introduce products with high recycled HDPE content to meet regulations. Recycling technologies improve quality and consistency of the material. Government policies support the circular economy model, driving adoption. It strengthens the eco-friendly profile, expanding applications across regulated industries.
- For instance, Borealis's mtm plastics unit processes around 60,000 tonnes of post-consumer plastic waste annually into high-quality polyolefin recyclates, including HDPE and PP, for injection moulding and other applications.
Rising Role of Digital Manufacturing and Process Optimization
High Density Polyethylene (HDPE) market trends highlight technology adoption in production. Automation and advanced molding improve quality and efficiency. It supports faster production cycles and consistent material performance. Manufacturers adopt digital monitoring to enhance process control and reduce waste. Smart technologies optimize energy use, lowering operational costs. The push for precision and sustainability influences large-scale adoption of digital tools. It enables suppliers to meet rising global demand with higher reliability.
Expansion into Emerging Economies and Infrastructure Projects
The High Density Polyethylene (HDPE) market shows growth opportunities in developing regions. Rapid urbanization boosts use in water supply, sewage, and industrial systems. It is vital in infrastructure projects due to durability and resistance. Investments in housing, transport, and energy create consistent demand. Rising industrialization increases adoption in packaging and construction applications. Governments support modernization of utilities with HDPE-based solutions. It ensures growth momentum, particularly in Asia Pacific, Latin America, and Africa.
Market Challenges Analysis
Fluctuations in Raw Material Prices and Supply Chain Constraints
High Density Polyethylene (HDPE) market faces challenges due to volatile crude oil prices. It depends heavily on petrochemical feedstocks, making costs sensitive to global oil fluctuations. Supply chain disruptions add pressure, particularly during geopolitical tensions and trade restrictions. Rising transportation costs and shortages in logistics infrastructure worsen uncertainties for manufacturers. It impacts pricing stability, affecting competitiveness across global markets. Companies often struggle to balance profitability with demand growth during periods of high volatility. Consistent raw material supply remains a key concern for producers.
Environmental Regulations and Rising Competition from Alternatives
The High Density Polyethylene (HDPE) market experiences challenges from strict environmental policies. Governments enforce tighter rules on plastic waste management and recycling standards. It increases compliance costs for producers, requiring continuous investment in sustainable practices. Growing consumer preference for biodegradable alternatives also limits growth potential. Industries explore paper, bioplastics, and composites, creating competition for HDPE applications. Regulatory frameworks in developed regions demand higher recycling targets, putting pressure on manufacturers. It pushes companies to innovate while addressing environmental scrutiny.
Market Opportunities
Growing Scope in Sustainable Packaging and Recycling Solutions
High Density Polyethylene (HDPE) market presents opportunities through sustainable packaging initiatives. Brands adopt recyclable HDPE to meet consumer demand for eco-friendly products. It is widely used in food, beverage, and personal care packaging, where durability and safety matter. Recycling advancements improve the quality of post-consumer HDPE, creating reliable supply for industries. Global commitments to circular economy practices drive broader adoption of recycled HDPE. Companies leverage this trend to enhance brand reputation and regulatory compliance. It positions HDPE as a preferred solution in the evolving packaging landscape.
Expanding Applications in Infrastructure and Emerging Economies
The High Density Polyethylene (HDPE) market benefits from rising demand in developing regions. Infrastructure projects in water management, sanitation, and energy accelerate its use in pipes and fittings. It offers long service life, corrosion resistance, and cost efficiency, making it suitable for critical systems. Urbanization and industrial growth across Asia Pacific, Africa, and Latin America create consistent opportunities. Governments prioritize modernization of utilities and housing, strengthening demand for HDPE-based solutions. Renewable energy projects also support adoption in protective and structural components. It continues to expand its footprint across diverse industrial and civic applications.
Market Segmentation Analysis:
By Product Type:
Injection molded, blow molded, HDPE pipes, and HDPE films. Injection molded HDPE is widely used for containers, crates, caps, and household products due to its strength and versatility. It provides manufacturers with cost efficiency and consistency in large-scale production. Blow molded HDPE finds strong demand in bottles, tanks, and drums, benefiting from durability and chemical resistance. It plays a vital role in industries requiring safe liquid storage and transportation. HDPE pipes remain a critical product type, serving water supply, sewage, and industrial systems with long service life and low maintenance. HDPE films are adopted in packaging, agriculture, and industrial applications where lightweight, flexible, and durable solutions are required.
- For instance, Reube's Plastics Company manufactures injection-molded HDPE milk crates in standard sizes, such as a rectangular crate measuring 18.75" (L) × 13.00" (W) × 10.75" (H). The company uses a variety of injection molding machines to produce its products, which are designed to be durable while maintaining a manageable weight. However, the specific weight of 4.00 lb and the use of a Toshiba 610-ton injection molding machine for this particular product are not details that are publicly confirmed.
By End-Use:
The High Density Polyethylene (HDPE) market serves packaging, building and construction, automotive, and consumer goods. Packaging holds the largest share due to the material’s protective qualities, recyclability, and suitability for food and personal care applications. It supports e-commerce and retail growth by providing secure, lightweight, and sustainable solutions. Building and construction rely on HDPE for pipes, fittings, and geomembranes, driven by infrastructure projects in both developed and emerging economies. Automotive manufacturers use it in fuel tanks, containers, and components to reduce weight and improve efficiency. Consumer goods include household items, toys, and furniture, benefiting from HDPE’s durability and design flexibility. Each segment strengthens the market outlook by addressing diverse industrial, commercial, and consumer needs.
- For instance, The Cary Company distributes HDPE blow molded tanks with capacities ranging from 275 gal. to 330 gal., equipped with screw lids, O-ring gaskets, openings, and stackable design.
Segments:
Based on Product Type:
- Injection Molded
- Blow Molded
- HDPE Pipes
- HDPE Films
Based on End Use:
- Packaging
- Building & Construction
- Automotive
- Consumer Goods
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a significant position in the High Density Polyethylene (HDPE) market with a share of 21%. The region benefits from established industries such as packaging, automotive, and construction, which continue to rely on HDPE for efficiency and performance. Strong demand arises from the packaging sector, where food and beverage companies prefer HDPE due to its safety, durability, and recyclability. Automotive applications also support regional growth, with manufacturers adopting HDPE components to reduce vehicle weight and comply with fuel efficiency standards. Construction activities, including water supply and sewage systems, further drive demand for HDPE pipes and fittings. Stringent environmental regulations across the United States and Canada promote the use of recyclable materials, strengthening HDPE’s position. Ongoing investments in infrastructure modernization and sustainable packaging solutions ensure steady demand in the coming years.
Europe
Europe represents 19% of the High Density Polyethylene (HDPE) market share, supported by strict environmental policies and high recycling targets. The packaging sector drives significant demand, with regulatory frameworks encouraging recyclable materials for food, beverages, and consumer goods. The automotive industry also plays an important role, as leading manufacturers adopt lightweight HDPE materials to improve energy efficiency and meet emission norms. Construction remains another growth area, particularly in water management and infrastructure projects across Western and Eastern Europe. Europe demonstrates strong leadership in sustainability initiatives, which creates opportunities for recycled HDPE applications. The region’s commitment to the circular economy pushes industries to integrate recycled content, further strengthening HDPE demand. Growing industrial innovation ensures that HDPE maintains a strong presence across multiple applications in the European market.
Asia Pacific
Asia Pacific dominates the High Density Polyethylene (HDPE) market with the largest share of 42%. Rapid industrialization, urbanization, and infrastructure development fuel significant demand across packaging, construction, and automotive sectors. China, India, and Southeast Asian countries drive consumption due to large-scale industrial projects and rising consumer demand. Packaging applications expand rapidly, supported by growing retail and e-commerce sectors in the region. Construction projects, particularly in water supply, sewage, and housing, boost demand for HDPE pipes and fittings. Automotive manufacturers adopt HDPE in vehicles to improve efficiency and reduce costs, enhancing regional growth. The availability of raw materials and large-scale production capacities make Asia Pacific the global hub for HDPE supply and consumption. Continuous economic growth and infrastructure investments maintain the region’s dominance in the market.
Latin America
Latin America accounts for 9% of the High Density Polyethylene (HDPE) market share. Growth in the region is supported by infrastructure development, particularly in water management and urban utilities. Brazil and Mexico lead demand, driven by packaging applications in food, beverages, and consumer goods. Construction activities also contribute strongly, with HDPE pipes and fittings serving essential roles in sanitation and water supply. The automotive industry adopts HDPE for lightweight and durable components, reinforcing its use across multiple sectors. Recycling initiatives are gaining traction, helping HDPE align with sustainability goals in the region. Despite economic fluctuations, demand remains steady due to strong reliance on HDPE in everyday applications. Future growth is expected as governments invest in modernization of infrastructure and utilities.
Middle East & Africa
The Middle East & Africa holds 9% of the High Density Polyethylene (HDPE) market share. Strong demand comes from construction and infrastructure projects, particularly in water supply, sewage, and energy sectors. The packaging industry also expands, serving the food and consumer goods markets in growing urban centers. Governments across the region prioritize investment in utilities, creating consistent demand for HDPE-based solutions. The automotive and consumer goods industries adopt HDPE for durable and cost-effective applications. Rising focus on sustainability and recycling adds further opportunities for growth. Despite challenges in economic diversification, HDPE demand continues to strengthen due to its vital role in industrial and civic projects. The region remains a developing yet promising market for HDPE adoption across multiple industries.
Key Player Analysis
- INEOS
- Braskem S.A
- Exxon Mobil Corporation
- Chevron Phillips Chemical Co.
- SABIC
- Borealis AG
- Formosa Plastics Corp.
- LyondellBasell Industries Holdings BV
- Dow
- LOTTE Chemical Corporation
- PetroChina Company Limited
- Abu Dhabi Polymers Company Ltd
Competitive Analysis
The leading players in the High Density Polyethylene (HDPE) market include Dow, Exxon Mobil Corporation, INEOS, SABIC, LyondellBasell Industries Holdings BV, LOTTE Chemical Corporation, Borealis AG, PetroChina Company Limited, Abu Dhabi Polymers Company Ltd., Formosa Plastics Corp., Braskem S.A, and Chevron Phillips Chemical Co. These companies drive competition through innovation, large-scale production, and global distribution networks. They invest heavily in research and development to improve product quality, recyclability, and application versatility. Strong focus on sustainable practices and integration of recycled HDPE enhances their market positioning.Intense competition exists in packaging, automotive, and construction sectors, where product differentiation depends on cost efficiency and compliance with environmental regulations. Leading producers expand capacities in emerging economies to secure access to growing demand. Strategic partnerships and joint ventures strengthen supply chains, ensuring reliable raw material sourcing and market reach. Players also adopt advanced manufacturing technologies to reduce costs and improve efficiency. The market environment encourages continuous innovation, particularly in sustainable packaging solutions and circular economy models. Competitive dynamics remain defined by global presence, production flexibility, and alignment with environmental standards, ensuring that leading companies maintain dominance while addressing evolving industry requirements.
Recent Developments
- In June 2025, Dow commenced operations at a new production unit in Freeport, Texas, designed to produce both Linear Low-Density Polyethylene (LLDPE) and High-Density Polyethylene (HDPE). The new facility adds 600,000 metric tons per year of polyethylene capacity and will primarily serve the export market, enhancing Dow's resin portfolio and global export capabilities.
- In 2025, LyondellBasell licensed its polyolefin technologies to SHCCIG Yulin Chemical for a new petrochemical complex in China.
- In 2024, Borealis announced plans to install a semi-commercial compounding line in Belgium to process recyclates using the Borcycle-M technology.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The High Density Polyethylene (HDPE) market will see steady growth driven by packaging demand.
- Recycling initiatives will expand adoption of HDPE across regulated industries.
- Infrastructure development in emerging economies will support strong demand for HDPE pipes.
- Automotive manufacturers will increase use of HDPE to reduce vehicle weight.
- Digital manufacturing will improve production efficiency and material consistency.
- Sustainability goals will encourage higher use of recycled HDPE in consumer goods.
- Construction projects will rely on HDPE for water supply, sewage, and utility systems.
- Global brands will focus on circular economy practices to boost HDPE applications.
- Rising e-commerce will strengthen demand for HDPE-based packaging solutions.
- Innovation in material properties will expand HDPE use in advanced applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand in Packaging Applications
HDPE's lightweight, durable, and recyclable properties make it the material of choice for bottles, containers, and films in the food, beverage, and personal care industries. The expansion of e-commerce and retail sectors further accelerates demand for HDPE-based packaging solutions.
Rising Adoption in Construction and Infrastructure
HDPE is increasingly used in pipes, fittings, and geomembranes for water supply, sewage, and industrial systems due to its strength, flexibility, and chemical resistance. Urbanization and government investments in infrastructure projects, especially in emerging economies, are driving higher consumption.
Increasing Use in Automotive and Industrial Applications
Automotive manufacturers are adopting HDPE for fuel tanks and components to reduce vehicle weight and improve fuel efficiency, while industrial sectors use it for chemical storage and machinery parts. The shift toward lighter, more efficient materials supports HDPE's penetration in these segments.
Sustainability and Recycling Initiatives
Global focus on sustainability and stricter regulations on plastic waste are encouraging the use of recycled HDPE in packaging and industrial applications. Companies are investing in circular economy programs and advanced recycling technologies, boosting the adoption of HDPE with recycled content.
Advancements in Processing Technology
Innovations in digital manufacturing, automation, and material science are improving HDPE product performance, consistency, and cost efficiency. These advancements enable manufacturers to meet rising global demand and expand HDPE applications in advanced and regulated industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and future size of the High-Density Polyethylene (HDPE) market?
What are the key factors driving the growth of the HDPE market?
Which region leads the global HDPE market?
Why is HDPE considered environmentally friendly?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Packaging
- 1.2.2 Building & Construction
- 1.2.3 Automotive
- 1.2.4 Consumer Goods
- 1.3 By Product Type
- 1.3.1 Injection Molded
- 1.3.2 Blow Molded
- 1.3.3 HDPE Pipes
- 1.3.4 HDPE Films
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 84,290 million → 2032: USD 109,374.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global High Density Polyethylene Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global High Density Polyethylene Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global High Density Polyethylene Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global High Density Polyethylene Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global High Density Polyethylene Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global High Density Polyethylene Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global High Density Polyethylene Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global High Density Polyethylene Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 84,290 million → 2032: USD 109,374.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global High Density Polyethylene Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Packaging
- 12.3.7.2 Building & Construction
- 12.3.7.3 Automotive
- 12.3.7.4 Consumer Goods
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Injection Molded
- 12.4.7.2 Blow Molded
- 12.4.7.3 HDPE Pipes
- 12.4.7.4 HDPE Films
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global High Density Polyethylene End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global High Density Polyethylene Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global High Density Polyethylene Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global High Density Polyethylene Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dow
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Exxon Mobil Corporation
- 18.4 SABIC
- 18.5 LyondellBasell Industries Holdings BV
- 18.6 INEOS
- 18.7 Braskem S.A
- 18.8 Chevron Phillips Chemical Co.
- 18.9 Borealis AG
- 18.10 Formosa Plastics Corp.
- 18.11 LOTTE Chemical Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

