
Market Overview:
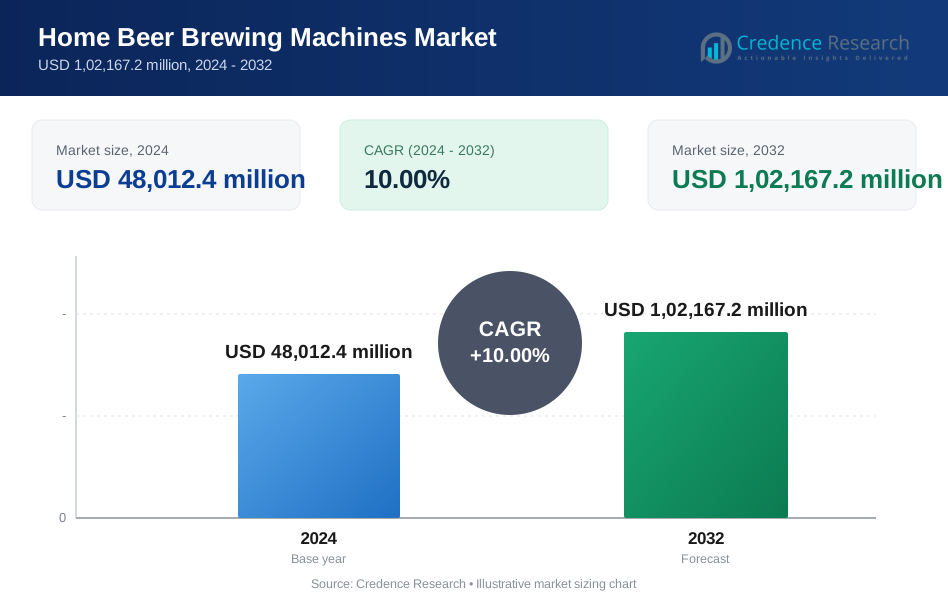
The Home Beer Brewing Machine Market size was valued at USD 35,400.0 million in 2018 to USD 48,012.4 million in 2024 and is anticipated to reach USD 1,02,167.2 million by 2032, at a CAGR of 10.0% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Home Beer Brewing Machine Market Size 2024 | USD 48,012.4 million |
| Home Beer Brewing Machine Market, CAGR | 10.% |
| Home Beer Brewing Machine Market Size 2032 | USD 1,02,167.2 million |
Market growth is driven by rising consumer interest in craft beer, home-based leisure activities, and personalized brewing experiences. Increasing disposable income and growing awareness of premium beer quality encourage more individuals to invest in automated brewing machines. The convenience of smart brewing systems, coupled with the trend of hobbyist brewing, has further expanded adoption. Manufacturers are also introducing user-friendly and compact models, making brewing accessible to both beginners and enthusiasts.
Regionally, North America leads the market due to strong craft beer culture, advanced brewing technology adoption, and high consumer spending. Europe follows, supported by established beer traditions in Germany, Belgium, and the UK, boosting demand for personalized brewing solutions. Asia-Pacific is emerging as a fast-growing region, driven by rising urbanization, expanding middle-class populations, and growing interest in Western-style craft beer consumption.

Market Insights:
- The Home Beer Brewing Machine Market was valued at USD 35,400.0 million in 2018, grew to USD 48,012.4 million in 2024, and is projected to reach USD 1,02,167.2 million by 2032, at a CAGR of 10.0%.
- North America held the largest regional share of 1% in 2024, followed by Europe at 27.4%, and Asia Pacific at 25.7%, driven by strong craft beer culture, disposable income, and premium lifestyle demand.
- Asia Pacific is the fastest-growing region with an 3% CAGR, supported by urbanization, rising middle-class populations, and growing interest in personalized brewing solutions.
- In 2024, mini brewers accounted for 3% of the market share, benefiting from affordability, compact design, and high adoption among beginners.
- Full-size brewers represented 7% of the market share in 2024, with demand rising among hobbyists and premium consumers seeking greater capacity and customization.
Market Drivers:
Rising Preference for Craft and Personalized Brewing Experiences
The growing demand for craft beer has played a vital role in pushing consumer interest toward home brewing systems. Individuals are increasingly drawn to brewing their own beer to achieve customized flavors and styles. The Home Beer Brewing Machine Market benefits from this cultural shift, as consumers perceive these devices as a gateway to personal creativity. Rising awareness of premium-quality beers has reinforced the trend, with customers wanting more control over taste and ingredients. It supports the transition of beer lovers from passive drinkers to active creators. Rising disposable income has also provided consumers with the capacity to invest in innovative brewing solutions. Compact machines designed for easy use have lowered the entry barrier for beginners. Brands are offering machines that combine simplicity with high-quality output. This has ensured sustained demand from both first-time users and seasoned enthusiasts.
Technological Advancements in Brewing Automation and Smart Features
Technological improvements have strengthened the appeal of automated brewing devices worldwide. Machines now integrate smart controls, IoT connectivity, and automated cleaning features, making them attractive to modern households. The Home Beer Brewing Machine Market gains strong momentum from these advancements, which reduce errors and simplify the process. It enables users to enjoy a seamless brewing experience without professional knowledge. Integration of recipe libraries and guided brewing through apps has made beer preparation efficient and interactive. Companies are using technology to build trust and enhance reliability in machine performance. Precision control over fermentation and temperature allows users to replicate consistent results. Rising demand for convenience aligns with these features, further driving adoption. This has positioned automation as a key factor for growth.
- For instance, the LG HomeBrew debuted at CES 2019, featuring automated capsule-based brewing and self-cleaning; it produces 5 liters of beer per batch with one-touch controls, precise automated temperature management, and app-based monitoring throughout the brewing process
Expanding Hobby Culture and Community Engagement in Beer Brewing
Home brewing has developed into a popular hobby, with communities supporting knowledge exchange and innovation. Many consumers now see brewing as a social activity that brings people together. The Home Beer Brewing Machine Market thrives because of the lifestyle appeal that surrounds this hobby. It helps create an ecosystem where sharing recipes, experimenting with flavors, and collaborating with friends enhances the value of ownership. Global festivals, workshops, and online communities promote engagement and keep interest levels high. Manufacturers have recognized the importance of such networks in boosting awareness. They are partnering with influencers, hobby clubs, and beer festivals to expand consumer reach. Consumers feel encouraged to experiment due to accessible learning resources. This supportive environment continues to shape consumer loyalty.
Rising Disposable Income and Premium Lifestyle Orientation in Urban Areas
Urban consumers with higher spending power are fueling consistent demand for home brewing solutions. These consumers link home brewing with premium lifestyle choices that reflect individuality. The Home Beer Brewing Machine Market benefits from this alignment with aspirational living standards. It caters to middle- and high-income groups who value unique experiences over mass-produced products. Rising exposure to international beer culture has strengthened this preference. Urbanization has increased the number of households adopting such systems as part of leisure activities. Young professionals often adopt brewing machines as both an investment and a form of self-expression. Brands are aligning marketing strategies to highlight exclusivity and sophistication. This positioning has secured growth in cities where premiumization trends are evident.
- For example, the MiniBrew Craft Gen 3 is a countertop brewing system that produces up to 6 liters per cycle. It features a compact design, self-cleaning kegging system, and access to a recipe library, appealing to space-conscious and design-focused homebrewers.
Market Trends:
Integration of Smart Connectivity and App-Controlled Brewing Functions
Smart connectivity has emerged as a defining feature in modern brewing machines. Manufacturers are integrating mobile applications that provide guided brewing, real-time monitoring, and automated adjustments. The Home Beer Brewing Machine Market benefits by aligning with the growing smart home ecosystem. It enhances convenience for users who value control and precision in every step. It also enables remote operation, appealing to younger demographics familiar with connected devices. Personalized recipe storage and digital brewing communities add value to these solutions. Brands are building ecosystems around apps to strengthen customer loyalty. Rising interest in IoT-based devices ensures continued investment in such developments. Smart features are becoming a clear differentiator in consumer decision-making.
Growing Popularity of Compact and Space-Saving Brewing Designs
Urban households face limited living space, which has created demand for compact brewing solutions. Manufacturers are responding with smaller, portable, and stylish machines that blend with modern interiors. The Home Beer Brewing Machine Market has expanded due to this focus on design efficiency. It allows city-based consumers to enjoy brewing without major space adjustments. Sleek and aesthetic designs also appeal to younger demographics looking for functional yet attractive products. Companies are investing in premium designs that enhance home décor appeal. Such machines also target customers with minimal storage capacity but strong interest in craft beer. Portable systems appeal to consumers who enjoy brewing in social gatherings or outdoor activities. The trend has established compact brewing as a key growth segment.
- For example, the BREWHA BIAC 5-USG (20 L) All-in-One System combines mashing, boiling, and fermenting in a single conical vessel. With a compact 16-inch footprint and 35-inch height, it brews full 20 L batches in limited spaces while simplifying cleaning and setup.
Rising Collaboration Between Brewing Machine Brands and Craft Beer Producers
Strategic collaborations between brewing machine brands and craft beer companies are shaping the industry. These partnerships help manufacturers offer authentic recipes and brewing kits that reflect established craft flavors. The Home Beer Brewing Machine Market gains credibility through such associations with expert brewers. It provides consumers access to tried-and-tested recipes directly from professional brewers. It also bridges the gap between commercial craft beer and home brewing. Companies view such collaborations as opportunities to build trust and expand their customer base. Limited-edition brewing kits have also emerged from these partnerships, driving exclusivity. Breweries benefit from reaching home brewing enthusiasts, creating new marketing channels. The trend strengthens industry integration across different levels of beer culture.
Rising Focus on Sustainable Brewing Practices and Eco-Friendly Machine Designs
Environmental awareness has influenced consumer choices, creating demand for sustainable brewing solutions. Manufacturers are designing machines that consume less energy, use recyclable materials, and promote waste reduction. The Home Beer Brewing Machine Market adapts to these expectations by integrating eco-friendly features. It supports consumers who prefer brewing systems aligned with responsible consumption. Brands emphasize durability and low-maintenance designs to reduce environmental impact. The focus on sustainable packaging for brewing kits further supports green initiatives. Eco-conscious consumers view brewing at home as a way to reduce reliance on packaged beers. Companies are showcasing environmental credentials as a marketing advantage. This trend reflects a long-term industry shift toward eco-friendly innovation.
- For example, Sierra Nevada Brewing Company’s Mills River facility is the first U.S. brewery with both LEED Platinum and TRUE Zero Waste Platinum It diverts 99.8% of solid waste, generates over 2.5 MW of renewable energy, and reuses millions of gallons of water annually while maintaining extensive rainwater storage for operations.

Market Challenges Analysis:
High Initial Costs and Limited Consumer Awareness Restrict Growth
The premium price of automated brewing machines remains a major obstacle for large-scale adoption. Many potential buyers perceive these systems as expensive investments, limiting demand in cost-sensitive markets. The Home Beer Brewing Machine Market faces resistance from consumers who prioritize affordability over advanced features. It creates challenges for manufacturers attempting to expand into emerging economies. It also requires consistent educational efforts to increase consumer awareness of the value proposition. Limited exposure to brewing culture in some regions reduces willingness to adopt. Companies face hurdles in justifying the cost through marketing campaigns. Targeting new customers requires a balance between pricing strategies and feature offerings. This challenge slows growth across diverse demographics.
Regulatory Restrictions and Quality Perception Issues in Home Brewing
Regulatory frameworks on alcohol production and consumption can hinder home brewing adoption in some countries. Governments often impose restrictions that make machine ownership and use less straightforward. The Home Beer Brewing Machine Market encounters difficulties when consumers perceive home brewing as legally complex. It also faces quality perception issues, with some buyers doubting consistency compared to commercial beer. It pressures manufacturers to prove machine reliability and maintain compliance with safety standards. Misconceptions about the complexity of brewing reduce adoption rates further. Brands must invest in education and customer support to overcome these doubts. Meeting strict regulations and maintaining product credibility remain significant challenges. Failure to address these issues impacts overall acceptance levels.
Market Opportunities:
Expansion into Emerging Markets with Growing Middle-Class Populations
Emerging economies are creating favorable conditions for brewing machine adoption. Rising middle-class incomes and increasing urbanization strengthen demand for home brewing systems. The Home Beer Brewing Machine Market benefits from these shifts by tapping into aspirational buyers. It allows manufacturers to penetrate regions where exposure to global beer culture is increasing. It creates room for innovative, mid-range products suited to diverse budgets. Localized marketing and distribution strategies can increase accessibility. Expanding into Asia-Pacific, Latin America, and parts of Africa presents long-term potential. Companies that adapt products to local preferences will secure a competitive edge. Market players are well positioned to capitalize on this demographic change.
Product Diversification Through Customizable Kits and Premium Experiences
Customization is emerging as a strong driver of consumer loyalty. Offering diverse recipe kits and premium brewing experiences can enhance satisfaction levels. The Home Beer Brewing Machine Market is poised to expand through such innovations. It allows companies to build repeat revenue models while strengthening brand engagement. It also provides consumers with greater control over flavor and style. Developing advanced machines that offer enhanced personalization can attract premium buyers. Companies are also exploring subscription models to maintain recurring customer interactions. This creates opportunities to expand revenue streams beyond machine sales. Personalization and premium experiences are set to shape the next phase of growth.
Market Segmentation Analysis:
The Home Beer Brewing Machine Market is segmented
By product into mini brewers and full-size brewers. Mini brewers dominate demand among urban consumers due to their compact design, ease of use, and affordability. They are widely adopted by beginners and hobbyists who seek convenience without requiring significant space. Full-size brewers attract seasoned users and enthusiasts who desire greater control, larger capacity, and advanced customization options. It continues to show promise in premium segments where consumers associate brewing with lifestyle and social experiences. Manufacturers are focusing on balancing affordability with advanced features to appeal to diverse consumer groups.
- For example, the MiniBrew Craft Gen 3 delivers a fully automated brewing experience in one compact unit. It brews, ferments, and serves up to 5–6 liters via app control, and it includes a clean-in-place system for simplified maintenance.
By mechanism, the market is divided into automatic and manual machines. Automatic machines account for a significant share due to their ability to simplify brewing through preset programs, smart controls, and consistent results. It is particularly attractive to new users who want professional-quality beer without technical expertise. Manual machines, though less prevalent, appeal to traditional brewers and craft enthusiasts who value experimentation and hands-on processes. This segment benefits from communities that prefer authenticity and personalization in the brewing journey. The balance between automation and manual operation highlights consumer diversity, creating opportunities for brands to cater to multiple experience levels.
- For example, the Coopers DIY Beer Kit includes equipment and ingredients to brew 23 liters per batch. It requires full manual control, appealing to hobbyists and craft enthusiasts seeking traditional, customizable brewing experiences.

Segmentation:
By Product
- Mini Brewer
- Full-Size Brewer
By Mechanism
- Automatic
- Manual
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Home Beer Brewing Machine Market size was valued at USD 11,859.0 million in 2018 to USD 15,872.6 million in 2024 and is anticipated to reach USD 33,718.0 million by 2032, at a CAGR of 10.0% during the forecast period. North America accounts for the largest regional share of the global market, supported by strong consumer interest in craft beer and advanced brewing technologies. The region benefits from a mature beer culture, particularly in the U.S., where home brewing is widely popularized. It thrives on consumer willingness to experiment with personalized beer recipes. High disposable incomes and exposure to global brewing trends strengthen adoption across households. Canada contributes steadily, with growing demand in urban centers. Mexico has also shown rising interest, supported by cultural integration of craft brewing practices. The region’s well-developed distribution and online retail networks ensure easy accessibility of brewing machines.
Europe
The Europe Home Beer Brewing Machine Market size was valued at USD 10,053.6 million in 2018 to USD 13,144.5 million in 2024 and is anticipated to reach USD 26,538.2 million by 2032, at a CAGR of 9.3% during the forecast period. Europe holds a significant share driven by its long-standing beer traditions and rising craft beer movement. The market benefits from strong demand in Germany, Belgium, and the UK, where beer consumption is culturally embedded. It gains traction among consumers seeking premium experiences and artisanal quality. Regional players focus on innovation while maintaining adherence to traditional brewing standards. France and Italy have recorded increasing adoption among younger demographics attracted to hobbyist brewing. Spain also contributes with rising interest in compact brewing systems for households. High awareness of beer varieties and strong tourism influence support regional demand. Companies are leveraging historic brewing cultures to introduce advanced home brewing systems.
Asia Pacific
The Asia Pacific Home Beer Brewing Machine Market size was valued at USD 8,708.4 million in 2018 to USD 12,331.8 million in 2024 and is anticipated to reach USD 28,855.2 million by 2032, at a CAGR of 11.3% during the forecast period. Asia Pacific is the fastest-growing region, supported by rising disposable incomes and expanding middle-class populations. China and Japan are leading contributors due to strong urban demand and exposure to global beer culture. It is also gaining momentum in India, where younger consumers are adopting hobbyist lifestyles. South Korea and Australia demonstrate steady adoption driven by cultural openness to craft brewing. Southeast Asia provides opportunities due to increasing urbanization and changing social preferences. Rising e-commerce penetration has improved product availability across diverse markets. Manufacturers are customizing machines to meet regional consumer expectations. Strong growth potential positions Asia Pacific as a priority for global players.
Latin America
The Latin America Home Beer Brewing Machine Market size was valued at USD 2,637.3 million in 2018 to USD 3,547.6 million in 2024 and is anticipated to reach USD 7,088.4 million by 2032, at a CAGR of 9.2% during the forecast period. Latin America is emerging as a promising market due to increasing awareness of craft beer and rising lifestyle changes. Brazil remains the largest contributor, supported by a strong beer-drinking culture and rising interest in premium segments. It benefits from growing consumer inclination toward creative brewing experiences. Argentina is also showing adoption growth, supported by urban consumers seeking alternative beer styles. Regional demand is supported by younger demographics eager to explore home brewing as a social activity. Distribution partnerships are improving access to compact machines. The market faces challenges with pricing sensitivity but continues to expand steadily. Manufacturers view Latin America as an untapped opportunity with long-term potential.
Middle East
The Middle East Home Beer Brewing Machine Market size was valued at USD 1,805.4 million in 2018 to USD 2,333.1 million in 2024 and is anticipated to reach USD 4,608.3 million by 2032, at a CAGR of 9.0% during the forecast period. The market in this region is shaped by cultural and regulatory dynamics. While restrictions in some countries limit alcohol production, rising tourism and expatriate communities create demand pockets. The GCC countries lead adoption, particularly in premium segments targeting affluent consumers. It is gaining visibility through hospitality and retail channels that cater to international audiences. Israel represents another growth market with higher acceptance of craft brewing. Turkey demonstrates interest among urban consumers despite regulatory hurdles. Regional growth remains modest compared to other geographies but reflects steady niche demand. Companies are focusing on premium machines that cater to smaller, affluent consumer bases.
Africa
The Africa Home Beer Brewing Machine Market size was valued at USD 336.3 million in 2018 to USD 782.8 million in 2024 and is anticipated to reach USD 1,359.1 million by 2032, at a CAGR of 6.6% during the forecast period. Africa holds a small but gradually expanding share of the global market. South Africa leads adoption, benefiting from its strong beer culture and rising craft beer popularity. It also shows potential in Egypt, where growing urban centers are driving new consumer trends. The market faces challenges from limited disposable income and weaker distribution networks. It is gradually gaining attention from global players seeking long-term expansion. Compact and affordable brewing systems hold the strongest potential in this region. Consumer education and marketing campaigns are essential to build awareness. Despite slower growth, Africa is expected to emerge as a developing market in the longer run.
Key Player Analysis:
- BREWIE
- MINIBREW
- Shandong Zunhuang Brewing Equipment Co., Ltd.
- SPEIDEL Tank and Container Construction
- Spike Brewing
- BEERMKR
- BREWART
- Bevie
- Clawhammer Supply
Competitive Analysis:
The Home Beer Brewing Machine Market features a competitive landscape shaped by innovation, product differentiation, and consumer engagement. Leading players such as BREWIE, MINIBREW, BEERMKR, SPEIDEL, Spike Brewing, BREWART, Bevie, and Clawhammer Supply focus on expanding portfolios to meet diverse consumer needs. It is driven by strong demand for compact, automated, and user-friendly systems that attract both beginners and enthusiasts. Companies emphasize advanced features like smart connectivity, recipe customization, and sustainable designs to secure loyalty. Strategic collaborations with craft beer producers help brands strengthen credibility and market presence. Regional expansion strategies are prominent, with Asia Pacific and Latin America offering growth opportunities. Marketing efforts highlight lifestyle integration and premium brewing experiences. The competitive environment pushes firms to balance affordability with innovation to appeal to wide consumer segments. Continuous product development and targeted outreach remain central to maintaining leadership and capturing emerging demand.
Recent Developments:
- In July 2024, MiniBrew expanded its global supplier partnerships and launched new GEN 3 brewing systems with a focus on rapid delivery across Europe and non-EU countries. MiniBrew announced a collaboration with Exobrew in the USA to handle assembly and distribution for American customers, and partnered with several local shops in the Netherlands, Sweden, and Italy to offer specialized brew kits and launch an on-demand supply model for ingredient packs.
Report Coverage:
The research report offers an in-depth analysis based on Product and Mechanism. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising consumer preference for craft and personalized beer will drive stronger adoption across demographics.
- Increasing disposable income in urban regions will support investments in advanced brewing systems.
- Integration of smart connectivity and app-based controls will become a standard expectation in product design.
- Compact and space-saving machines will gain prominence due to growing urbanization and limited household space.
- Expanding middle-class populations in Asia Pacific and Latin America will create new growth opportunities.
- Collaborations between brewing machine brands and craft beer producers will enhance credibility and product diversity.
- Premiumization trends will encourage demand for full-size brewers with higher capacity and advanced customization.
- Rising e-commerce penetration will ensure wider product availability and strengthen direct-to-consumer sales.
- Sustainability concerns will push manufacturers to develop eco-friendly machines with lower energy consumption.
- Strengthened community engagement through hobbyist networks and workshops will foster long-term market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Home Beer Brewing Machines Market?
What are the key drivers of this market's growth?
Which regions are leading the Home Beer Brewing Machines Market?
Why are more people interested in home beer brewing?
Are there any emerging markets for home beer brewing machines?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Home Beer Brewing Machines Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Home Beer Brewing Machines Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 48,012.4 million → 2032: USD 1,02,167.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Home Beer Brewing Machines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Home Beer Brewing Machines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Home Beer Brewing Machines Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Home Beer Brewing Machines Market Drivers
- 3.3 Home Beer Brewing Machines Market Restraints & Challenges
- 3.4 Home Beer Brewing Machines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Home Beer Brewing Machines Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Home Beer Brewing Machines Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Home Beer Brewing Machines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Home Beer Brewing Machines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Home Beer Brewing Machines Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Home Beer Brewing Machines market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Home Beer Brewing Machines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Home Beer Brewing Machines Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Home Beer Brewing Machines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Home Beer Brewing Machines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Home Beer Brewing Machines Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Home Beer Brewing Machines Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Home Beer Brewing Machines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Home Beer Brewing Machines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Home Beer Brewing Machines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Home Beer Brewing Machines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Home Beer Brewing Machines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Home Beer Brewing Machines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Home Beer Brewing Machines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
