
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Hydraulic Fracturing Market Size 2024 | USD 50281.2 Million |
| Hydraulic Fracturing Market, CAGR | 8.00% |
| Hydraulic Fracturing Market Size 2032 | USD 50281.2 Million |
Market Insights
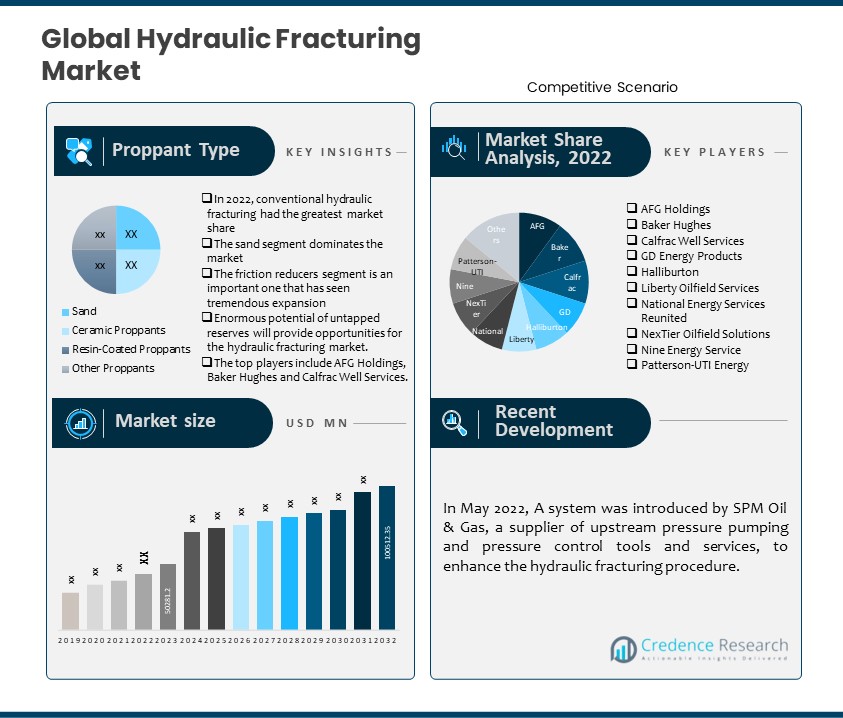
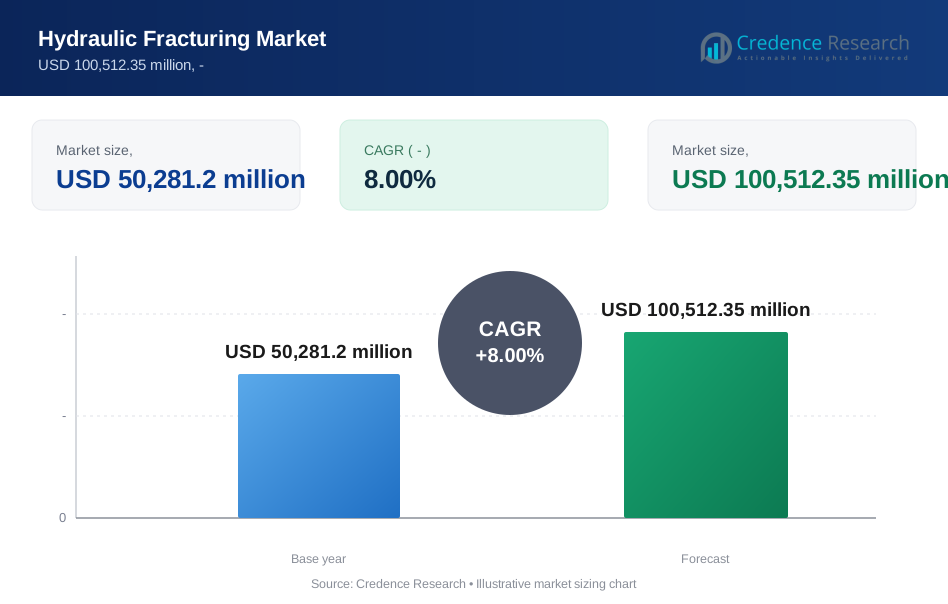
- The global market for hydraulic fracturing is expected to develop at a compound annual growth rate (CAGR) of 8.00% between 2024 and 2032, from its estimated USD 50281.2 million in 2023 to USD 100512.35 million in 2032.
- The largest category is conventional hydraulic fracturing. Horizontal hydraulic fracturing, on the other hand, is expected to grow at a strong CAGR.
- The sand category will expand at a rapid rate of growth.
- The CAGR for the friction reducers is expected to be the highest during the projection period.
- North America dominated the hydraulic fracturing market.
- Regarding the market share of hydraulic fracturing, Europe is expected to come second.
- In the hydraulic fracturing market, Asia Pacific is anticipated to grow fastest.
- The global market is expanding as a result of ongoing advancements in fracking technology, which raise its attractiveness to exploration and production firms by cutting expenses and increasing efficiency.
- Through the capture and storage of CO2 from power plants and industrial facilities, the integration of CCS technology with hydraulic fracturing operations can reduce greenhouse gas emissions and open up new market opportunities for the hydraulic fracturing industry.
Executive Summary
Market Definition
The industry that deals with extracting oil and natural gas from unconventional reservoirs like tight sandstone, shale, and coalbed methane formations is referred to as the hydraulic fracturing market or fracking. In order to create fractures in the rock formation, hydraulic fracturing entails injecting a high-pressure fluid, typically water combined with sand and chemicals, into a wellbore. The trapped hydrocarbons are released by these fractures, making it easier for them to move to the wellbore for extraction. A wide range of players are involved in the market, including suppliers of chemicals, equipment manufacturers, oil and gas companies, and drilling service providers.
Market Overview
The hydraulic fracturing sector is estimated to develop at an 8.00% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will continue to develop, rising from its estimated USD 50281.2 million in 2023 to USD 100512.35 million in 2032.
The hydraulic fracturing market has grown significantly as a result of ongoing advancements in fracking technology. The cost of hydraulic fracturing operations is declining as technology advances. The development of more effective fracking fluids and proppants, along with advances in drilling techniques and data analytics for reservoir characterization, are the primary causes of this cost reduction. Fracking becomes more economically feasible due to lower costs, which promotes more investment and market expansion. Fracking technology advancements have made it possible to extract gas and oil from unconventional reservoirs, like shale formations, more effectively. Improved well design, optimized fracturing techniques, and a deeper comprehension of geological formations are the means by which this efficiency is attained.
Furthermore, environmental issues related to the fracking process are also addressed by ongoing advancements in technology. For instance, improvements in water management and recycling help lower water use and lower the chance of contaminating groundwater. Fracking operations are also safer and more environmentally friendly thanks to advancements in well construction and monitoring technologies. The regulations governing hydraulic fracturing are getting more and more complicated. But thanks to technological advancements, businesses can now more efficiently meet these requirements without sacrificing operational effectiveness-for example, enhanced well integrity monitoring systems aid in guaranteeing adherence to environmental and safety standards.
Segmentation by Technology Type
- Conventional hydraulic fracturing is the market leader in terms of technology type. Fracking, also known as conventional hydraulic fracturing, is a method for extracting natural gas and oil from deep under the Earth's crust.
- The horizontal hydraulic fracturing category will exhibit a sizable CAGR during the projected period. Fracking, or horizontal hydraulic fracturing, is a method used in the oil and gas sector to remove hydrocarbons from underground shale rock formations. Once a particular depth is reached, horizontal drilling entails drilling horizontally as opposed to traditional vertical drilling, which descends directly into the earth.
- Other technology types, such as multi-stage hydraulic fracturing, hybrid fracturing, and enhanced fracturing technologies, also contribute to the demand for hydraulic fracturing.
Segmentation by Proppant Type
- Sand is considered the best proppant type. Sand is essential to creating and propping open fractures in shale rock. Sand particles are carried into the fractures after the rock is broken apart by the high-pressure fluid. These grains serve as proppants, keeping the fractures open after the pressure is released and facilitating a more unrestricted flow of gas or oil into the well.
- The ceramic proppants category will likely register a significant CAGR during forecasting. When it comes to durability and conductivity, ceramic proppants outperform other proppants like sand. Because of their increased longevity and productivity, wells are increasingly chosen for hydraulic fracturing operations.
- Other proppant types, such as resin-coated proppants, also contribute to the demand for hydraulic fracturing.
Segmentation by Chemical Additives
- The friction reducers category is projected to grow faster over the projection period. Chemical additives known as friction reducers are used to lessen the frictional resistance that occurs when fracturing fluids are pumped into the wellbore and through the formation. Friction can obstruct fluid flow, raising pumping pressure and energy requirements.
- Other chemical additives influence the need for hydraulic fracturing, including gelling agents, biocides, scale inhibitors, acidifiers, surfactants, breakers, and crosslinkers.
Segmentation by Region
- North America leads the hydraulic fracturing industry. Infrastructure related to hydraulic fracturing, such as pipelines, processing plants, and transportation networks, has seen significant investment in North America. The entire fracking supply chain, from extraction to distribution, is supported by this investment's robust ecosystem.
- Europe is estimated to rank second in market size for hydraulic fracturing.
- The hydraulic fracturing industry is predicted to flourish rapidly in Asia Pacific.
- Regions such as Africa, the Middle East, and Latin America cover the remaining requirement for hydraulic fracturing.
The market for hydraulic fracturing, or fracking, is, in fact, significantly influenced by the ongoing shift towards greener energy sources, such as solar and wind power. Natural gas is regarded as a "bridge" fuel between conventional fossil fuels and cleaner energy sources. It is frequently obtained through hydraulic fracturing. In comparison to coal or oil, it produces fewer greenhouse emissions when burned to generate electricity. Natural gas is seen as an essential component in the interim as nations work to reduce their carbon footprint and switch to cleaner energy. Large gas reserves that were previously unreachable in shale formations have been made accessible through hydraulic fracturing. Many nations now have greater energy security, and as a result, they are becoming less reliant on imported gas and oil. Governments are attempting to diversify their energy sources.
Based on projections, North America is anticipated to control the hydraulic fracturing market. Large reserves of tight oil and shale gas can be found throughout North America, especially in areas like the Appalachian Basin, the Bakken Formation in North Dakota, and the Permian Basin in Texas. These materials are essential to the process of fracking. Particularly when it comes to the development and improvement of fracking technology, the US has led the way. The productivity and efficiency of extracting oil and gas from shale formations have increased dramatically due to techniques like hydraulic fracturing and horizontal drilling. North America generally has a more fracking-friendly regulatory environment than many other regions. Although state and province-specific regulations differ, North America generally has a more streamlined and predictable fracking operation permitting process than other regions of the world.
Moreover, Asia Pacific is anticipated to increase at a high rate over the projection period. Significant shale gas reserves are found in the Asia Pacific area, particularly in nations like Australia and China. With hydraulic fracturing techniques, these reserves represent a valuable energy asset that can be utilized. Advances in hydraulic fracturing technology, including horizontal drilling and more effective fracturing techniques, have made it possible to extract previously unreachable shale reserves economically. The Asia Pacific hydraulic fracturing industry now has more prospects as a result of this. The Asia Pacific area, especially nations like China and India, has been rapidly industrializing and urbanizing, which has increased the demand for energy. There is a strong push towards unconventional energy sources like shale gas, which requires hydraulic fracturing, as conventional energy sources are unable to meet this demand.
Key Highlights of the Report
The global hydraulic fracturing market is segmented by technology type, proppant type, chemical additives, and region. Conventional hydraulic fracturing is the market spearhead in terms of technology type. Sand is the top category. The friction reducers category is anticipated to increase at the highest CAGR throughout the projection period. The hydraulic fracturing market is expanding mostly in North America.
There is a large opportunity for the hydraulic fracturing market when carbon capture and storage (CCS) technology is integrated with hydraulic fracturing operations. Even though hydraulic fracturing is a useful technique for obtaining natural gas and oil, it can produce large amounts of carbon emissions. Hydraulic fracturing can drastically lower its carbon footprint by utilizing CCS technology, which sequesters carbon dioxide emissions from industrial processes and stores them underground. This is imperative to meet emissions reduction targets and address environmental concerns related to hydraulic fracturing. Through the use of CCS technology, the captured carbon dioxide can be safely stored underground, keeping it from escaping into space and accelerating climate change. Lessening the effects of hydraulic fracturing operations on the environment and guaranteeing adherence to legal obligations concerning the reduction of emissions improves the sustainability of these operations.
North America is expected to account for the largest hydraulic fracturing market globally. Fracking has significantly boosted the economy in North America by creating jobs, generating income for local governments, and stimulating the local economy in areas where fracking is practiced. The region's hydraulic fracturing industry has grown even more as a result of these financial incentives. The Asia Pacific region is also assumed to have the market's sharpest growth. The hydraulic fracturing sector generates substantial economic benefits in the form of infrastructure development, employment opportunities, and tax and royalties revenue. Thus, a lot of nations in the Asia-Pacific area are eager to increase their fracking operations in order to capitalize on these advantages.
Which Key Factors Are Driving The Global Hydraulic Fracturing Market?
The hydraulic fracturing industry is expanding due to the growing focus on minimizing greenhouse gas emissions and expenditures in infrastructure, including pipelines, manufacturing plants, and transportation networks.
What Are The Main Challenges Confronting The Global Hydraulic Fracturing Market?
Volatile oil and gas prices, stringent regulations and licenses, and limited infrastructure for water supply, transportation, and wastewater disposal are the main obstacles to the sector's expansion.
What Market Opportunities Exist For Hydraulic Fracturing Globally?
The hydraulic fracturing industry may expand due to rising consumer demand for natural gas liquids (NGLs) such as ethane, propane, and others produced through the process and the adoption of creative water management techniques like recycled, treated, and repurposed water.
Market Drivers
Multiple factors propel the hydraulic fracturing industry across the globe. The primary factors propelling the global hydraulic fracturing market are as follows:
Growing Focus is being Directed Towards Increasing Present Oil and Gas Production
North American nations are constantly concentrating on utilizing state-of-the-art technologies to explore shale and other tight-rock formations within the current reserves in order to increase the productivity of crude oil from the wells that already exist. According to the American Petroleum Institute, hydraulic fracturing will be necessary in the upcoming years for up to 95% of natural gas well drilling. Moreover, Total, a global integrated oil and gas company, is stepping up its efforts to increase the output of oil and gas by submitting 200 patent applications annually to advance the technology of hydraulic fracturing, which facilitates the expansion of production. The increased emphasis on increasing the productivity of current oil wells will, therefore, propel the global market during the anticipated period.
Market Restraints
There are several obstacles that the global hydraulic fracturing market must overcome to continue growing. Among them are the following:
Strict Environmental Protection Laws and a Growing Renewable Energy Preference
The growth of this market has been hindered by the strict regulations and safety standards set by national governments and regulatory bodies, such as the Environmental Protection Agency (EPA), and the Registration, Evaluation, Authorization, and Restriction of Chemicals. Growing environmental consciousness in both developed and developing nations had impeded market expansion. The hydrocarbon business is likely to suffer from the growing trend of using renewable energy as a clean energy source. Globally, renewable energy production was predicted to increase from 190.9 GW in 2019 to 196.1 GW in 2021, according to IEA data. The hydraulic system is restrained by regulatory prohibitions against hydraulic fracturing and increased adoption of renewable energy from several regional countries, including France, Russia, and Bulgaria.
Opportunities
There are plenty of potential prospects in the global hydraulic fracturing industry. Among these are the following:
Foams' Capacity To Provide Waterless Fracturing
Foams are highly advantageous due to their low liquid content and high viscosity, and they are used in a wide range of petroleum industry processes. By using less water than conventional fracturing techniques, they provide a good substitute, resolving environmental issues related to fracturing operations. A considerable amount of water (approximately 89%) is used during the fracture process during well drilling. This presents a chance for businesses to include waterless fracking solutions into their products and increase their market share. A large internal volume (55–95%) is dispersed through the liquid phase to prepare foams, with a typical formation temperature of 90°F (32.2°C). Gases like N2 or CO2 are typically present in the internal phase. These factors create opportunities for the global market.
Competitive Landscape
Key Players
Several major competitors exist in the fiercely competitive global hydraulic fracturing market. The following are a few of the leading market participants and their market shares:
- AFG Holdings
- Baker Hughes
- Calfrac Well Services
- GD Energy Products
- Halliburton
- Liberty Oilfield Services
- National Energy Services Reunited
- NexTier Oilfield Solutions
- Nine Energy Service
- Patterson-UTI Energy
- Petro Welt Technologies
- ProFrac Holding
- ProPetro Holding
- Schlumberger
- STEP Energy Services
- Tacrom
- TAM International
- Others
These companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions to remain competitive.
The largest suppliers in the global hydraulic fracturing market continuously work to stay one step ahead of the competition by developing innovative concepts and products.
In June 2023, A definitive merger agreement has been reached by NexTier Oilfield Solutions and Patterson-UTI Energy, Inc. to merge in an all-stock merger of equals. The combined business will operate in the busiest major U.S. basins and be a market leader in the drilling and completions services sector.
In January 2023, REV Energy Holdings, LLC ("REV"), a privately held provider of pressure pumping services with operations in the Rockies and Eagle Ford, was acquired by ProFrac Holding Corp. For REV, ProFrac spent $140 million. ProFrac will become more prevalent in the Rockies and South Texas as a result of the acquisition.
In January 2022, Producers Services Holdings LLC, a provider of pressure pumping services to the Mid-Continent and Appalachia, was purchased by ProFrac. Per the terms of the agreement, ProFrac acquired Producers for a total transaction value of approximately $35 million.
Summary of Key Findings
- The hydraulic fracturing industry is supported by investments made in infrastructure, such as transportation networks, processing centers, and pipelines.
- The market is segmented by technology type, proppant type, chemical additives, and region.
- In the market, conventional hydraulic fracturing is the most widely used technology type.
- Sand is the foremost category.
- The friction reducers industry is expected to grow fastest in terms of CAGR during the forecast period.
- North America is leading market development; the market is highly competitive with key players including AFG Holdings, Baker Hughes, Calfrac Well Services, GD Energy Products, Halliburton, Liberty Oilfield Services, National Energy Services Reunited, NexTier Oilfield Solutions, Nine Energy Service, Patterson-UTI Energy, Petro Welt Technologies, ProFrac Holding, ProPetro Holding, Schlumberger, STEP Energy Services, Tacrom, TAM International, and Others.
Future Outlook
- The hydraulic fracturing industry is expected to increase significantly in North America, and its outlook is positive worldwide.
- Optimizing supply chain logistics, inventory control, and procurement procedures makes hydraulic fracturing operations more efficient and cost-effective, propelling the hydraulic fracturing market.
- Fluctuations in the price of gas and oil affect hydraulic fracturing projects' economic viability, which limits the expansion of the global market.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Hydraulic Fracturing Market Report
CXOs may get a detailed picture of the market in the Credence Research Hydraulic Fracturing Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the global hydraulic fracturing market size, segmented by technology type, proppant type, chemical additives, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for hydraulic fracturing into segments based on technology type, proppant type, chemical additives, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the hydraulic fracturing industry, including information on their business plans, product lines, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the hydraulic fracturing market. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Hydraulic Fracturing Market Report to:
- Identify growth opportunities: This analysis may help CXOs identify new growth opportunities in the hydraulic fracturing sector. For example, the report identifies the growing demand for hydraulic fracturing from the shale gas industry as a key opportunity.
- Make informed investment decisions: The report helps CXOs make wise choices regarding hydraulic fracturing. For example, the research study provides information on the critical factors to consider when selecting hydraulic fracturing solutions and evaluating suppliers.
- Develop competitive strategies: CXOs can use the research report to develop competitive strategies for their hydraulic fracturing businesses. For example, the research paper outlines the main strategies that hydraulic fracturing suppliers utilize to differentiate themselves from competitors.
- Track market developments: This research report may help CXOs stay ahead of the curve by tracking market developments. For instance, it offers insights into the most recent developments and trends in the hydraulic fracturing market.
CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Hydraulic Fracturing Market Report useful.
Segmentation
- By Technology Type
- Conventional Hydraulic Fracturing
- Horizontal Hydraulic Fracturing
- Multi-Stage Hydraulic Fracturing
- Hybrid Fracturing
- Enhanced Fracturing Technologies
- By Proppant Type
- Sand
- Ceramic Proppants
- Resin-Coated Proppants
- Other Proppants
- By Chemical Additives
- Friction Reducers
- Gelling Agents
- Biocides
- Scale Inhibitors
- Acidifiers
- Surfactants
- Breakers
- Crosslinkers
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Fracking Technology
Continuous improvements in hydraulic fracturing techniques, such as horizontal drilling and enhanced proppant materials, have reduced operational costs and increased extraction efficiency, making fracking more economically viable and attractive to oil and gas producers.
Expansion of Unconventional Oil & Gas Reserves
The ability to access and economically extract hydrocarbons from unconventional reservoirs, such as shale and tight sandstone, has significantly expanded the addressable market for hydraulic fracturing, especially in regions with large untapped reserves.
Integration of Carbon Capture and Storage (CCS)
The adoption of CCS technologies alongside hydraulic fracturing operations is opening new market opportunities by addressing environmental concerns and regulatory requirements, enabling operators to reduce greenhouse gas emissions and improve sustainability.
Infrastructure Investments in Key Regions
Significant investments in pipelines, processing plants, and transportation networks, particularly in North America, have created a robust ecosystem that supports the growth and scalability of hydraulic fracturing operations.
Rising Demand for Natural Gas Liquids (NGLs)
Increasing consumption of NGLs such as ethane and propane, which are produced through hydraulic fracturing, is driving additional demand for fracking services as these products are essential feedstocks for the petrochemical industry.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for hydraulic fracturing?
What is the hydraulic fracturing market's projected growth rate between 2024 and 2032?
In terms of technology type, which market category is leading?
Which chemical additives segment is estimated to have the highest CAGR throughout the forecast period?
Who are the main players in the global hydraulic fracturing industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Proppant Type
- 1.2.1 Sand
- 1.2.2 Ceramic Proppants
- 1.2.3 Resin-Coated Proppants
- 1.2.4 Other Proppants
- 1.3 By Technology Type
- 1.3.1 Conventional Hydraulic Fracturing
- 1.3.2 Horizontal Hydraulic Fracturing
- 1.3.3 Multi-Stage Hydraulic Fracturing
- 1.3.4 Hybrid Fracturing
- 1.3.5 Enhanced Fracturing Technologies
- 1.4 By Chemical Additives
- 1.4.1 Friction Reducers
- 1.4.2 Gelling Agents
- 1.4.3 Biocides
- 1.4.4 Scale Inhibitors
- 1.4.5 Acidifiers
- 1.4.6 Surfactants
- 1.4.7 Breakers
- 1.4.8 Crosslinkers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 50,281.2 million → 2032: USD 100,512.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hydraulic Fracturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hydraulic Fracturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hydraulic Fracturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hydraulic Fracturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hydraulic Fracturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hydraulic Fracturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hydraulic Fracturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hydraulic Fracturing Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 50,281.2 million → 2032: USD 100,512.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hydraulic Fracturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Proppant Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sand
- 12.3.7.2 Ceramic Proppants
- 12.3.7.3 Resin-Coated Proppants
- 12.3.7.4 Other Proppants
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional Hydraulic Fracturing
- 12.4.7.2 Horizontal Hydraulic Fracturing
- 12.4.7.3 Multi-Stage Hydraulic Fracturing
- 12.4.7.4 Hybrid Fracturing
- 12.4.7.5 Enhanced Fracturing Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Chemical Additives - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Friction Reducers
- 12.5.7.2 Gelling Agents
- 12.5.7.3 Biocides
- 12.5.7.4 Scale Inhibitors
- 12.5.7.5 Acidifiers
- 12.5.7.6 Surfactants
- 12.5.7.7 Breakers
- 12.5.7.8 Crosslinkers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hydraulic Fracturing Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hydraulic Fracturing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hydraulic Fracturing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Halliburton
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Schlumberger
- 17.4 Baker Hughes
- 17.5 Liberty Oilfield Services
- 17.6 Calfrac Well Services
- 17.7 ProFrac Holding
- 17.8 NexTier Oilfield Solutions
- 17.9 Patterson-UTI Energy
- 17.10 ProPetro Holding
- 17.11 STEP Energy Services
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

