
Market Overview
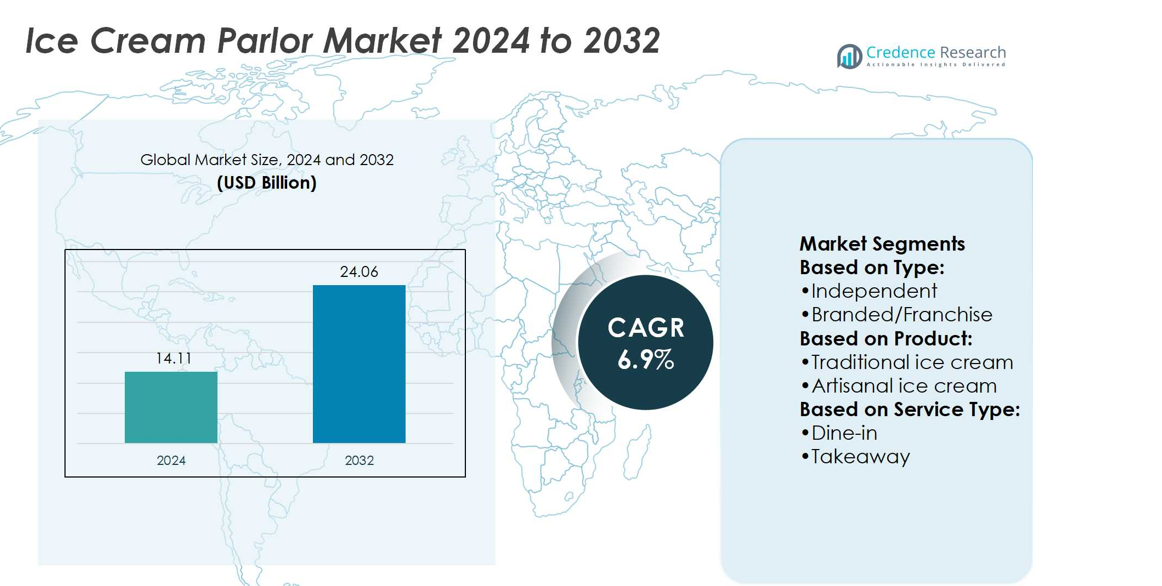
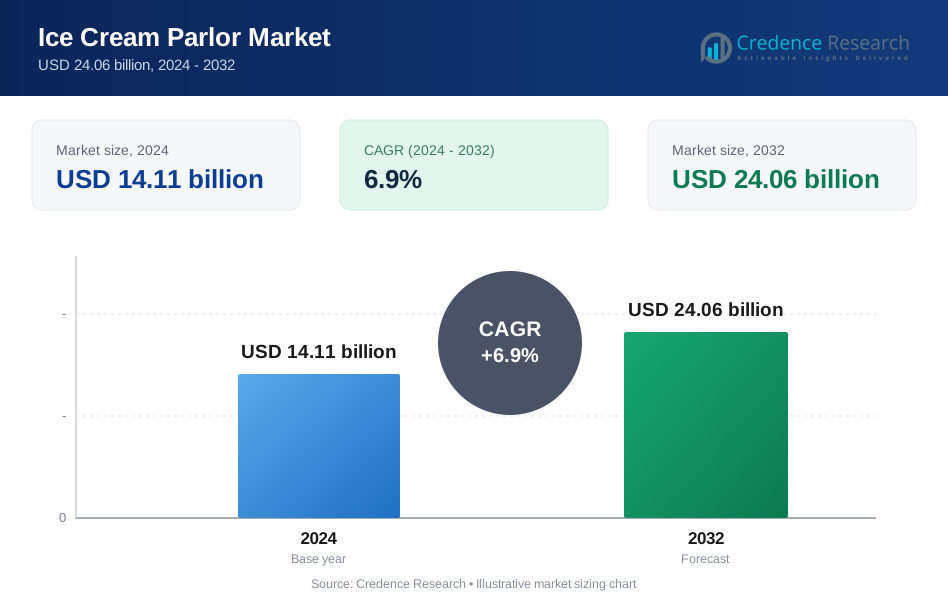
Ice Cream Parlor Market size was valued at USD 14.11 billion in 2024 and is anticipated to reach USD 24.06 billion by 2032, at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ice Cream Parlor Market Size 2024 | USD 14.11 billion |
| Ice Cream Parlor Market, CAGR | 6.9% |
| Ice Cream Parlor Market Size 2032 | USD 24.06 billion |
The Ice Cream Parlor Market grows through strong consumer demand for premium, artisanal, and health-oriented offerings. Rising disposable incomes, urban lifestyles, and social dining preferences drive steady expansion. Parlors adapt to dietary shifts with plant-based, low-sugar, and functional varieties while leveraging experiential formats like customization and nitrogen-infused desserts to attract younger demographics. Digital platforms, delivery services, and loyalty programs enhance accessibility and engagement. Seasonal menus and limited-edition flavors boost repeat visits, while sustainability initiatives influence operations. Together, these drivers and trends position ice cream parlors as dynamic, experience-focused destinations catering to evolving global consumer expectations.
The Ice Cream Parlor Market shows strong geographical diversity, with Asia Pacific leading due to urbanization and rising incomes, followed by Europe’s artisanal traditions and North America’s established franchise presence. Latin America and the Middle East & Africa present emerging opportunities driven by retail expansion and tourism. Key players such as Baskin-Robbins, Ben & Jerry’s, Cold Stone Creamery, Dairy Queen, Haagen-Dazs, Breyers, Blue Bell Creameries, Carvel, Graeter’s Ice Cream, and Ghirardelli Ice Cream and Chocolate Shop shape competition through innovation, branding, and expansion strategies.
Market Insights
- The Ice Cream Parlor Market size was valued at USD 14.11 billion in 2024 and is expected to reach USD 24.06 billion by 2032, at a CAGR of 6.9%.
- Rising disposable incomes, premium demand, and evolving dining preferences drive consistent market growth.
- Trends highlight plant-based, low-sugar, and functional ice creams alongside experiential formats like nitrogen-infused desserts.
- Competition remains strong, with global and regional players focusing on innovation, branding, and franchise expansion.
- High operational costs, supply chain disruptions, and seasonal demand patterns act as market restraints.
- Asia Pacific leads through rapid urbanization, Europe thrives on artisanal traditions, and North America holds strong franchise presence, while Latin America and Middle East & Africa present emerging opportunities.
- Seasonal menus, digital ordering, delivery services, and sustainability practices enhance customer engagement and shape long-term industry growth.
Market Drivers
Rising Consumer Demand for Premium and Artisanal Flavors
The Ice Cream Parlor Market benefits from rising consumer preference for unique, high-quality flavors. Shoppers seek artisanal options, natural ingredients, and indulgent textures. It is driven by the shift from mass-market products to personalized experiences. Premium offerings such as organic, vegan, and locally sourced varieties increase customer loyalty. Seasonal menus and limited-edition flavors also attract repeat visits. This demand for exclusivity continues to strengthen overall market growth.
- For instance, Each French Pot batch takes about 15-20 minutes of freezing in a salt water bath held at around –20 °F, during which blades scrape frozen product from the sides of the pot to maintain density and texture.
Influence of Lifestyle Shifts and Social Experience
Changing lifestyles encourage consumers to treat ice cream parlors as social hubs. Families and young adults view parlors as casual dining and leisure spaces. It gains traction through ambiance, interior design, and community-driven marketing. Enhanced in-store experiences create strong customer engagement and longer visits. Interactive elements like self-serve toppings and customizable sundaes expand appeal. Such positioning drives consistent customer traffic and brand differentiation.
- For instance, Carvel created a first-of-its-kind billboard in Manhattan fitted with a soft-serve dispenser. That installation served more than 50 gallons of soft serve, yielding about 1,500 servings over a seven-hour period.
Expansion of Quick-Service and Franchised Outlets
The Ice Cream Parlor Market grows through rapid expansion of franchise models and quick-service outlets. It leverages standardized menus and brand recognition to capture wider audiences. Franchise partnerships lower entry barriers for entrepreneurs, supporting steady market penetration. Well-known chains dominate high-footfall urban and suburban zones. Strong supply chain networks ensure consistency across multiple outlets. This model helps brands scale efficiently while meeting consumer demand.
Innovation in Product Formats and Dietary Alternatives
Product innovation plays a vital role in market expansion. The Ice Cream Parlor Market adapts to dietary trends with low-sugar, plant-based, and lactose-free options. It integrates functional ingredients like probiotics and protein to attract health-conscious consumers. Creative formats such as rolled, nitrogen-infused, or fusion desserts enhance novelty. Technology supports consistency in texture and flavor delivery across outlets. These innovations broaden appeal, making parlors relevant to diverse demographics.
Market Trends
Growing Demand for Plant-Based and Functional Varieties
The Ice Cream Parlor Market experiences a rising trend toward plant-based and functional alternatives. It caters to lactose-intolerant and vegan consumers through dairy-free and natural ingredient options. Functional varieties include protein-rich, probiotic, and low-calorie formats designed for health-conscious buyers. Parlors introduce superfoods like matcha, chia, or acai into their offerings. Such innovations appeal to customers balancing indulgence with nutrition. This trend reflects the shift toward healthier dessert choices while sustaining indulgence appeal.
- For instance, Haagen-Dazs responded to plant-based demand by launching an oat-based frozen dessert line in Canada. Each tub in that line is 400 ml in volume. They use oats for creaminess and pea protein as the protein source in those plant-based recipes.
Emphasis on Customization and Experiential Formats
Customers increasingly seek personalized experiences within parlors. The Ice Cream Parlor Market adopts interactive formats like self-serve counters, customizable toppings, and themed sundaes. It creates opportunities for consumers to engage directly in the dessert-making process. Innovative presentation formats such as nitrogen-infused or rolled ice cream strengthen novelty appeal. The focus on unique customer experiences helps parlors stand out in competitive urban markets. This trend supports higher consumer loyalty and social media-driven brand awareness.
- For instance, Baskin-Robbins stores have installed remote sensors and WiFi-thermostats to monitor walk-in freezer temperatures. The sensors check if temperatures rise above –10 °F to –20 °F, sending alerts via mobile app to prevent spoilage.
Integration of Digital Platforms and Delivery Services
Technology adoption shapes modern ice cream parlors. The Ice Cream Parlor Market integrates online ordering, mobile apps, and third-party delivery platforms to expand reach. It ensures convenience for customers seeking premium desserts at home. Loyalty programs embedded in mobile platforms increase repeat purchases and data-driven personalization. Social media promotions and influencer collaborations also boost visibility. This digital integration enhances brand accessibility across both local and global markets.
- For instance, Blue Bell also reinstated Homemade in the Shade, which pairs Homemade Vanilla ice cream with hot fudge sauce swirl. This flavor had been off shelves for about 10 years, returning and offered in the same two sizes: pint and half-gallon.
Expansion of Seasonal and Limited-Edition Offerings
Seasonal menus and exclusive launches gain strong traction among younger demographics. The Ice Cream Parlor Market uses limited-time flavors tied to festivals, holidays, or regional traditions. It stimulates repeat visits by offering fresh and unique experiences. Collaborations with confectionery brands and local suppliers add novelty to menus. Seasonal flavors create anticipation and strengthen consumer engagement cycles. This trend sustains excitement and positions parlors as dynamic, experience-driven destinations.
Market Challenges Analysis
Rising Operational Costs and Supply Chain Pressures
The Ice Cream Parlor Market faces challenges from fluctuating costs of raw materials and utilities. It struggles with high prices of dairy, plant-based ingredients, and premium flavoring agents. Seasonal demand variations further complicate inventory planning and cost management. Energy expenses related to refrigeration and storage increase operational strain. Supply chain disruptions also impact timely sourcing of specialty products. These pressures limit profit margins, particularly for smaller and independent parlors. Businesses must adapt through efficient sourcing and waste reduction strategies.
Intense Competition and Shifting Consumer Preferences
The Ice Cream Parlor Market encounters rising competition from global chains, quick-service restaurants, and artisanal startups. It must balance traditional offerings with modern dietary demands like low-sugar or vegan options. Rapidly changing consumer tastes create challenges in product development and menu planning. Limited differentiation reduces customer loyalty in saturated urban markets. High expectations for experiential formats demand constant investment in innovation and marketing. These conditions make long-term growth difficult for less capitalized players. Parlors need strategic positioning to maintain relevance in a dynamic landscape.
Market Opportunities
Expansion Through Health-Oriented and Premium Offerings
The Ice Cream Parlor Market holds strong opportunities in health-focused and premium product categories. It can leverage rising demand for plant-based, low-fat, and functional ice cream varieties. Introducing options fortified with protein, probiotics, or natural sweeteners attracts health-conscious consumers. Premium positioning through organic ingredients, artisanal flavors, and indulgent textures supports higher margins. Growing interest in gourmet and exotic flavors also creates differentiation in competitive markets. This opportunity aligns with evolving dietary preferences while enhancing brand loyalty.
Growth Potential in Emerging Markets and Digital Channels
Emerging economies present significant room for parlor expansion. The Ice Cream Parlor Market can benefit from increasing disposable income and urbanization in Asia, Latin America, and the Middle East. It gains further reach through digital platforms offering online ordering, delivery, and loyalty programs. Collaborations with e-commerce and food delivery companies expand accessibility to new customers. Targeted marketing through social media enhances visibility and engagement with younger demographics. This multi-channel growth opportunity strengthens brand presence and supports sustainable expansion.
Market Segmentation Analysis:
By Type
The Ice Cream Parlor Market divides into independent outlets and branded/franchise formats. Independent parlors dominate in local communities by offering unique flavors and personalized experiences. It appeals to consumers seeking authenticity and artisanal creations, often tied to regional tastes. Branded and franchise outlets show strong growth due to standardized operations, wide reach, and consistent product quality. Global chains leverage supply chain efficiency and marketing power to expand rapidly across urban and suburban markets. Both formats play distinct roles, with independents driving innovation and franchises ensuring scalability.
- For instance, Dairy Queen operates more than 4,100 locations in the United States as of mid-2025. These locations include various formats-from Grill & Chill restaurants to traditional soft-serve only shops.
By Product
Traditional ice cream remains the most widely consumed product category. It sustains demand through familiar flavors, affordability, and wide consumer acceptance. The Ice Cream Parlor Market also experiences rising interest in artisanal ice cream. It attracts premium buyers with natural ingredients, seasonal fruits, and creative recipes. Artisanal formats highlight freshness and indulgence, driving strong traction in urban and affluent areas. This dual demand balances mass-market appeal with a growing segment of discerning consumers.
- For instance, Ben & Jerry’s non-dairy portfolio has grown from 1 flavour to 20 non-dairy flavours globally since its first non-dairy launch. A Ben & Jerry's flavor guru confirmed that 70 different formulations were tested to develop the new oat base.
By Service Type
Service formats shape customer engagement and revenue models. Dine-in service remains a core driver, as parlors position themselves as social and leisure spaces. It provides an experiential setting where ambiance and presentation enhance value. Takeaway services continue to expand, fueled by consumer demand for convenience and on-the-go indulgence. Combined service formats integrate both models, allowing outlets to capture diverse customer preferences. The Ice Cream Parlor Market benefits from this flexibility, enabling parlors to adapt to varying consumer lifestyles and regional demand. This segmentation strengthens the industry’s ability to serve both traditional and modern consumption patterns.
Segments:
Based on Type:
- Independent
- Branded/Franchise
Based on Product:
- Traditional ice cream
- Artisanal ice cream
Based on Service Type:
- Dine-in
- Takeaway
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for nearly 20% of the Ice Cream Parlor Market. The United States drives most of this share, supported by strong demand for branded franchise outlets and well-established premium chains. Canada and Mexico add to the region’s contribution, where consumer interest in convenience and indulgence remains strong. It benefits from advanced cold chain infrastructure and the growing popularity of digital ordering platforms. Health-oriented innovations such as plant-based and low-sugar ice creams continue to gain traction across the region. Competition is intense, with both global chains and local independents serving diverse customer preferences. Market maturity limits the overall growth rate, but innovation and premiumization sustain steady expansion.
Europe
Europe holds roughly 30% of the market, making it one of the largest regional contributors. Italy, France, Germany, Spain, and the UK dominate sales, reflecting the region’s deep-rooted traditions in gelato and artisanal dessert culture. The Ice Cream Parlor Market in Europe benefits from consumer preference for high-quality, natural, and organic ingredients. It also faces evolving regulations on sugar and additives, which drive the launch of healthier alternatives. Independent parlors thrive alongside well-known chains, often emphasizing locally sourced products and seasonal menus. Tourism further supports demand, particularly in Mediterranean countries where ice cream is integral to leisure dining. Growth is steady, and Europe continues to serve as a hub for innovation in artisanal ice cream.
Asia Pacific
Asia Pacific leads the global market with approximately 40% share, reflecting its large consumer base and fast-growing economies. China, India, Japan, and South Korea are major growth engines, with rising disposable income and rapid urbanization fueling demand. The Ice Cream Parlor Market here thrives on flavor experimentation and premium positioning. Younger demographics drive traffic to parlors offering novelty, customization, and experiential dining. Franchises and global chains expand quickly in tier-1 and tier-2 cities, while local parlors adapt menus to regional tastes. Digital integration through mobile apps and food delivery platforms further boosts accessibility. Asia Pacific remains the fastest-growing regional market and is expected to retain its dominance through the forecast period.
Latin America
Latin America contributes close to 6% of the Ice Cream Parlor Market. Brazil and Mexico lead the region, supported by growing middle-class spending and expansion of retail infrastructure. Independent parlors are widespread, often family-run and offering localized flavors suited to cultural preferences. It faces challenges with cold chain logistics and fluctuating input costs, but rising demand continues to push the market forward. Seasonal demand peaks during summer months, boosting sales in tourist-heavy areas. International franchises are gradually entering, bringing standardized menus and wider visibility. Latin America is still a small share of the global market, but it shows steady growth potential.
Middle East & Africa
The Middle East and Africa together account for nearly 4% of the market. The UAE, Saudi Arabia, and South Africa are the leading countries where urbanization and rising disposable incomes fuel expansion. Tourism and the growth of modern shopping malls provide high visibility for ice cream parlors in this region. It benefits from increasing demand for premium and international dessert experiences, with franchises gaining strong traction. Independent parlors continue to play a role, offering locally inspired flavors that appeal to cultural preferences. Cold chain infrastructure and operational costs remain challenges, but rising consumer interest ensures growth opportunities. The region, though small in share, shows promising expansion over the coming years.
Key Player Analysis
- Cold Stone Creamery
- Graeter’s Ice Cream
- Carvel
- Haagen-Dazs
- Baskin-Robbins
- Blue Bell Creameries
- Dairy Queen
- Breyers
- Ben & Jerry’s
- Ghirardelli Ice Cream and Chocolate Shop
Competitive Analysis
The Ice Cream Parlor Market companies include Baskin-Robbins, Ben & Jerry’s, Blue Bell Creameries, Breyers, Carvel, Cold Stone Creamery, Dairy Queen, Ghirardelli Ice Cream and Chocolate Shop, Graeter’s Ice Cream, and Haagen-Dazs. The Ice Cream Parlor Market remains highly competitive, shaped by evolving consumer preferences, innovative product development, and expanding service formats. Brands compete through strategies that emphasize premium flavors, artisanal quality, and healthier alternatives such as low-sugar or plant-based offerings. Strong franchise networks and local independents both play vital roles in maintaining market presence, with the former focusing on scalability and the latter on uniqueness and personalization. Digital integration through online ordering, delivery platforms, and loyalty programs strengthens customer engagement. Seasonal menus, experiential dining, and creative formats like nitrogen-infused or rolled ice cream further enhance differentiation. The market continues to see intense rivalry, pushing companies to innovate continuously and expand across diverse regional markets.
Recent Developments
- In February 2024, Unilever partnered with leading precision fermentation innovator Perfect Day to launch Breyers Lactose-Free Chocolate, which is composed of Perfect Day dairy protein from fermentation in the U.S.
- In 2023, Baskin-Robbins reopened its outlet in Bay City, Michigan. The store closed and was looking for new owners. Since its reopening, the business has seen massive growth and customer demand.
- In June 2023, Ben & Jerry’s came together with The Entrepreneurial Refugee Network (TERN) to craft a fresh flavor called Sunny Honey Home. This unique blend is specifically designed to raise funds and provide support for the entrepreneurial endeavors of refugees in the UK.v
- In February 2023, Cold Stone Creamery, in collaboration with Reese, launched Reese-inspired ice creams like Reese’s Take 5 peanut butter ice cream and Reese’s Peanut Butter Cup ice cream. The company also launched marshmallow-flavored ice cream.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Service Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Ice Cream Parlor Market will expand through rising demand for premium and artisanal flavors.
- Health-conscious consumers will drive growth in plant-based, low-sugar, and functional ice cream options.
- Franchise models will strengthen global reach with standardized offerings and efficient supply chains.
- Independent parlors will continue to thrive by offering unique, locally inspired flavors.
- Digital ordering, mobile apps, and delivery services will shape future consumer engagement.
- Seasonal and limited-edition menus will create recurring demand and repeat customer visits.
- Experiential formats such as customizable sundaes and nitrogen-infused ice cream will gain popularity.
- Urbanization and rising disposable incomes in emerging markets will fuel regional expansion.
- Sustainability and eco-friendly packaging will become a priority for parlor operators.
- Continuous innovation in flavors, formats, and customer experiences will sustain competitive growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Premium and Artisanal Flavor Demand
Consumers are increasingly seeking unique, high-quality, and artisanal ice cream experiences, driving parlors to innovate with natural ingredients, seasonal menus, and exclusive flavors that foster customer loyalty and repeat visits.
Lifestyle Shifts and Social Dining
Ice cream parlors are evolving into social hubs, attracting families and young adults who value ambiance, customization, and experiential formats, which increases foot traffic and enhances brand differentiation.
Expansion of Franchise and Quick-Service Models
The rapid growth of branded and franchise outlets, supported by standardized menus and strong supply chains, enables wider market penetration and scalability, especially in urban and suburban areas.
Innovation in Dietary Alternatives
Rising health consciousness is pushing parlors to offer plant-based, low-sugar, and functional ice cream varieties, broadening their appeal to vegan, lactose-intolerant, and health-focused consumers.
Digital Integration and Delivery Services
The adoption of online ordering, mobile apps, and third-party delivery platforms is making premium ice cream more accessible, increasing customer engagement and expanding the market beyond traditional dine-in experiences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ice Cream Parlor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ice Cream Parlor Market projected to grow between 2025 and 2032?
Which Ice Cream Parlor Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ice Cream Parlor Market?
Who are the leading companies in the Ice Cream Parlor Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Independent
- 1.2.2 Branded/Franchise
- 1.3 By Product
- 1.3.1 Traditional ice cream
- 1.3.2 Artisanal ice cream
- 1.4 By Service Type
- 1.4.1 Dine-in
- 1.4.2 Takeaway
- 1.4.3 Combined
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14.11 billion → 2032: USD 24.06 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ice Cream Parlor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ice Cream Parlor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ice Cream Parlor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ice Cream Parlor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ice Cream Parlor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ice Cream Parlor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ice Cream Parlor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ice Cream Parlor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14.11 billion → 2032: USD 24.06 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ice Cream Parlor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Independent
- 12.3.7.2 Branded/Franchise
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Traditional ice cream
- 12.4.7.2 Artisanal ice cream
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Dine-in
- 12.5.7.2 Takeaway
- 12.5.7.3 Combined
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ice Cream Parlor Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Ice Cream Parlor Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Ice Cream Parlor Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Baskin-Robbins
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Ben & Jerry’s
- 17.4 Cold Stone Creamery
- 17.5 Dairy Queen
- 17.6 Haagen-Dazs
- 17.7 Breyers
- 17.8 Blue Bell Creameries
- 17.9 Carvel
- 17.10 Graeter’s Ice Cream
- 17.11 Ghirardelli Ice Cream and Chocolate Shop
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

