
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ice Maker Market Size 2024 | USD 5325.53 million |
| Ice Maker Market, CAGR | 3.8% |
| Ice Maker Market Size 2032 | USD 7176.9 million |
Market Overview:
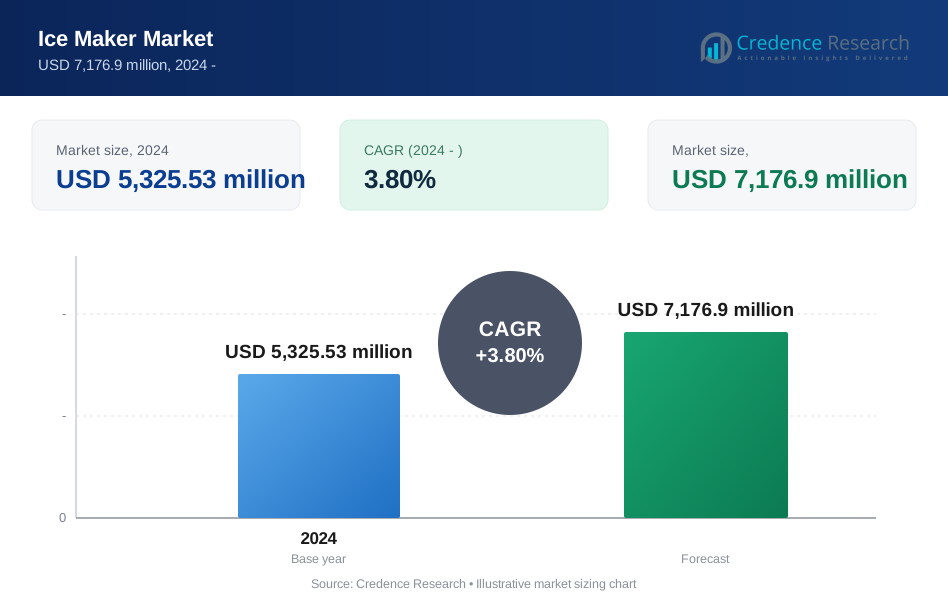
Ice Maker Market size was valued at USD 5325.53 million in 2024 and is anticipated to reach USD 7176.9 million by 2032, at a CAGR of 3.8% during the forecast period (2024-2032).
The market growth is primarily driven by increasing demand from the food and beverage industry, where consistent and hygienic ice supply is essential for preservation, presentation, and service. The healthcare sector also plays a vital role, requiring ice for temperature-sensitive pharmaceuticals and patient care. Growing urbanization, changing consumer lifestyles, and rising disposable incomes support increased demand for ice makers in residential and commercial settings. In addition, the surge in quick-service restaurants (QSRs), cafes, and convenience stores fuels the requirement for reliable and high-capacity ice-making machines. The integration of smart sensors and IoT-enabled controls enhances operational efficiency and attracts tech-savvy consumers. Regulatory focus on food safety and hygiene further emphasizes the need for high-quality ice production systems.
Regionally, North America leads the Ice Maker Market due to its well-established foodservice industry, widespread adoption in healthcare institutions, and a strong presence of key manufacturers. Europe follows closely, driven by increasing hospitality investments and growing demand for energy-efficient appliances. The Asia Pacific region is expected to witness the highest growth rate during the forecast period, supported by rising urban populations, expanding commercial infrastructure, and increased consumer spending on convenience appliances. Government initiatives to improve cold chain logistics support regional demand. Rapid digitalization of retail and hospitality services further accelerates product penetration in emerging economies.
Market Insights:
- The Ice Maker Market was valued at USD 5,325.53 million in 2024 and is expected to reach USD 7,176.9 million by 2032, driven by growing demand across foodservice, healthcare, and residential sectors.
- Increasing need for clean and consistent ice in restaurants, bars, and hotels fuels demand for high-capacity, hygienic ice makers.
- Hospitals, clinics, and laboratories adopt ice machines for temperature-sensitive storage, patient recovery, and infection control.
- Rising urbanization, modern housing trends, and lifestyle shifts promote residential use of compact and portable ice makers.
- Energy-efficient technologies, smart controls, and IoT-enabled features enhance machine performance and attract tech-savvy consumers.
- North America holds 38% of the market share due to strong foodservice infrastructure and healthcare adoption; Europe follows with 28% led by sustainability initiatives.
- Asia Pacific, with a 23% market share, is set to grow fastest due to urban development, rising consumer spending, and expanding retail and hospitality sectors.
Market Drivers:
Rising Demand from Foodservice and Hospitality Sectors Strengthens Market Potential:
The Ice Maker Market gains strong momentum from the expanding foodservice and hospitality sectors. Restaurants, hotels, catering businesses, and event venues increasingly require reliable, hygienic ice production systems to meet operational needs. Ice is essential for food presentation, beverage service, and safe storage. The growing popularity of cold beverages, cocktails, and buffet service formats further boosts demand for high-capacity ice makers. Tourism recovery and hotel refurbishments worldwide drive equipment upgrades across commercial kitchens. It benefits from vendors offering versatile machines that meet varied volume and cube-type preferences in the hospitality space.
Healthcare and Pharmaceutical Applications Stimulate Equipment Adoption:
Healthcare institutions significantly contribute to demand in the Ice Maker Market. Hospitals, laboratories, and clinics require ice for storing organs, medicines, and temperature-sensitive biological samples. It supports infection control and therapeutic treatments, where patient safety and hygiene are critical. The expansion of diagnostic labs and blood banks reinforces the need for consistent ice supply. Demand for nugget and flake ice types has increased in these settings due to ease of handling and surface contact. The market responds by offering specialized models compliant with healthcare-grade standards and cooling precision.
- For instance, Empire Cooler Service is recognized for supplying medical-grade ice machines that adhere to stringent sanitation and operational requirements in healthcare facilities.
Urbanization and Changing Lifestyles Expand Residential Demand:
The growing urban middle class and evolving consumer lifestyles positively influence the Ice Maker Market. Rising disposable incomes and an increased focus on home comfort drive interest in portable and under-counter ice machines. Consumers value convenience, quick service, and stylish kitchen appliances. Premium home designs integrate modular refrigeration and ice-making units to support hosting and self-service. It attracts demand from high-rise apartments, co-living spaces, and vacation homes. Manufacturers respond by developing compact, user-friendly models with smart features and aesthetic appeal.
- For instance, in the United States, consumer preferences for automated appliances have led to the popularity of smart ice makers offering features like remote operation via mobile apps and energy-saving modes, aligning with the growing trend of connected home devices.
Technological Advancements and Energy Efficiency Accelerate Market Growth:
Product innovation remains a critical driver for the Ice Maker Market. Manufacturers introduce energy-efficient systems that reduce electricity and water consumption without compromising output. Self-cleaning technologies and antimicrobial surfaces address hygiene concerns. Smart controls, app-based monitoring, and automated diagnostics improve operational visibility. It supports commercial users in managing uptime, service schedules, and compliance requirements. Evolving regulatory standards on appliance efficiency and food safety create incentives to adopt next-generation ice makers across end-user segments.
Market Trends:
Smart Technologies and IoT Integration Enhance Product Functionality:
Smart features are reshaping product development in the Ice Maker Market. Manufacturers incorporate IoT-enabled controls, remote diagnostics, and automated cleaning cycles to improve performance and reduce maintenance. It helps commercial users monitor usage patterns, detect malfunctions early, and schedule timely servicing. Touchscreen interfaces, programmable settings, and app-based control options make machines more user-friendly and efficient. These features align with rising customer expectations for convenience and digital control. Energy-saving technologies, such as variable-speed compressors and insulated storage systems, support sustainability goals while reducing operational costs.
- For instance, LG Electronics offers refrigerators with Wi-Fi connectivity and interior cameras, allowing users to monitor contents and appliance status remotely through their smartphones, demonstrating how wireless and IoT features are becoming standard in modern appliances.
Growing Focus on Hygiene and Sustainable Design Influences Purchasing Decisions:
Hygiene standards and environmental concerns are driving significant design shifts in the Ice Maker Market. Foodservice operators and healthcare providers increasingly prefer machines with antimicrobial components, sealed water systems, and reduced-touch dispensing. It supports compliance with health regulations and ensures a safer user environment. Consumers and businesses seek units with recyclable materials, low energy consumption, and water-saving capabilities. Demand rises for air-cooled models and units with eco-friendly refrigerants. Manufacturers respond by launching models certified by Energy Star and other sustainability benchmarks to address these evolving buyer preferences.
- For instance, Franke’s EcO3Ice Antimicrobial Ice Protection system uses a dissolved ozone generator to significantly reduce microbial growth and biofilm formation inside ice machines, as confirmed by field studies in restaurant environments.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs Limit Adoption:
The Ice Maker Market faces challenges related to the high upfront cost of advanced ice-making equipment. Small businesses and budget-conscious institutions often hesitate to invest in premium machines with automated features. It requires routine maintenance, filter replacements, and periodic cleaning to ensure consistent performance and hygiene. These ongoing costs can burden owners, especially in price-sensitive regions. Complex installations and space limitations in older buildings also restrict deployment. Buyers may opt for low-cost or traditional alternatives, slowing the adoption of modern systems.
- For instance, Easy Ice has successfully addressed these barriers by offering a subscription-based model that includes both the machine and all service and maintenance costs, making modern ice makers more accessible for hotels and businesses that might otherwise be deterred by high upfront investments and ongoing expenses.
Water and Energy Consumption Raise Sustainability Concerns:
Water and energy usage remain key environmental challenges for the Ice Maker Market. High-capacity models consume significant utilities, increasing operational costs and environmental impact. It raises concerns in regions with limited water resources or strict energy regulations. Older models often fall short of current efficiency standards, prompting replacements or regulatory pressure. Manufacturers must address these concerns through eco-friendly designs and innovation in cooling and insulation. Balancing performance with environmental responsibility remains critical to long-term market growth.
Market Opportunities:
Expansion in Emerging Economies Creates New Revenue Streams:
Rapid urbanization, rising disposable incomes, and the growth of hospitality infrastructure in emerging economies present strong opportunities for the Ice Maker Market. Countries in Asia Pacific, Latin America, and the Middle East are witnessing a surge in hotels, restaurants, and healthcare facilities. It benefits from increased demand for cold chain logistics and food preservation solutions. Government investments in tourism and public health amplify the need for modern cooling appliances. Manufacturers can capture market share by offering affordable, energy-efficient models tailored to regional needs. Local partnerships and distribution networks further support penetration in untapped areas.
Product Customization and Niche Applications Broaden Market Scope:
Evolving customer preferences create demand for specialized ice types and compact machine formats across sectors. The Ice Maker Market can grow by offering modular, space-saving units for co-working spaces, mobile food outlets, and luxury residential kitchens. It also sees rising interest in machines that produce gourmet, nugget, or flake ice to suit specific uses in cocktails, healthcare, and seafood display. Customization features such as adjustable cube size, touchless dispensing, and Wi-Fi controls attract tech-savvy and hygiene-conscious buyers. These niche applications allow manufacturers to diversify offerings and increase margins in a competitive landscape.
Market Segmentation Analysis:
By Type
The Ice Maker Market includes modular, under-counter, countertop, and portable units. Modular ice makers hold the largest share due to their high output and suitability for commercial and industrial applications. Under-counter and countertop machines serve mid-sized operations where space optimization is critical. Portable ice makers gain traction in residential and outdoor use due to ease of transport and installation. It benefits from growing demand in events, food trucks, and recreational settings.
By Product
Cube ice makers lead the product segment, driven by high usage in restaurants, bars, and hotels where standard-sized ice cubes are preferred for beverages. Flake ice makers are widely used in medical, seafood, and supermarket applications for their soft consistency and cooling efficiency. Nugget ice makers show steady growth in both healthcare and foodservice sectors due to their chewable texture and water-efficient design. It reflects changing consumer preferences and application-specific needs.
By Application
Commercial applications dominate the Ice Maker Market, led by hotels, cafes, quick-service restaurants, and retail chains requiring consistent and hygienic ice supply. Healthcare facilities use ice makers for storing biological materials, pharmaceuticals, and patient recovery processes. Residential use is growing steadily, supported by premium appliance integration and rising interest in home entertainment. It shows potential across both traditional and emerging use cases.
Segmentations:
By Type
- Modular Ice Makers
- Under-Counter Ice Makers
- Countertop Ice Makers
- Portable Ice Makers
By Product
- Cube Ice Makers
- Flake Ice Makers
- Nugget Ice Makers
- Gourmet Ice Makers
By Application
- Commercial
- Residential
- Healthcare
- Industrial
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America: Holds 38% Market Share, Leading Institutional Demand
North America holds 38% of the Ice Maker Market, securing its position as the top regional contributor. The region benefits from a well-established foodservice industry and advanced healthcare systems that drive consistent demand. It supports widespread use in restaurants, hotels, hospitals, and convenience stores where hygiene and ice quality are essential. Strong consumer preferences for chilled beverages and premium service standards encourage frequent equipment upgrades. The presence of key manufacturers and reliable service infrastructure further enhances market growth. Quick-service restaurants and event-based catering continue to expand ice maker adoption across metropolitan areas.
Europe: Captures 28% Market Share, Driven by Sustainability-Focused Adoption
Europe holds 28% of the Ice Maker Market, driven by increasing emphasis on energy-efficient appliances and eco-conscious business practices. The region sees strong demand from hospitality venues, cafes, and institutional kitchens that prioritize low-energy and low-noise machines. It supports adoption in space-constrained operations with modular and built-in equipment. Tourism growth across Southern and Western Europe boosts demand for high-capacity units in seasonal and coastal destinations. Healthcare applications also contribute to steady equipment demand, particularly for specialized ice types. Manufacturers gain traction by aligning with EU environmental regulations and offering certified models.
Asia Pacific: Accounts for 23% Market Share, Poised for Fastest Growth
Asia Pacific holds 23% of the Ice Maker Market and is projected to record the fastest growth rate in the coming years. Rising urbanization, increasing consumer spending, and rapid infrastructure expansion drive equipment demand across foodservice, healthcare, and retail sectors. It benefits from growing presence of international food chains, modern hospitals, and cold storage facilities. Government initiatives to improve public health systems and tourism infrastructure support long-term growth. High demand for affordable, compact, and energy-saving models aligns with regional economic priorities. Local manufacturers compete on cost efficiency and customization to gain market share in dense urban markets.
Key Player Analysis:
- Whynter LLC.
- ITV Ice Makers
- AB Electrolux
- Hoshizaki Corporation.
- Howe Corporation
- A & V Refrigeration Corp.
- Ali Group SPA
- Cornelious Inc.
- Middleby Corporation
- North Star Ice Equipment Corporation
- Direct Catering Products Ltd.
- Kold Draft
Competitive Analysis:
The Ice Maker Market features a competitive landscape shaped by global and regional manufacturers offering a wide range of products across commercial, industrial, and residential applications. It is characterized by continuous innovation in energy efficiency, automation, and design to meet evolving customer expectations. Leading companies focus on product differentiation through smart features, low maintenance requirements, and compact formats. Players such as Hoshizaki, Manitowoc, and Scotsman maintain strong brand presence through extensive distribution networks and after-sales service. Regional firms compete by offering cost-effective solutions tailored to local preferences. Strategic partnerships, mergers, and product launches are common tactics to strengthen market position and expand reach. Innovation in refrigerant technology and sustainable materials further intensifies competition among top-tier brands.
Recent Developments:
- In December 2024, Hoshizaki Corporation began shipping upgraded commercial refrigerator, freezer, and refrigerator-freezer models, completing the transition of all standard models for the Japanese market from HFCs to low-environmental-impact natural refrigerants, furthering their leadership in sustainable cooling solutions.
- In March 2025, Middleby Corporation formed the Brewing & Distilling Solutions Group, aligning brands to deliver advanced beverage and ice solutions and enhance innovation for evolving customer needs.
- In January 2024, Hoshizaki Corporation announced the adoption of HFC-free natural refrigerants in standard model ice machines, with a phased rollout beginning January 5, 2024, and 14 models available by June 2024 in Japan.
Market Concentration & Characteristics:
The Ice Maker Market exhibits moderate to high market concentration, with a few multinational players holding significant global share. It is defined by strong competition among established brands and emerging regional manufacturers. Product quality, energy efficiency, and after-sales support play a decisive role in customer loyalty. The market favors companies with wide distribution networks, robust R&D capabilities, and the ability to meet diverse end-user needs. It demonstrates consistent demand across sectors such as foodservice, healthcare, hospitality, and retail. Regulatory compliance, technological integration, and customization remain critical to competitive positioning. The market continues to evolve with a focus on sustainability, compact design, and automation features.
Report Coverage:
The research report offers an in-depth analysis based on Type, Product Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Manufacturers will integrate smart features and automation to enhance efficiency and reduce operational complexity.
- The healthcare sector will continue expanding its use of ice makers for temperature-sensitive storage and patient care.
- Emerging economies will drive demand with increasing urbanization, tourism, and foodservice expansion.
- The foodservice industry will remain a key growth area, with quick-service restaurants and cafes upgrading to modern machines.
- Consumer preferences will favor machines offering multiple ice shapes, quiet operation, and compact design.
- Regulatory pressure will drive innovation in eco-friendly refrigerants and energy-saving technologies.
- Residential adoption will rise as consumers invest in premium appliances that offer convenience and style.
- Online retail platforms will play a larger role in product visibility and customer outreach.
- Strong after-sales service and product reliability will influence brand loyalty and repeat purchases.
- Competitive intensity will increase as global and regional players invest in product development and market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Foodservice and Hospitality Sectors
The growing number of restaurants, hotels, cafes, and quick-service outlets is driving demand for reliable, high-capacity, and hygienic ice makers to support beverage service, food preservation, and presentation needs.
Healthcare and Pharmaceutical Applications
Hospitals, clinics, and laboratories require specialized ice makers for temperature-sensitive storage, infection control, and patient care, leading to increased adoption of medical-grade and precision-controlled ice machines.
Urbanization and Changing Consumer Lifestyles
Rising urban populations and disposable incomes are fueling demand for compact, stylish, and convenient ice makers in residential settings, as consumers seek premium appliances for home comfort and entertainment.
Technological Advancements and Energy Efficiency
Manufacturers are integrating smart controls, IoT features, and energy-efficient technologies into ice makers, enhancing operational efficiency, reducing maintenance, and attracting tech-savvy and sustainability-focused buyers.
Regulatory Focus on Food Safety and Hygiene
Stricter regulations around food safety and hygiene standards are prompting commercial and healthcare operators to upgrade to advanced ice makers with antimicrobial features and automated cleaning, ensuring compliance and consumer safety.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Ice Maker Market?
What is driving the growth of the Ice Maker Market?
Which region is expected to grow the fastest?
Why are smart features important in ice makers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Modular Ice Makers
- 1.2.2 Under-Counter Ice Makers
- 1.2.3 Countertop Ice Makers
- 1.2.4 Portable Ice Makers
- 1.3 By Product
- 1.3.1 Cube Ice Makers
- 1.3.2 Flake Ice Makers
- 1.3.3 Nugget Ice Makers
- 1.3.4 Gourmet Ice Makers
- 1.4 By Application
- 1.4.1 Commercial
- 1.4.2 Residential
- 1.4.3 Healthcare
- 1.4.4 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,325.53 million → 2032: USD 7,176.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ice Maker Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ice Maker Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ice Maker Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ice Maker Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ice Maker Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ice Maker Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ice Maker Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ice Maker Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,325.53 million → 2032: USD 7,176.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ice Maker Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Modular Ice Makers
- 12.3.7.2 Under-Counter Ice Makers
- 12.3.7.3 Countertop Ice Makers
- 12.3.7.4 Portable Ice Makers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cube Ice Makers
- 12.4.7.2 Flake Ice Makers
- 12.4.7.3 Nugget Ice Makers
- 12.4.7.4 Gourmet Ice Makers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Commercial
- 12.5.7.2 Residential
- 12.5.7.3 Healthcare
- 12.5.7.4 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ice Maker End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ice Maker Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ice Maker Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ice Maker Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hoshizaki Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Middleby Corporation
- 18.4 AB Electrolux
- 18.5 Ali Group SPA
- 18.6 ITV Ice Makers
- 18.7 Whynter LLC
- 18.8 Howe Corporation
- 18.9 Cornelius Inc.
- 18.10 North Star Ice Equipment Corporation
- 18.11 Kold Draft
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

