
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| IGaas (Industrial Goods as a Service) Market Size 2024 | USD 29750 million |
| IGaas (Industrial Goods as a Service) Market, CAGR | 15.89% |
| IGaas (Industrial Goods as a Service) Market Size 2032 | USD 96795.38 million |
Market Overview:
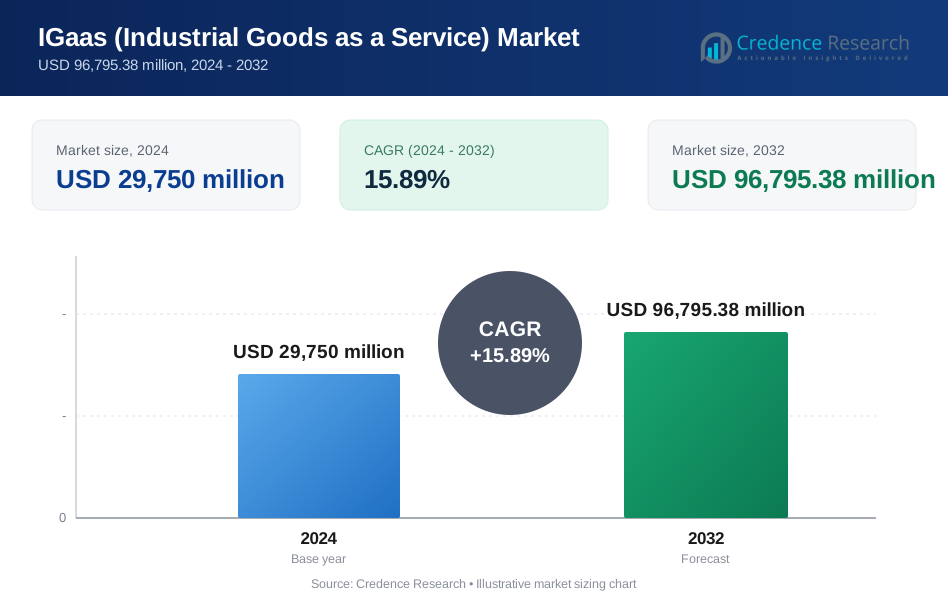
IGaas (Industrial Goods as a Service) Market size was valued at USD 29750 million in 2024 and is anticipated to reach USD 96795.38 million by 2032, at a CAGR of 15.89% during the forecast period (2024-2032).
Key market drivers include the rising demand for cost-effective and flexible industrial solutions, minimizing capital expenditure while maximizing asset utilization. Digital transformation across industries and advancements in IoT, AI, and automation enable efficient asset management and predictive maintenance, reducing downtime and operational inefficiencies. Additionally, sustainability concerns and regulatory mandates are pushing industries toward service-oriented models, reducing waste and improving resource efficiency. The need for scalable and customizable industrial solutions further fuels the market’s growth, with businesses seeking tailored service packages that align with their operational needs. The adoption of AI-powered predictive analytics enhances operational efficiency by preventing equipment failures and optimizing resource allocation. Furthermore, companies are leveraging IGaaS models to achieve competitive differentiation by offering value-added services alongside their core industrial solutions.
Regionally, North America dominates the IGaaS market due to early adoption of digital technologies and strong industrial infrastructure. Europe follows closely, driven by stringent environmental regulations and an increasing focus on industrial sustainability. The Asia-Pacific region is witnessing rapid growth, supported by expanding industrial sectors, rising adoption of smart manufacturing, and government initiatives promoting Industry 4.0. Emerging markets in Latin America and the Middle East & Africa are also gaining traction as companies seek cost-effective and technology-driven industrial solutions. Growing investments in digital manufacturing ecosystems and smart factories across key regions are further accelerating IGaaS adoption. Additionally, regional partnerships between industrial service providers and technology firms are strengthening market expansion by enabling end-to-end service integration.
Market Insights:
- The IGaaS market was valued at USD 29,750 million in 2024 and is expected to reach USD 96,795.38 million by 2032, growing at a CAGR of 15.89%.
- Increasing demand for cost-effective and flexible industrial solutions is driving the transition from traditional ownership to service-based models.
- Integration of IoT, AI, and automation enhances asset management, predictive maintenance, and operational efficiency, reducing downtime and costs.
- Sustainability regulations and circular economy initiatives are pushing industries toward IGaaS adoption to optimize resource utilization and reduce waste.
- North America leads the market with a 35% share, followed by Europe at 30%, driven by strong industrial infrastructure and sustainability policies.
- Asia-Pacific is the fastest-growing region, holding a 25% share, fueled by industrial automation, smart manufacturing, and Industry 4.0 initiatives.
- Market competition is intensifying as key players invest in digital transformation, cybersecurity, and customized service models to gain a competitive edge.
Market Drivers:
Shift Toward Cost-Effective and Flexible Industrial Solutions:
The increasing demand for cost-effective and flexible industrial solutions is a major driver of the IGaaS market. Businesses are shifting from traditional ownership models to service-based offerings to minimize capital expenditures while optimizing asset utilization. The subscription-based and pay-per-use models provide companies with financial flexibility, allowing them to scale operations without significant upfront investments. For instance, Honeywell has successfully transformed itself into an industrial software and services company by leveraging IoT, offering solutions like Honeywell Forge to enhance operational efficiency and insights across various industries. This transition enables industries to allocate resources more efficiently, enhancing productivity and cost-effectiveness. Additionally, IGaaS solutions help businesses mitigate financial risks by converting capital expenses into predictable operational costs, improving financial stability and operational agility.
Advancements in IoT, AI, and Automation:
The integration of advanced technologies, including IoT, AI, and automation, is accelerating the adoption of IGaaS across various industries. IoT-enabled devices facilitate real-time monitoring and predictive maintenance, reducing equipment downtime and enhancing overall efficiency. AI-powered analytics optimize industrial processes by predicting failures, improving asset management, and streamlining operations. Automation further enhances service-based models by enabling remote monitoring and proactive maintenance, reducing manual intervention. For instance, Samsara's IoT and AI solutions have been instrumental in enhancing operational efficiency and safety across various industries by providing real-time data and insights for fleet management and equipment monitoring. These technological advancements not only improve operational efficiency but also contribute to sustainability by reducing energy consumption and resource wastage.
Regulatory Push for Sustainability and Circular Economy:
Regulatory frameworks and sustainability initiatives are driving the adoption of IGaaS models across industries. Governments and regulatory bodies are imposing stringent environmental policies, encouraging businesses to adopt circular economy principles. By shifting to service-based models, industries can extend the lifecycle of assets, reduce waste, and optimize resource consumption. IGaaS also aligns with sustainability goals by promoting energy efficiency, reducing emissions, and enabling responsible waste management. For example, the Plastic Waste Management Rules (2016) in India have catalyzed significant measures across various industries to control plastic pollution. Companies that embrace service-oriented industrial solutions gain a competitive advantage by complying with regulatory mandates while demonstrating environmental responsibility.
Growing Demand for Scalable and Customized Solutions:
The increasing need for scalable and customized industrial solutions is further propelling the IGaaS market. Industries require flexible service models that can adapt to changing operational needs without excessive capital investment. IGaaS providers offer tailored solutions, allowing businesses to select specific services based on their requirements. This flexibility enables enterprises to optimize their industrial processes, improve asset performance, and enhance operational resilience. For instance, Modulight Corporation offers customized laser solutions, such as tailored packaging for integration into existing hardware, which allows businesses to adapt their manufacturing processes efficiently. Additionally, the ability to integrate multiple services into a single offering enhances efficiency, making IGaaS a preferred choice for businesses seeking long-term value and operational excellence.
Market Trends:
Increased Adoption of Subscription-Based and Pay-Per-Use Models:
The IGaaS market is witnessing a significant shift toward subscription-based and pay-per-use models as industries seek cost-efficient alternatives to traditional ownership. For instance, Siemens offers subscription-based access to its industrial automation software, allowing companies to utilize advanced technology without large capital investments. Companies prefer flexible payment structures that allow them to access industrial equipment and services without large capital investments. This trend is particularly strong in manufacturing, logistics, and construction, where businesses prioritize asset optimization and operational agility. The growing demand for scalable solutions is further driving the adoption of IGaaS, enabling companies to enhance productivity while reducing financial risk.
Integration of IoT, AI, and Predictive Maintenance:
Technological advancements, particularly in IoT, AI, and predictive maintenance, are transforming the IGaaS market. IoT-enabled industrial assets provide real-time data insights, allowing businesses to monitor equipment performance and detect potential failures before they occur. AI-driven analytics optimize asset utilization and improve decision-making by automating maintenance schedules and reducing downtime. For instance, Faststream Technologies uses IoT sensors for predictive maintenance, employing techniques like vibration analysis and thermal imaging to evaluate asset performance in real-time, thereby enhancing operational efficiency and reducing maintenance costs. The integration of these technologies enhances service efficiency, ensuring that businesses maximize asset longevity while minimizing operational disruptions.
Emphasis on Sustainability and Circular Economy Models:
Sustainability is becoming a key focus in the IGaaS market, with industries adopting circular economy principles to reduce waste and improve resource efficiency. Companies are shifting toward service-based models to extend the lifecycle of industrial assets and minimize environmental impact. This trend aligns with regulatory requirements and corporate sustainability goals, driving businesses to prioritize energy-efficient and eco-friendly solutions. For instance, Vedanta Limited is committed to reducing its environmental footprint by transitioning to renewable energy sources and improving waste recycling, reflecting a broader industry shift toward sustainable practices. As a result, IGaaS providers are developing innovative service models that enhance operational sustainability.
Expansion of IGaaS Across Emerging Markets:
The IGaaS market is expanding rapidly in emerging economies as industries adopt digital transformation strategies. For instance, in India, the government’s “Make in India” initiative has significantly boosted investments in industrial automation and smart manufacturing. Increasing investments in industrial automation and smart manufacturing are fueling demand for service-based solutions in regions such as Asia-Pacific, Latin America, and the Middle East. Governments and enterprises are leveraging IGaaS to modernize infrastructure and improve operational efficiency, leading to a broader market reach. The trend toward localized service partnerships is also gaining momentum, enabling businesses to access customized industrial solutions tailored to regional needs.
Market Challenges Analysis:
Complex Implementation and Integration Issues:
The adoption of IGaaS faces challenges related to implementation complexities and integration with existing industrial systems. Many businesses operate with legacy infrastructure that is not easily compatible with service-based models, requiring significant upgrades and system modifications. Integrating IGaaS solutions with IoT, AI, and automation technologies demands substantial investment in digital transformation, which can be a barrier for small and mid-sized enterprises. Additionally, ensuring seamless data connectivity and interoperability across diverse industrial ecosystems presents technical challenges, delaying adoption and increasing operational costs. The lack of standardized protocols across industries further complicates integration, leading to inefficiencies in deployment. Moreover, resistance to change within organizations slows down the transition to service-based models, as businesses need to upskill their workforce and adapt to new operational workflows. To address these challenges, IGaaS providers must offer tailored solutions that facilitate smooth integration while minimizing disruptions in existing processes.
Data Security and Regulatory Compliance Risks:
The IGaaS model relies heavily on real-time data collection, cloud computing, and AI-driven analytics, making data security and regulatory compliance critical concerns. Industrial assets connected to cloud-based platforms are vulnerable to cyber threats, including data breaches and unauthorized access, which can disrupt operations and compromise sensitive information. Companies must invest in robust cybersecurity measures to mitigate these risks, adding to operational expenses. Furthermore, regulatory frameworks governing data protection and industrial operations vary across regions, making compliance complex for multinational organizations. Ensuring adherence to industry standards and local regulations adds another layer of challenge, requiring IGaaS providers to implement region-specific strategies to maintain compliance while delivering seamless services. The evolving nature of data privacy laws increases uncertainty for businesses, necessitating continuous monitoring and updates to security protocols. Additionally, concerns about data ownership and third-party access create reluctance among industries to fully embrace cloud-based service models. To overcome these challenges, IGaaS providers must prioritize end-to-end encryption, strong access controls, and transparent data governance policies.
Market Opportunities:
The IGaaS market presents significant growth opportunities driven by the increasing adoption of digital transformation and Industry 4.0 initiatives. As industries seek to optimize operational efficiency and reduce capital expenditures, service-based models offer a cost-effective alternative to traditional asset ownership. The rising implementation of IoT, AI, and cloud-based solutions enables real-time monitoring, predictive maintenance, and data-driven decision-making, enhancing asset utilization. Additionally, the growing demand for flexible, scalable, and subscription-based industrial solutions creates new opportunities for IGaaS providers to develop tailored offerings that cater to specific industry needs. Businesses are increasingly recognizing the benefits of shifting to a service-oriented approach, unlocking opportunities for providers to offer value-added services such as remote diagnostics, automated maintenance scheduling, and performance optimization.
Expanding IGaaS adoption in emerging markets presents another major growth avenue as industries in regions such as Asia-Pacific, Latin America, and the Middle East invest in industrial automation and smart manufacturing. Governments and private enterprises are prioritizing digital infrastructure development, creating demand for technology-driven service solutions. Moreover, sustainability-focused initiatives are driving industries to adopt circular economy principles, positioning IGaaS as an ideal solution for reducing waste and improving resource efficiency. Companies seeking to comply with environmental regulations and improve operational sustainability are turning to service-based models that extend asset lifecycles while minimizing environmental impact. The increasing collaboration between industrial service providers and technology firms further strengthens market expansion, enabling end-to-end service integration that enhances industrial productivity and cost efficiency.
Market Segmentation Analysis:
By Type
The IGaaS market is segmented based on different service models, including subscription-based services, pay-per-use models, and leasing-based industrial solutions. Subscription-based services dominate the market, as businesses prefer predictable cost structures and access to continuous upgrades. Pay-per-use models are gaining traction, particularly in industries requiring flexible and demand-driven access to industrial assets. Leasing-based services also hold a significant share, enabling companies to utilize high-value industrial equipment without substantial capital investments. The growing preference for customized service packages across industries further enhances market growth, allowing businesses to optimize asset utilization and operational efficiency.
By Application
IGaaS finds application across various industries, including manufacturing, logistics, construction, and energy. The manufacturing sector leads the market, driven by the increasing adoption of smart factories and industrial automation. Logistics companies are leveraging IGaaS to optimize fleet and warehouse management, reducing operational costs through efficient asset usage. The construction industry benefits from flexible access to heavy machinery and equipment without long-term ownership commitments. Additionally, the energy sector is integrating IGaaS solutions to enhance the performance and maintenance of critical infrastructure. The expanding scope of IGaaS across multiple industries highlights its role in improving efficiency, sustainability, and cost-effectiveness.
Segmentations:
By Type
- Subscription-Based Services
- Pay-Per-Use Models
- Leasing-Based Solutions
By Application
- Manufacturing
- Logistics
- Construction
- Energy
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a market share of 35%, making it the dominant region in the IGaaS market. The region’s leadership is driven by early adoption of digitalization, strong industrial infrastructure, and advanced IoT and AI integration in industrial operations. The presence of key market players and a high demand for cost-effective, flexible asset utilization models further contribute to market expansion. Manufacturing and logistics sectors are leading adopters of IGaaS, leveraging subscription-based and pay-per-use models to enhance operational efficiency. Government initiatives supporting Industry 4.0, along with stringent regulations on industrial sustainability, drive the transition toward service-based models. Additionally, high investment in cloud-based solutions and predictive maintenance technologies accelerates IGaaS adoption across industries. The rising need for scalable and customized industrial solutions is further pushing companies to integrate IGaaS into their operations, driving long-term regional growth.
Europe
Europe accounts for 30% of the IGaaS market, supported by strict environmental regulations and a growing focus on industrial sustainability. The transition toward a circular economy, where businesses prioritize resource efficiency and waste reduction, fuels IGaaS adoption across key industries. The manufacturing sector is a major contributor, driven by automation trends and the push for energy-efficient industrial solutions. Logistics and construction industries are increasingly adopting IGaaS to optimize equipment usage and reduce capital expenditures. The presence of strong government policies promoting digital transformation and industrial efficiency further strengthens the market. Additionally, partnerships between industrial service providers and technology firms enhance regional growth by enabling seamless integration of service-based solutions. The rising emphasis on lowering operational risks and improving business resilience is driving industries toward IGaaS models, ensuring long-term cost savings and operational agility.
Asia-Pacific
Asia-Pacific holds a market share of 25%, experiencing the fastest growth in the IGaaS market. Rapid industrialization, increasing adoption of smart manufacturing, and government-led initiatives promoting Industry 4.0 drive regional expansion. Countries such as China, Japan, and India are leading adopters, investing heavily in industrial automation and digital infrastructure. The manufacturing and energy sectors contribute significantly to IGaaS demand, leveraging service-based models for cost optimization and operational efficiency. The logistics sector is also witnessing strong growth, with businesses adopting asset-as-a-service solutions to enhance supply chain efficiency. Increasing collaboration between global IGaaS providers and regional industrial players is further accelerating market adoption. The rising presence of local IGaaS providers offering region-specific solutions is fueling competitive growth, expanding market opportunities across diverse industrial sectors.
Key Player Analysis:
- Siemens AG
- General Electric (GE)
- Honeywell International Inc.
- Rockwell Automation, Inc.
- Schneider Electric SE
- ABB Ltd.
- Mitsubishi Electric Corporation
- Bosch Rexroth AG
- Caterpillar Inc.
- Komatsu Ltd.
- Eaton Corporation plc
- Hitachi Ltd.
Competitive Analysis:
The IGaaS market is highly competitive, with leading players focusing on innovation, digital transformation, and strategic partnerships to strengthen their market position. For instance, Siemens AG has successfully integrated IoT and AI solutions to enhance service efficiency and asset management, allowing for more effective predictive maintenance and remote monitoring. Companies such as Siemens AG, General Electric, and Schneider Electric leverage advanced IoT, AI, and cloud-based solutions to enhance service efficiency and asset management. Key players are expanding their service offerings through subscription-based and pay-per-use models, catering to diverse industrial needs.
Market competition is driven by technological advancements, regional expansion, and sustainability initiatives. Companies are investing in predictive maintenance, remote monitoring, and data-driven analytics to improve operational efficiency. Strategic collaborations with industrial service providers and technology firms are further intensifying competition. Additionally, emerging players are gaining traction by offering cost-effective and customized IGaaS solutions, challenging established market leaders. The evolving demand for flexible and scalable service models is shaping the competitive landscape, driving continuous innovation and market growth.
Recent Developments:
- In March 2024, ABB invests in AI startup UptimeAI to enhance industrial asset performance through predictive maintenance, a key aspect of IGaaS. This partnership aims to optimize operations and reduce downtime in industries like cement and metals.
- In June 2024, Hitachi and Microsoft announce a projected multi-billion-dollar collaboration over the next three years. This partnership will accelerate digital transformation by embedding Microsoft cloud services into Hitachi's Lumada solutions, enhancing operational efficiency and application development.
Market Concentration & Characteristics:
The IGaaS market exhibits a moderately high level of concentration, with key global players such as Siemens AG, General Electric, and Schneider Electric holding significant market shares. These established companies dominate the market through advanced digital solutions, strong industrial partnerships, and extensive service portfolios. The market is characterized by rapid technological advancements, increasing adoption of IoT and AI-driven predictive maintenance, and a shift toward flexible, subscription-based service models. Competitive differentiation is driven by innovation, service customization, and integration of cloud-based asset management solutions. While large enterprises lead in market presence, emerging players are gaining traction by offering cost-effective and scalable IGaaS solutions tailored to industry-specific needs. The market also demonstrates strong growth potential in developing regions, where industrial automation and digital transformation are accelerating. Sustainability initiatives and regulatory frameworks further influence market dynamics, encouraging companies to adopt energy-efficient and resource-optimized service models.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for flexible, subscription-based industrial solutions will continue to grow as businesses seek cost-effective alternatives to traditional asset ownership.
- Advancements in IoT, AI, and cloud computing will enhance real-time monitoring, predictive maintenance, and asset optimization, driving widespread adoption of IGaaS models.
- Sustainability initiatives and regulatory mandates will push industries toward service-based models, promoting circular economy practices and resource-efficient operations.
- Increased investment in industrial automation and digital transformation will accelerate the transition to IGaaS, particularly in manufacturing, logistics, and construction sectors.
- The integration of AI-driven analytics and machine learning will improve operational efficiency, enabling predictive insights and automated service management.
- Expansion in emerging markets, including Asia-Pacific, Latin America, and the Middle East, will drive new opportunities as businesses modernize industrial infrastructure.
- Strategic collaborations between IGaaS providers and technology firms will enhance service offerings, enabling seamless connectivity and data-driven decision-making.
- Companies will prioritize cybersecurity and data governance to address concerns related to data privacy, regulatory compliance, and cyber threats.
- Increasing adoption of remote monitoring and automation solutions will reduce operational risks and improve equipment lifecycle management.
- Customization and scalability will remain key differentiators, with IGaaS providers offering industry-specific solutions to meet evolving business needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected market size of the IGaaS market?
What are the key drivers of the IGaaS market growth?
How does IGaaS benefit industries?
What role does technology play in IGaaS market expansion?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 IGaas (Industrial Goods as a Service) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global IGaas (Industrial Goods as a Service) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 29,750 million → 2032: USD 96,795.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 IGaas (Industrial Goods as a Service) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. IGaas (Industrial Goods as a Service) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 IGaas (Industrial Goods as a Service) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 IGaas (Industrial Goods as a Service) Market Drivers
- 3.3 IGaas (Industrial Goods as a Service) Market Restraints & Challenges
- 3.4 IGaas (Industrial Goods as a Service) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 IGaas (Industrial Goods as a Service) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 IGaas (Industrial Goods as a Service) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, IGaas (Industrial Goods as a Service) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 IGaas (Industrial Goods as a Service) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. IGaas (Industrial Goods as a Service) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the IGaas (Industrial Goods as a Service) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 IGaas (Industrial Goods as a Service) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 IGaas (Industrial Goods as a Service) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 IGaas (Industrial Goods as a Service) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in IGaas (Industrial Goods as a Service) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New IGaas (Industrial Goods as a Service) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global IGaas (Industrial Goods as a Service) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America IGaas (Industrial Goods as a Service) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe IGaas (Industrial Goods as a Service) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific IGaas (Industrial Goods as a Service) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America IGaas (Industrial Goods as a Service) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East IGaas (Industrial Goods as a Service) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa IGaas (Industrial Goods as a Service) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. IGaas (Industrial Goods as a Service) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
