
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
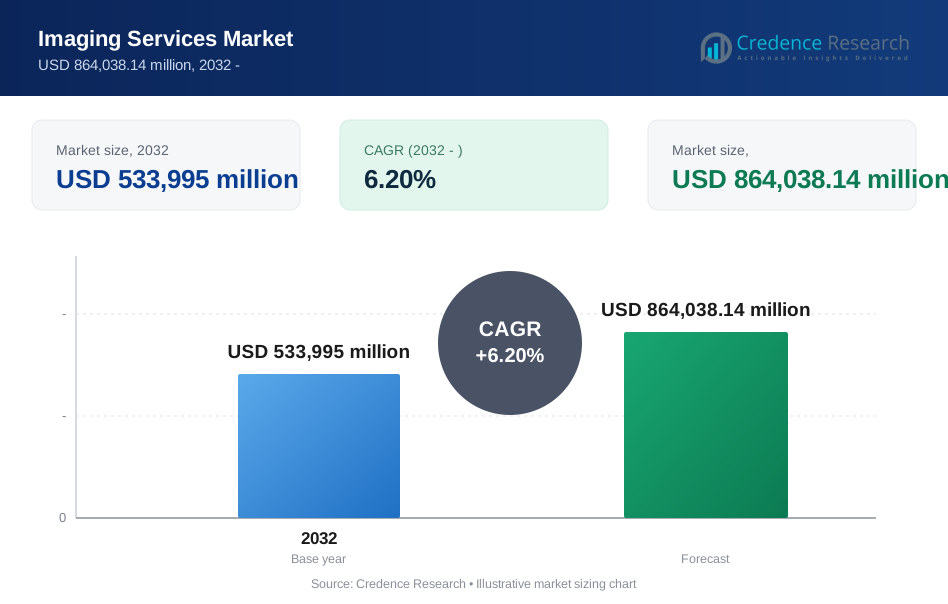
| Imaging Services Market Size 2024 | USD 533,995 Million |
| Imaging Services Market, CAGR | 6.20% |
| Imaging Services Market Size 2032 | USD 864,038.14 Million |
Market Overview:
The Imaging Services Market is experiencing substantial growth, driven by advancements in imaging technology and an increasing demand for diagnostic imaging procedures. As of 2024, the global Imaging Services Market is valued at approximately USD 533,995 million and is projected to grow at a compound annual growth rate (CAGR) of 6.20% over the forecast period, reaching around USD 864,038.14 million by 2032. This robust growth reflects the rising prevalence of chronic diseases, the aging population, and the growing emphasis on preventive healthcare.
Several key factors are fueling the market's expansion. The increasing utilization of imaging modalities such as MRI, CT scans, and ultrasound is enhancing diagnostic accuracy and patient outcomes. Moreover, technological innovations, including the integration of artificial intelligence (AI) in imaging systems, are improving the efficiency and efficacy of imaging services. The rising awareness of the importance of early diagnosis and treatment is further driving demand for imaging services across healthcare facilities.
Regionally, North America dominates the Imaging Services Market, attributed to its advanced healthcare infrastructure, high healthcare expenditure, and early adoption of cutting-edge imaging technologies. Europe follows closely, supported by a well-established healthcare system and increasing investments in medical imaging. The Asia-Pacific region is anticipated to witness significant growth during the forecast period, driven by expanding healthcare services, increasing government initiatives to enhance healthcare infrastructure, and rising awareness about the benefits of advanced imaging technologies. Emerging economies in this region, such as China and India, present substantial growth opportunities due to their large populations and growing healthcare investments.
Market Drivers:
Technological Advancements:
Technological innovation is a crucial driver of growth in the Imaging Services Market. Recent developments in imaging modalities have significantly enhanced diagnostic capabilities, making them indispensable in healthcare settings. For instance, in March 2024, GE Healthcare unveiled its SonoSAMTrack1, an advanced research model that leverages NVIDIA technology. This model is built on the foundational SonoSAM1, designed specifically for object segmentation in ultrasound imagery. The core functionality of SonoSAMTrack is to accurately delineate anatomical structures, lesions, and critical regions within ultrasound images, ultimately improving diagnostic precision. Such advancements not only facilitate better patient outcomes but also encourage healthcare providers to adopt state-of-the-art imaging technologies. The integration of artificial intelligence (AI) and machine learning in imaging systems further boosts efficiency, enabling faster analysis and improved workflow. This technological evolution continues to attract investment and interest from both healthcare providers and patients.
Rising Demand for Early Diagnosis:
The increasing prevalence of chronic diseases is another significant driver for the Imaging Services Market. According to the World Health Organization (WHO), the number of individuals suffering from chronic conditions is expected to rise by 75% by 2030. This alarming trend underscores the necessity for frequent diagnostic imaging procedures aimed at early detection and timely intervention. The International Monetary Fund (IMF) projects that global healthcare spending on preventive measures will rise by 5% annually through 2025. As healthcare systems worldwide focus more on early diagnosis to improve patient outcomes and reduce long-term costs, the demand for imaging services will naturally surge. Furthermore, as more patients become aware of the importance of early diagnosis, healthcare providers are increasingly compelled to offer advanced imaging services. This heightened awareness drives hospitals and clinics to invest in innovative imaging technologies, which can enhance their service offerings.
Growing Aging Population:
The global aging population is a pivotal factor contributing to the growth of the Imaging Services Market. According to United Nations projections, the number of individuals aged 60 and older is expected to double from 1 billion in 2020 to 2.1 billion by 2050. Older adults often require more medical interventions, including imaging services, to manage age-related health issues such as cardiovascular diseases, cancers, and degenerative conditions. For instance, In January 2024, Canon introduced Aplio me, a cutting-edge shared-service ultrasound system designed to cater to diverse medical environments. This portable system is particularly well-suited for healthcare providers serving aging populations, as it offers high efficiency in workflow and sophisticated solutions for various medical settings, from small clinics to large hospitals. As the demand for age-specific healthcare services rises, imaging technologies must evolve to meet the needs of this demographic, further driving market growth.
Government Initiatives and Funding:
Government support plays a critical role in propelling the Imaging Services Market. Many governments are actively implementing policies to enhance healthcare infrastructure and expand access to diagnostic services. A significant focus on improving public health has led to increased funding for healthcare facilities, especially in developing countries. For Instance, In November 2023, Canon Medical Systems introduced significant upgrades to its CT product line, including the launch of two new scanners presented at the Radiological Society of North America Congress. The World Bank has initiated several programs aimed at strengthening healthcare systems globally, particularly in regions that lack adequate diagnostic capabilities. Recent reports suggest that government spending on healthcare infrastructure is projected to increase by 8% annually through 2026. Such initiatives are designed to ensure healthcare facilities are equipped with modern imaging technologies, thus fostering market growth. Moreover, collaborations between governmental bodies and private enterprises are crucial for advancing healthcare technology and making it more accessible to underserved populations. This alignment not only addresses the immediate needs of healthcare systems but also promotes long-term sustainable growth in the Imaging Services Market.
Market Trends:
Integration of Artificial Intelligence:
The integration of artificial intelligence (AI) into imaging services is transforming the diagnostic landscape. AI technologies enhance the accuracy and efficiency of imaging procedures, allowing for more precise interpretations and quicker turnaround times. For Instance, In February 2023, GE Healthcare announced an agreement to acquire Caption Health, Inc., a privately held AI healthcare provider. Caption Health focuses on developing clinical applications aimed at early disease diagnosis, particularly through the use of AI to assist with ultrasound scans. This strategic move underscores the industry's shift toward harnessing AI capabilities to improve diagnostic outcomes. According to a report by the World Health Organization, the use of AI in healthcare is expected to grow by 40% annually, reflecting a broader trend of adopting smart technologies in medical imaging. The increasing reliance on AI not only enhances patient care but also enables healthcare professionals to manage workloads more efficiently, thereby addressing the growing demand for imaging services.
Advancements in Imaging Technology:
Advancements in imaging technology continue to shape the Imaging Services Market, leading to improved diagnostic capabilities and patient outcomes. For instance, In May 2023, Koninklijke Philips N.V. launched the Philips CT 3500, a high-end CT system designed to meet the needs of routine radiology and high-volume screening programs. This system features cutting-edge imaging capabilities that allow healthcare providers to conduct rapid and accurate assessments, particularly in emergency and outpatient settings. The launch of such advanced systems aligns with findings from the International Monetary Fund, which highlight the necessity for countries to invest in modern healthcare infrastructure to enhance service delivery. As healthcare facilities strive to adopt the latest technologies, the demand for innovative imaging solutions is expected to rise, further driving market growth. These advancements not only improve the quality of care but also contribute to more efficient healthcare delivery systems worldwide. The ongoing trends of AI integration and technological advancements in imaging services reflect a commitment to enhancing diagnostic accuracy and efficiency. As healthcare providers increasingly adopt these innovations, the Imaging Services Market is set to expand, meeting the evolving needs of patients and healthcare systems alike.
Market Challenge Analysis:
High Costs of Advanced Imaging Technologies:
One of the primary challenges facing the Imaging Services Market is the high cost associated with advanced imaging technologies. The acquisition and maintenance of state-of-the-art imaging systems, such as MRI and CT machines, require significant financial investment, which can be prohibitive for smaller healthcare facilities and clinics. According to the World Bank, many healthcare providers, particularly in developing regions, struggle to allocate sufficient budgets for advanced diagnostic equipment. This financial barrier often leads to disparities in access to high-quality imaging services, with larger hospitals benefitting from the latest technologies while smaller providers may rely on outdated equipment. The need for ongoing training and maintenance of sophisticated imaging systems further exacerbates this issue, as healthcare facilities must invest in specialized personnel to operate and troubleshoot these machines effectively. Moreover, the costs associated with advanced imaging technologies can hinder the adoption of innovative solutions such as AI and machine learning. Although these technologies promise to enhance diagnostic accuracy and workflow efficiency, the initial investment required for integration can deter healthcare providers from implementing them. As a result, many facilities may fall behind in adopting cutting-edge imaging solutions, limiting their ability to provide optimal patient care. To address these financial challenges, healthcare organizations must seek alternative funding sources, such as grants or partnerships with technology companies. However, navigating the complexities of funding can be time-consuming and may not always yield immediate results, leaving many facilities in a state of uncertainty regarding their imaging capabilities.
Regulatory and Compliance Challenges:
The Imaging Services Market also faces significant regulatory and compliance challenges that can impede growth and innovation. Healthcare providers must adhere to a complex web of regulations and standards set forth by government authorities and industry organizations, which can vary significantly by region. These regulations often pertain to patient safety, data privacy, and the quality of imaging services. For instance, in the United States, the Food and Drug Administration (FDA) oversees the approval and regulation of imaging devices, requiring extensive testing and documentation before new technologies can enter the market. This lengthy approval process can delay the introduction of innovative imaging solutions, stalling progress and limiting access for healthcare providers.
Additionally, compliance with these regulations requires substantial administrative resources, diverting attention and funding away from other critical areas, such as patient care and technology adoption. Smaller healthcare facilities may find it particularly challenging to navigate the regulatory landscape due to limited personnel and expertise. This situation creates a competitive disadvantage compared to larger institutions, which often have dedicated compliance teams to manage these complexities. To remain compliant while fostering innovation, healthcare organizations must invest in robust compliance frameworks and continuously educate their staff on evolving regulations. As the regulatory landscape becomes increasingly stringent, the challenge of maintaining compliance while implementing new technologies will remain a significant hurdle for many imaging service providers.
Market Segmentation Analysis:
By Type
The Imaging Services Market segments primarily by type, which includes various imaging modalities. These modalities encompass X-ray, ultrasound, magnetic resonance imaging (MRI), computed tomography (CT), and nuclear imaging. Each type serves distinct diagnostic purposes, with X-rays being commonly used for bone fractures and other structural issues. Ultrasound is widely utilized for real-time imaging, particularly in obstetrics and gynecology. MRI and CT scans are integral for detailed imaging of soft tissues and complex anatomical structures, playing crucial roles in diagnosing conditions such as tumors and neurological disorders. The demand for each imaging type varies based on specific healthcare needs, population demographics, and the prevalence of certain diseases, influencing the overall market dynamics.
By Technology
The market also segments by technology, which includes conventional imaging techniques and advanced technologies such as digital imaging, 3D imaging, and AI-assisted imaging. Conventional imaging techniques remain vital due to their established effectiveness and lower costs. However, the shift toward digital imaging has gained momentum, offering enhanced image quality and quicker processing times. 3D imaging technology is particularly valuable in surgical planning and complex diagnostics, providing a more comprehensive view of anatomical structures. The incorporation of AI in imaging services is emerging as a game-changer, enabling faster and more accurate analyses. AI algorithms assist radiologists in interpreting images, detecting anomalies, and improving workflow efficiency. This technological segmentation highlights the ongoing innovation within the market and the growing demand for enhanced imaging solutions.
By End-User
The Imaging Services Market further segments by end-user, primarily including hospitals, diagnostic imaging centers, outpatient facilities, and research institutions. Hospitals represent the largest segment, as they house advanced imaging technologies and cater to a diverse patient population requiring various imaging services. Diagnostic imaging centers are becoming increasingly prominent, focusing on specialized imaging services and offering convenience for patients seeking quick diagnostic solutions. Outpatient facilities, including urgent care clinics, are also expanding their imaging capabilities to meet the rising demand for accessible healthcare. Research institutions leverage imaging technologies for clinical studies and trials, contributing to advancements in medical science. The diversity of end-users reflects the broad applicability of imaging services across the healthcare spectrum, driving market growth and influencing future trends.
Segmentation:
Based on Product Type:
- X-ray
- Ultrasound
- Magnetic Resonance Imaging (MRI)
- Computed Tomography (CT)
- Nuclear Imaging
- Other Imaging Modalities
Based on Technology:
- Conventional Imaging Techniques
- Digital Imaging
- 3D Imaging
- AI-Assisted Imaging
- Hybrid Imaging Technologies
Based on End-User:
- Hospitals
- Diagnostic Imaging Centers
- Outpatient Facilities
- Research Institutions
- Academic Institutions
Based on Region:
- North America
- S.
- Canada
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
Regional Analysis:
North America
North America dominates the Imaging Services Market, accounting for approximately 40% of the global market share. The region benefits from advanced healthcare infrastructure, high healthcare expenditure, and early adoption of innovative imaging technologies. The United States, in particular, leads in the use of advanced imaging modalities such as MRI and CT scans. The presence of major market players like GE Healthcare and Siemens Healthineers further bolsters this region's growth. Additionally, the increasing prevalence of chronic diseases necessitates frequent diagnostic imaging, which drives demand in both hospitals and outpatient facilities. Furthermore, government initiatives aimed at enhancing healthcare quality and accessibility, alongside significant investments in medical research, contribute to the robust growth of the imaging services sector in North America.
The aging population in North America also plays a significant role in driving market growth. As the number of elderly individuals rises, the demand for diagnostic imaging to manage age-related health issues escalates. This demographic trend is expected to continue, further fueling the need for advanced imaging services. Moreover, the integration of artificial intelligence and machine learning in imaging technologies enhances diagnostic accuracy and efficiency, attracting investment and interest from healthcare providers. The combination of these factors positions North America as a leader in the Imaging Services Market.
Europe
Europe holds a significant share of the Imaging Services Market, accounting for approximately 30%. The region is characterized by a well-established healthcare system, high standards of patient care, and a strong emphasis on technological advancements in imaging. Countries like Germany, France, and the United Kingdom are at the forefront of adopting cutting-edge imaging technologies. The presence of leading manufacturers and a growing number of diagnostic imaging centers contribute to the market's expansion.
The European market is also experiencing growth due to increasing investments in healthcare infrastructure and initiatives aimed at improving diagnostic capabilities. The European Union and various governments are funding projects to enhance medical imaging services, focusing on integrating innovative technologies and improving patient outcomes. The rising incidence of chronic diseases and the demand for early diagnosis further drive the need for advanced imaging solutions.
Moreover, the regulatory environment in Europe encourages the adoption of high-quality imaging technologies. The focus on patient safety and compliance with stringent regulations ensures that healthcare providers invest in state-of-the-art equipment, thereby enhancing service delivery. The combination of these factors contributes to the steady growth of the Imaging Services Market in Europe.
Asia-Pacific
The Asia-Pacific region is rapidly emerging as a significant player in the Imaging Services Market, currently holding around 25% of the global market share. This growth is fueled by an expanding healthcare sector, increasing government initiatives to improve healthcare infrastructure, and rising awareness about the benefits of advanced imaging technologies. Countries such as China and India are at the forefront of this transformation, driven by large populations and increasing healthcare expenditures.
The rising prevalence of chronic diseases in the Asia-Pacific region further accelerates the demand for imaging services. As more individuals seek early diagnosis and treatment options, healthcare providers are investing in modern imaging technologies to meet these needs. Additionally, the integration of AI in imaging solutions is gaining traction, offering enhanced diagnostic capabilities and workflow efficiencies.
Emerging economies in the region are experiencing significant growth opportunities as they upgrade their healthcare facilities and expand access to advanced imaging services. The increasing number of diagnostic imaging centers, along with collaborations between healthcare providers and technology firms, supports the growth of the market. As the Asia-Pacific region continues to invest in healthcare innovations and infrastructure, its share of the Imaging Services Market is expected to expand further in the coming years.
Key Player Analysis:
- GE Healthcare
- Koninklijke Philips N.V.
- Siemens Healthineers
- Canon Medical Systems Corporation
- Mindray Medical International
- FUJIFILM VisualSonics Inc.
- Carestream Health
- Hitachi
- Samsung Medison Co., Ltd.
- Koning Corporation
- PerkinElmer Inc.
- Konica Minolta
- Esaote
- Hologic, Inc.
- Varex Imaging
Competitive Analysis:
The Imaging Services Market is highly competitive, characterized by the presence of several key players and a mix of established companies and emerging firms. Major players such as GE Healthcare, Siemens Healthineers, Philips, and Canon Medical Systems dominate the market due to their extensive product portfolios, innovative technologies, and strong distribution networks. These companies continually invest in research and development to enhance imaging capabilities and integrate advanced technologies like artificial intelligence and machine learning into their systems, improving diagnostic accuracy and operational efficiency. Furthermore, strategic partnerships and acquisitions, such as GE Healthcare’s acquisition of Caption Health, enable companies to expand their technological capabilities and market reach. Emerging firms are also gaining traction, particularly in regions with rapidly developing healthcare infrastructures, such as Asia-Pacific, where the demand for advanced imaging services is growing. Competitive factors such as pricing strategies, technological advancements, and customer service play a crucial role in influencing market dynamics. Additionally, regulatory compliance and the ability to adapt to changing healthcare policies further affect competitive positioning. As the market evolves, companies must focus on innovation and customer-centric solutions to maintain a competitive edge, particularly as healthcare providers seek to enhance diagnostic capabilities while managing costs. Overall, the competitive landscape is expected to intensify as new entrants emerge and established players strive to capture a larger market share.
Recent Developments:
- In March 2024, GE Healthcare developed its latest research model, SonoSAMTrack1, utilizing NVIDIA technology. This innovative model builds on the foundational SonoSAM1, designed for object segmentation in ultrasound imagery. The primary function of SonoSAMTrack is to delineate anatomical structures, lesions, and other critical regions within ultrasound images. Additionally, a more simplified version, SonoSAMLite, has also been introduced.
- In January 2024, Canon launched Aplio me, a cutting-edge shared-service ultrasound system engineered to meet the diverse needs of users across various medical environments. This exceptionally portable and lightweight system caters to ultrasound experts who prioritize high efficiency in their workflows and seek advanced standard solutions, suitable for settings ranging from small clinics to major hospitals. Furthermore, Canon Medical Systems Corporation partnered with Olympus Corporation to collaborate on Endoscopic Ultrasound Systems. Under this agreement, Canon Medical will focus on developing and manufacturing diagnostic ultrasound systems for Endoscopic Ultrasonography, while Olympus will manage sales and marketing activities. This partnership aims to combine Canon's Aplio i800 diagnostic ultrasound system with Olympus' Ultrasound Endoscope, delivering advanced equipment for Endoscopic Ultrasound and ensuring high-quality imaging diagnostics.
- In November 2023, Canon Medical Systems introduced significant upgrades to its CT product line, launching two new scanners. The introduction includes a premium model, the Aquilion ONE / INSIGHT Edition, and a high-efficiency model, the Aquilion Serve SP, both showcased at the Radiological Society of North America Congress (RSNA) in Chicago, Illinois.
- In February 2023, GE Healthcare announced its agreement to acquire Caption Health, Inc., a privately held AI healthcare provider. Caption Health specializes in developing clinical applications that assist with early disease diagnosis, utilizing AI to enhance ultrasound scans.
- In May 2023, Koninklijke Philips N.V. launched the Philips CT 3500, a high-end CT system designed to meet the needs of routine radiology and high-volume screening programs.
Market Concentration & Characteristics:
The Imaging Services Market exhibits a moderate level of concentration, with a few key players holding substantial market shares while numerous smaller companies also compete in various niches. Major players such as GE Healthcare, Siemens Healthineers, Philips, and Canon Medical Systems dominate the landscape, leveraging their extensive resources, advanced technology portfolios, and established brand reputations to maintain competitive advantages. These companies focus on continuous innovation, regularly introducing cutting-edge imaging solutions that integrate artificial intelligence and advanced data analytics to enhance diagnostic accuracy and operational efficiency. Despite the presence of these dominant firms, the market remains characterized by a diverse array of smaller companies that specialize in specific imaging technologies or serve regional markets, contributing to a dynamic competitive environment. This fragmentation allows for innovation and specialization, particularly in emerging markets like Asia-Pacific, where local firms are addressing unique healthcare challenges. Additionally, regulatory compliance and technological advancements shape market characteristics, compelling companies to invest in high-quality imaging solutions while navigating complex approval processes. As healthcare systems increasingly prioritize efficient and effective diagnostic tools, the concentration of market power among major players, coupled with the presence of nimble smaller firms, creates a balanced yet competitive landscape that fosters ongoing innovation and growth in the Imaging Services Market.
Report Coverage:
This report provides a comprehensive analysis of the Imaging Services Market, encompassing various facets such as market dynamics, trends, and competitive landscapes. It covers segmentation based on product type, technology, end-user, and regional dynamics, offering insights into key market segments like X-ray, MRI, and AI-assisted imaging solutions. The report delves into regional analyses, highlighting the dominant positions of North America and Europe, as well as the rapid growth potential in the Asia-Pacific region. Additionally, it examines market drivers, challenges, and opportunities, providing a balanced view of the factors influencing market growth. The competitive analysis offers insights into major players, their strategies, and market concentration, revealing how established companies leverage innovation and partnerships to maintain their positions. The report also addresses regulatory and compliance issues that impact market entry and operational strategies. By synthesizing data from industry reports, market studies, and expert interviews, this report serves as a valuable resource for stakeholders seeking to understand the current landscape of the Imaging Services Market and make informed decisions about investment, development, and strategic planning. Overall, it aims to equip readers with actionable insights and a clear understanding of the market's trajectory in the coming years.
Future Outlook:
- The Imaging Services Market is expected to grow at a robust through 2032.
- North America will continue to hold the largest market share, driven by advanced healthcare infrastructure.
- The Asia-Pacific region will witness the fastest growth due to increasing healthcare investments.
- Integration of AI and machine learning technologies will enhance diagnostic accuracy and efficiency.
- Demand for portable and point-of-care imaging solutions will rise significantly.
- Regulatory environments will become more supportive, facilitating faster technology approvals.
- Collaborative partnerships between technology firms and healthcare providers will increase.
- The aging population will drive the need for imaging services, particularly for chronic disease management.
- Growing awareness about early diagnosis will further propel market growth.
- Innovations in imaging modalities, such as 3D and hybrid imaging, will reshape the competitive landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Imaging Services Market?
How much is the market expected to grow by 2032?
What are the main factors driving market growth?
Which region leads the Imaging Services Market?
Which region is expected to see significant growth in the coming years?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 533,995 million → Forecast year: USD 864,038.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Imaging Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Imaging Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Imaging Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Imaging Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Imaging Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Imaging Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Imaging Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Imaging Services Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 533,995 million → Forecast year: USD 864,038.14 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Imaging Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Imaging Services Geographic Market Outlook
- 13.1 Regional Market Size and Share, 2032
- 13.2 Regional Market Forecast
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Imaging Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Imaging Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2032
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
