
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Immunomodulator Market Size 2024 | USD 88579.7 Million |
| Immunomodulator Market, CAGR | 6.7% |
| Immunomodulator Market Size 2032 | USD 148816 Million |
Market Overview:
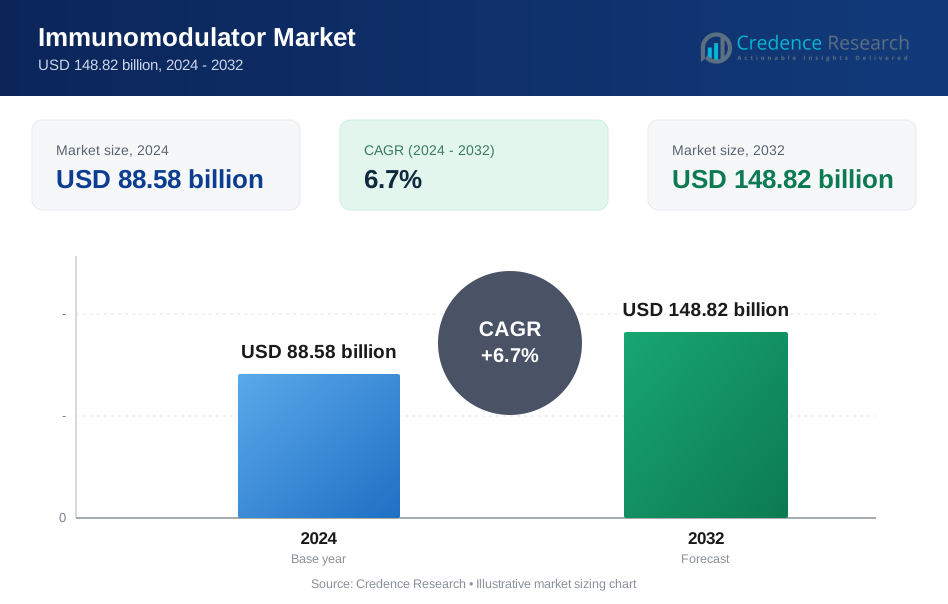
The Immunomodulator Market is projected to grow from USD 88579.7 million in 2024 to an estimated USD 148816 million by 2032, with a compound annual growth rate (CAGR) of 6.7% from 2024 to 2032.
The growth of the immunomodulator market is driven by several key factors. The increasing prevalence of chronic diseases such as autoimmune disorders, cancer, and infectious diseases creates a higher demand for effective immunomodulatory treatments. Additionally, substantial investments in research and development by pharmaceutical companies are advancing the efficacy and scope of immunomodulators. The trend towards personalized medicine, which tailors’ treatments based on individual genetic profiles, is also fueling market growth. Furthermore, the aging global population is leading to a rise in immune system-related health conditions, which enhances the need for these therapies. The expansion of healthcare infrastructure and growing healthcare expenditure worldwide are additional contributors to the market's development.
In the regional landscape, North America holds the largest share of the immunomodulator market, driven by its advanced healthcare infrastructure, substantial R&D investments, and high prevalence of chronic diseases. The United States, in particular, plays a significant role in market growth due to its strong pharmaceutical sector and considerable healthcare spending. Europe also represents a significant market, bolstered by increased healthcare initiatives and a growing emphasis on immunotherapy. The Asia-Pacific region is emerging as a key growth area, with rising population figures, improving healthcare facilities, and increasing healthcare spending in countries such as China and India. Meanwhile, Latin America and the Middle East & Africa are experiencing gradual market expansion, supported by the development of healthcare infrastructure and heightened awareness of immunomodulatory treatments.
Market Drivers:
Increasing Prevalence of Chronic Diseases:
The rising prevalence of chronic diseases such as autoimmune disorders, cancer, and infectious diseases is a primary driver of the immunomodulator market. For instance, according to the Centers for Disease Control and Prevention (CDC), 42% of American adults have 2 or more chronic conditions, and 12% have at least 5 chronic conditions. As these conditions become more widespread, the demand for effective immunomodulatory treatments grows. Autoimmune disorders, where the immune system mistakenly attacks healthy cells, and cancers, which often involve immune system dysfunction, require advanced therapeutic approaches to modulate immune responses. Immunomodulators play a crucial role in managing these diseases by altering the immune system's activity to achieve desired therapeutic effects. The increasing incidence of these health conditions globally drives the need for innovative treatments that can better manage or potentially cure these complex disorders.
Advancements in Research and Development:
The significant investments in research and development (R&D) by pharmaceutical companies are accelerating advancements in the immunomodulator market. R&D efforts are focused on discovering and developing new immunomodulatory agents with improved efficacy and safety profiles. These advancements include the development of novel biologics, small molecules, and combination therapies that target specific immune pathways or modulate immune responses in more precise ways. The continuous progress in understanding the immune system's mechanisms and how various drugs interact with it is crucial in enhancing the effectiveness of immunomodulators. This dynamic R&D environment not only leads to innovative treatment options but also fosters competition and drives market growth by introducing more advanced and effective therapies. For instance, data from Citeline's Pharma R&D Annual Review 2024 shows that major pharmaceutical companies are maintaining robust pipelines focused on immunology and related areas. Pfizer, for example, had 204 pipeline drugs in development as of January 2024, while Johnson & Johnson had 149. These extensive pipelines likely include numerous immunomodulatory agents at various stages of development.
Growing Focus on Personalized Medicine:
The shift towards personalized medicine is another significant driver of the immunomodulator market. Personalized medicine involves tailoring treatments based on individual genetic profiles, which allows for more targeted and effective therapeutic interventions. In the context of immunomodulators, this approach enables the development of treatments that are specifically designed to address the unique immune system characteristics of individual patients. Personalized medicine aims to optimize therapeutic outcomes and minimize adverse effects by considering a patient’s genetic makeup, lifestyle, and environmental factors. This trend is increasingly influencing the development and application of immunomodulatory therapies, leading to enhanced precision in treatment and contributing to market growth.
Expansion of Healthcare Infrastructure and Expenditure:
The expansion of healthcare infrastructure and increasing healthcare expenditure globally are pivotal drivers of the immunomodulator market. As countries invest in improving their healthcare systems and increase spending on healthcare services, there is greater access to advanced medical treatments, including immunomodulators. Improved healthcare infrastructure facilitates the availability and distribution of new therapies, while higher healthcare expenditure supports the affordability and accessibility of these treatments. This growth in infrastructure and spending is particularly notable in emerging markets, where rising economic development and healthcare investments are broadening access to advanced therapies and driving the adoption of immunomodulatory treatments.
Market Trends:
Emergence of Biologic Therapies:
One of the prominent trends in the immunomodulator market is the increasing adoption of biologic therapies. Biologics, including monoclonal antibodies, cytokines, and immune checkpoint inhibitors, are gaining prominence due to their ability to target specific immune system components with high precision. These therapies offer significant advantages over traditional small molecule drugs, including enhanced efficacy and reduced side effects. For instance, The Food and Drug Administration's (FDA) Center for Drug Evaluation and Research (CDER) reports a steady increase in biologic approvals. In 2023, 17 out of 55 novel drug approvals (31%) were biologics, up from 13 out of 50 (26%) in 2022, demonstrating the growing importance of these therapies. The development of biologics has revolutionized the treatment landscape for various autoimmune disorders, cancers, and chronic inflammatory conditions. As research continues to uncover new biological targets and mechanisms, the market for biologic immunomodulators is expected to expand further, driving innovation and offering more personalized treatment options.
Integration of Digital Technologies:
The integration of digital technologies into immunomodulator therapy is another significant trend shaping the market. Advances in digital health tools, such as wearable devices, mobile health applications, and remote monitoring systems, are enhancing the management and administration of immunomodulatory treatments. These technologies facilitate real-time monitoring of patient responses and side effects, enabling more personalized and timely adjustments to treatment regimens. Digital platforms also support patient engagement and adherence by providing educational resources and tracking capabilities. The growing use of digital technologies in healthcare is expected to improve patient outcomes and streamline treatment processes, thereby influencing the overall growth and evolution of the immunomodulator market.
Rising Interest in Combination Therapies:
The trend towards combination therapies is becoming increasingly prevalent in the immunomodulator market. Combination therapies involve using multiple drugs or treatment modalities simultaneously to achieve a synergistic effect and enhance therapeutic outcomes. This approach is particularly relevant for managing complex diseases where single-agent therapies may not be sufficient. In the context of immunomodulators, combining different agents can improve efficacy, reduce resistance, and address multiple aspects of a disease. Combining immunomodulatory drugs with chemotherapy or targeted therapies can enhance overall treatment effectiveness for cancer patients. For instance, data from the Pharmaceutical Research and Manufacturers of America (PhRMA) 2024 Biopharmaceutical Research Industry Profile reveals that among the 8,000+ medicines in clinical development globally, over 40% are combination therapies or involve multiple mechanisms of action, with immunomodulators featuring prominently. The growing emphasis on combination therapies reflects the ongoing efforts to optimize treatment strategies and address the limitations of existing therapies.
Focus on Emerging Markets:
The focus on emerging markets is another key trend in the immunomodulator sector. As economic development accelerates and healthcare infrastructure improves in regions such as Asia-Pacific, Latin America, and the Middle East & Africa, there is increasing demand for advanced medical treatments, including immunomodulators. Pharmaceutical companies are expanding their presence in these regions to capitalize on the growing market potential and address the rising need for effective therapies. The increasing affordability of healthcare, improved access to medicines, and rising awareness of immune-related diseases contribute to the growth of the immunomodulator market in these emerging regions. This trend highlights the shifting global dynamics and the opportunities for market expansion beyond traditional healthcare markets.
Market Restraints and Challenges:
High Cost of Treatment:
One of the significant restraints in the immunomodulator market is the high cost associated with advanced therapies, particularly biologics. The development and production of these treatments involve complex processes and high research and development expenditures, which are reflected in their price. This high cost can limit accessibility for patients, especially in regions with lower healthcare budgets or for those without comprehensive insurance coverage. As a result, the affordability of immunomodulatory treatments remains a substantial barrier, potentially restricting market growth and limiting the widespread adoption of these therapies.
Regulatory Challenges:
The regulatory landscape presents another challenge for the immunomodulator market. Navigating the complex and often lengthy approval processes for new immunomodulatory drugs can be time-consuming and costly for pharmaceutical companies. Regulatory agencies require extensive clinical trial data to demonstrate the safety and efficacy of new therapies, which can delay the introduction of innovative treatments into the market. Additionally, varying regulatory requirements across different regions can complicate global market entry and increase the burden on companies seeking to launch their products internationally.
Adverse Effects and Safety Concerns:
Adverse effects and safety concerns associated with immunomodulatory therapies pose significant challenges. While these treatments can be highly effective, they may also lead to severe side effects or unintended immune system reactions. Managing these adverse effects requires careful monitoring and, in some cases, dose adjustments or discontinuation of therapy. The potential for serious side effects can impact patient compliance and limit the use of certain immunomodulators. Ensuring the safety and tolerability of these treatments remains a critical concern for both healthcare providers and patients.
Market Competition and Innovation Pressure:
The intense competition and pressure for innovation within the immunomodulator market present additional challenges. The rapid pace of technological advancements and the continuous emergence of new therapies require companies to stay at the forefront of research and development. This competitive environment can lead to significant investment in R&D and marketing strategies, potentially straining resources and impacting profitability. Companies must navigate this competitive landscape while striving to offer differentiated and effective treatments to maintain a competitive edge.
Market Segmentation Analysis:
By Product
The immunomodulator market can be segmented by product into biologics, small molecules, and other emerging therapies. Biologics, including monoclonal antibodies, cytokines, and immune checkpoint inhibitors, hold the largest share due to their high efficacy and targeted action. These products are particularly prominent in the treatment of cancer and autoimmune disorders. Small molecules, such as disease-modifying antirheumatic drugs (DMARDs) and immunosuppressants, also play a significant role in managing various immune-mediated conditions. The segment of emerging therapies includes novel treatments currently in development, such as gene therapies and new immunomodulatory agents, which are expected to grow as innovation in the field progresses.
By Application
The market is segmented by application into autoimmune diseases, cancer, infectious diseases, and others. Autoimmune diseases, such as rheumatoid arthritis, lupus, and multiple sclerosis, represent a major application area, driven by the increasing prevalence and need for effective therapies. Cancer treatment also constitutes a significant segment, with immunomodulators being used to enhance the body’s immune response against tumors. Infectious diseases, including chronic viral infections and certain bacterial infections, benefit from immunomodulatory treatments that can boost immune system activity or modify immune responses. The "others" category includes a variety of conditions where immunomodulators are used, such as allergic disorders and transplant rejection. Each segment is influenced by factors such as disease prevalence, ongoing clinical research, and advancements in therapeutic technologies, which collectively shape the market dynamics.
Segmentation:
By Product
- Biologics,
- Small molecules,
- Other emerging therapies.
By Application
- Autoimmune diseases,
- Cancer,
- Infectious diseases,
- Others
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America dominates the immunomodulator market, holding the largest market share of approximately 45%. The United States is a key contributor, driven by its advanced healthcare infrastructure, significant R&D investments, and high prevalence of chronic diseases such as autoimmune disorders and cancer. The presence of major pharmaceutical companies and biotech firms in the region further bolsters market growth. Additionally, the strong focus on innovative treatments, along with favorable regulatory frameworks and high healthcare spending, supports the expansion of immunomodulators. The market is expected to continue growing as new therapies emerge and personalized medicine gains traction.
Europe
Europe holds a substantial market share of around 30%, with significant contributions from countries like Germany, France, and the United Kingdom. The European market benefits from a robust healthcare system, increasing investments in healthcare R&D, and a rising focus on precision medicine. The approval of advanced immunomodulatory therapies and the growing incidence of chronic diseases are driving demand. The European Union’s regulatory support and funding for medical research also play a crucial role in fostering market growth. Regional collaborations and partnerships among pharmaceutical companies and research institutions further enhance the market’s development.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth, accounting for approximately 20% of the global immunomodulator market. Countries like China and India are emerging as key markets due to their large populations, improving healthcare infrastructure, and rising healthcare expenditure. The increasing prevalence of chronic diseases and the expansion of pharmaceutical and biotechnology sectors in these countries are significant growth drivers. Government initiatives to improve healthcare access and the growing middle-class population are also contributing to market expansion. The region’s dynamic and evolving healthcare landscape presents substantial opportunities for market players seeking to enter or expand their presence in these emerging markets.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively represent about 5% of the global market share. In Latin America, countries like Brazil and Mexico are seeing gradual market growth driven by improving healthcare access and rising awareness of immunomodulatory treatments. In the Middle East & Africa, growing investments in healthcare infrastructure and increasing healthcare spending are supporting market development. However, challenges such as economic instability and varying healthcare standards may impact the rate of market growth in these regions. Despite these challenges, there is a growing demand for advanced immunomodulatory therapies as healthcare systems continue to evolve and expand.
Key Player Analysis:
- Abbott
- Amgen Inc.
- Biogen
- Bristol-Myers Squibb Company
- Eli Lilly and Company
- Hoffmann-La Roche Ltd
- Johnson & Johnson Services, Inc.
- Merck & Co., Inc.
- Novartis AG
- Pfizer Inc
Competitive Analysis:
The immunomodulator market is characterized by intense competition among key players focused on innovation and market expansion. Leading pharmaceutical companies, such as AbbVie, Bristol-Myers Squibb, and Merck & Co., dominate the market with their extensive portfolios of established immunomodulatory therapies and significant investments in R&D. These companies leverage advanced technologies and clinical trials to develop novel treatments and maintain a competitive edge. Emerging biotech firms, like Ability Biologics and Odyssey Therapeutics, are also making substantial impacts by introducing cutting-edge therapies and securing substantial funding. Competition is further heightened by the rapid pace of technological advancements and the growing demand for personalized medicine. Companies must navigate complex regulatory environments and address safety concerns while striving to deliver effective and differentiated products. The dynamic landscape requires continuous innovation and strategic partnerships to capture market share and address evolving patient needs.
Recent Developments:
- In March 2024, Ability Biologics secured USD 18 million in seed funding. This investment will be allocated towards the development of innovative and highly targeted immunomodulators.
- In February 2024, Nuvig Therapeutics, Inc., based in the United States, began early-stage trials for its advanced NVG-2089 immunomodulator, designed for patients with inflammatory autoimmune diseases.
- In December 2023, Odyssey Therapeutics, a biotechnology company focused on advanced precision immunomodulators and oncology therapies, successfully raised USD 101 million in a Series C funding round.
- In August 2023, Janssen Pharmaceuticals Companies, headquartered in Belgium and part of Johnson & Johnson, received FDA approval for TALVEY, a first-in-class bispecific therapy for treating adult patients with heavily pretreated multiple myeloma.
- In February 2023, Sage Therapeutics and Biogen announced that the FDA accepted the new drug application for zuranolone, aimed at treating postpartum depression and major depressive disorder (MDD).
Market Concentration & Characteristics:
The immunomodulator market is characterized by a moderate to high level of concentration, with several large pharmaceutical and biotechnology companies dominating the space. Major players such as AbbVie, Bristol-Myers Squibb, and Merck & Co. hold substantial market shares due to their extensive portfolios and significant investments in research and development. These companies leverage their established distribution networks and regulatory expertise to maintain a competitive edge. The market also features a dynamic landscape with numerous emerging biotech firms introducing innovative therapies. This influx of new entrants intensifies competition and drives rapid advancements in treatment options. The market is characterized by high R&D costs and a strong emphasis on technological innovation, particularly in biologics and personalized medicine. Additionally, the regulatory environment plays a crucial role, influencing market entry and product development through stringent approval processes and compliance requirements.
Report Coverage:
The research report offers an in-depth analysis based on By Product and By application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to experience robust growth, driven by increasing prevalence of chronic diseases and autoimmune disorders.
- Advancements in biologics and personalized medicine will lead to the development of more targeted and effective immunomodulatory therapies.
- Emerging biotech firms will continue to introduce innovative products, intensifying competition and driving market evolution.
- Rising investments in research and development will foster new drug discoveries and enhance existing therapies.
- The expansion of healthcare infrastructure in emerging markets will broaden access to immunomodulatory treatments.
- Integration of digital health technologies will improve patient management and treatment adherence.
- Regulatory agencies will play a crucial role in shaping market dynamics through evolving approval processes and compliance requirements.
- The trend towards combination therapies will grow, offering enhanced treatment options for complex diseases.
- Increased focus on personalized medicine will lead to more tailored and effective immunomodulatory interventions.
- Collaboration and strategic partnerships between pharmaceutical companies and research institutions will accelerate innovation and market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the immunomodulator market?
What factors are driving the growth of the immunomodulator market?
Which region holds the largest share of the immunomodulator market?
What challenges does the immunomodulator market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Immunomodulator Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Immunomodulator Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 88.58 billion → 2032: USD 148.82 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Immunomodulator Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Immunomodulator Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Immunomodulator Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Immunomodulator Market Drivers
- 3.3 Immunomodulator Market Restraints & Challenges
- 3.4 Immunomodulator Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Immunomodulator Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Immunomodulator Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Immunomodulator category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Immunomodulator Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Immunomodulator Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Immunomodulator market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Immunomodulator Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Immunomodulator Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Immunomodulator Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Immunomodulator (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Immunomodulator Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Immunomodulator Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Immunomodulator Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Immunomodulator Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Immunomodulator Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Immunomodulator Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Immunomodulator Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Immunomodulator Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Immunomodulator Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
