
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Automotive Lead Acid Battery Market Size 2023 | USD 609.74 million |
| India Automotive Lead Acid Battery Market, CAGR | 10.3% |
| India Automotive Lead Acid Battery Market Size 2032 | USD 1,475.08 million |
Market Overview
India Automotive Lead Acid Battery market size was valued at USD 609.74 million in 2023 and is anticipated to reach USD 1,475.08 million by 2032, at a CAGR of 10.3% during the forecast period (2023-2032).
The India automotive lead acid battery market is witnessing substantial growth, driven by the rising demand for passenger and commercial vehicles, coupled with the increasing adoption of electric rickshaws and two-wheelers across urban and rural regions. The affordability, reliability, and widespread availability of lead acid batteries make them a preferred choice for both OEMs and aftermarket consumers. Additionally, government initiatives promoting clean mobility and localized battery manufacturing are fostering market expansion. Technological advancements such as enhanced flooded batteries (EFB) and improved recyclability further support the sustainability and efficiency of lead acid batteries. A growing trend towards vehicle electrification, especially in the entry-level segment, is also boosting battery replacement rates and driving continuous innovation in battery performance and lifespan. Moreover, the rising penetration of organized retail and e-commerce platforms is streamlining battery distribution, enhancing consumer accessibility. These factors collectively contribute to the consistent upward trajectory of the automotive lead acid battery market in India.
The India automotive lead acid battery market is geographically diverse, with significant activity concentrated across the northern, western, and southern regions due to rising vehicle ownership, industrial growth, and expanding transportation networks. Urban centers such as Delhi, Mumbai, Chennai, and Bengaluru serve as key demand hubs, supported by strong aftermarket services and a high density of passenger and commercial vehicles. Meanwhile, semi-urban and rural areas are witnessing increased adoption of two-wheelers and electric rickshaws, further driving battery demand. The market is supported by a mix of established domestic and international players who offer a broad portfolio of products catering to various vehicle types and consumer needs. Key players in the market include Amara Raja Energy & Mobility Limited, Exide Industries Ltd., Luminous Power Technologies Pvt. Ltd., TATA Green Batteries, and Clarios, among others. These companies are focusing on technological enhancements, distribution expansion, and sustainable practices to strengthen their market presence across India.
Market Insights
- The India automotive lead acid battery market was valued at USD 609.74 million in 2023 and is projected to reach USD 1,475.08 million by 2032, growing at a CAGR of 10.3% from 2023 to 2032.
- The Global Automotive Lead Acid Battery market was valued at USD 21,181.34 million in 2023 and is expected to reach USD 43,052.54 million by 2032, growing at a CAGR of 8.2% from 2023 to 2032.
- Increasing demand for electric rickshaws and two-wheelers drives the growth of lead acid batteries in cost-sensitive transportation segments.
- Enhanced Flooded Batteries (EFBs) are gaining traction due to their compatibility with start-stop systems and improved performance in modern vehicles.
- The shift towards organized retail and online distribution channels is improving accessibility and customer engagement.
- Lithium-ion batteries pose a competitive threat, with rising adoption in electric vehicles and premium segments.
- Environmental concerns over informal recycling practices are challenging the industry to adopt more sustainable practices.
- The Northern region dominates the market, with strong growth in passenger cars, while the Southern region shows promising growth due to the rise in electric two-wheelers.
Report Scope
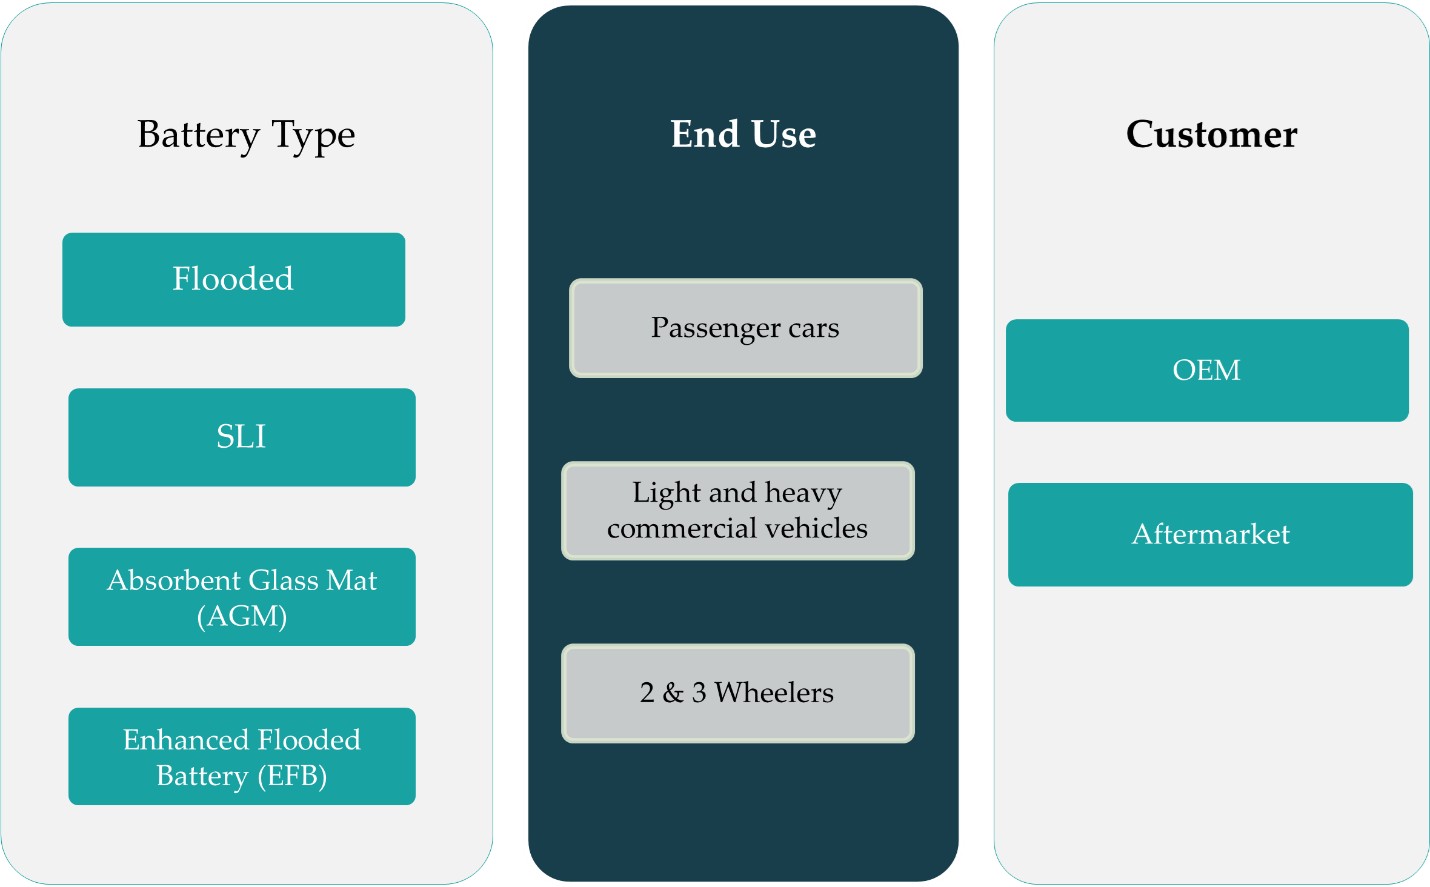
This report segments the India Automotive Lead Acid Battery Market as follows:
Market Drivers
Growing Vehicle Ownership and Expanding Automotive Industry
The consistent rise in vehicle ownership across India remains a fundamental driver for the automotive lead acid battery market. Increasing disposable incomes, improved road infrastructure, and government schemes supporting rural mobility have led to a significant surge in the sales of two-wheelers, passenger cars, and commercial vehicles. For instance, India’s automotive sector is witnessing increased investment in large-scale battery manufacturing to meet rising demand for automotive, two-wheeler, and energy storage applications. This expansion in India’s vehicle parc creates a parallel increase in the demand for lead acid batteries, which are widely used in ignition, lighting, and starting (SLI) applications. The cost-effectiveness and proven reliability of lead acid batteries make them a preferred power source for both OEMs and aftermarket users. Furthermore, the growth in entry-level and budget vehicle segments-particularly in semi-urban and rural areas-continues to fuel the demand for conventional battery solutions, solidifying the role of lead acid batteries in India’s evolving mobility landscape.
Supportive Government Policies and Local Manufacturing Initiatives
Government initiatives such as the Make in India campaign and Production Linked Incentive (PLI) schemes for advanced battery storage are indirectly benefiting the lead acid battery market by encouraging local manufacturing and reducing reliance on imports. For instance, the Indian government has introduced several policy reforms in Battery Waste Management Rules 2022 to promote battery waste refurbishment using new and innovative technologies. Additionally, the regulatory environment continues to support recycling and safe disposal of lead acid batteries, reinforcing their sustainability credentials. Programs that promote cleaner transport alternatives and battery recycling not only align with environmental goals but also enhance consumer awareness and trust in domestic battery brands. Furthermore, the establishment of dedicated battery testing centers, skill development programs, and subsidies for EV adoption indirectly spur demand for lead acid batteries in specific applications. These policy measures, combined with private investments in battery production infrastructure, are creating a favorable ecosystem for the growth and modernization of India’s automotive lead acid battery market.
Robust Demand from the Replacement Market
India’s large base of operational vehicles generates a substantial aftermarket demand for battery replacements, especially given the limited lifespan of conventional lead acid batteries. Vehicle owners typically replace batteries every 3 to 5 years, and with the continuous expansion of the vehicle population, the frequency of replacements is rising. The unorganized nature of battery sales in many parts of India further enhances opportunities for both local and branded battery manufacturers. Moreover, the demand is not limited to private vehicles-commercial fleets, taxis, and logistics vehicles also contribute significantly to the replacement cycle due to their higher usage rates. This steady and recurring demand from the replacement market acts as a strong growth catalyst for the automotive lead acid battery sector, providing consistent revenue streams for suppliers and distributors across the country.
Widespread Use in Electric Rickshaws and Low-Speed EVs
The rapid adoption of electric rickshaws (e-rickshaws) and other low-speed electric vehicles across urban and semi-urban regions is another major factor boosting the demand for lead acid batteries. These vehicles primarily use lead acid batteries due to their low cost, easy availability, and compatibility with local charging infrastructure. With state governments and local authorities increasingly promoting e-mobility for last-mile connectivity, the sales of e-rickshaws and battery-operated carts have surged. This trend supports the proliferation of lead acid batteries, especially in price-sensitive regions where lithium-ion solutions remain cost-prohibitive. As more startups and local assemblers enter the e-rickshaw segment, the dependency on lead acid batteries continues, strengthening their market relevance despite technological transitions in the EV landscape.
Market Trends
Shift Toward Enhanced Flooded Batteries (EFBs) for Improved Performance
One of the prominent trends in the India automotive lead acid battery market is the increasing adoption of Enhanced Flooded Batteries (EFBs), especially in modern passenger vehicles equipped with start-stop technology. EFBs offer better charge acceptance, longer cycle life, and improved performance under high-load conditions compared to conventional flooded batteries. As Indian consumers become more quality-conscious and automotive manufacturers upgrade their vehicle models, EFBs are gaining popularity in both OEM and aftermarket segments. Additionally, the growing emphasis on fuel efficiency and emission reduction encourages the use of batteries with improved technological attributes. This trend reflects a broader industry shift toward integrating advanced battery systems that support eco-friendly and energy-efficient mobility solutions without compromising affordability.
Growth of Electric Rickshaws and Two-Wheelers Driving Demand
The expansion of India’s electric vehicle ecosystem-particularly the surge in electric rickshaws and low-speed electric two-wheelers-continues to fuel demand for lead acid batteries. These vehicles predominantly rely on lead acid technology due to its cost advantage, established supply chain, and compatibility with low-cost charging solutions. For instance, India’s e-rickshaw market is expected to grow to 1 million units by 2025, with 98% currently powered by lead-acid batteries. The adoption of e-rickshaws has been especially significant in Tier II and Tier III cities, where public transportation infrastructure is still developing. Furthermore, numerous small-scale assemblers and regional vehicle manufacturers prefer lead acid batteries for their ease of integration and relatively simple maintenance requirements. This segment contributes substantially to overall market volume, reinforcing the position of lead acid batteries in India’s evolving urban mobility ecosystem despite the rise of lithium-ion alternatives.
Expansion of Organized Retail and Online Distribution Channels
The distribution landscape for automotive lead acid batteries in India is undergoing a transformation, driven by the expansion of organized retail outlets and the emergence of online battery marketplaces. Previously dominated by unorganized local vendors, the market is now seeing a growing presence of branded showrooms and authorized service centers offering genuine battery replacements with warranty coverage and installation support. For instance, India’s automotive battery market is expanding due to increasing demand from commercial fleet operators seeking reliable energy storage solutions. E-commerce platforms specializing in automotive components are also gaining traction by offering convenience, transparent pricing, and doorstep service, particularly in metro and Tier I cities. These developments not only improve customer experience but also help organized players penetrate deeper into the replacement battery market, enhancing brand visibility and trust among tech-savvy consumers.
Focus on Recycling and Circular Economy Integration
Sustainability is becoming a key focus in India’s automotive lead acid battery market, with increasing attention toward recycling and reuse. Lead acid batteries are among the most recycled products globally, and India is aligning with this trend through stricter environmental regulations and the promotion of circular economy models. Several manufacturers are investing in reverse logistics and setting up dedicated recycling facilities to recover lead and other valuable materials, thereby reducing environmental impact and lowering raw material costs. Government agencies and industry bodies are also encouraging public-private partnerships to improve the battery recycling ecosystem. This trend ensures long-term sustainability, regulatory compliance, and responsible waste management while reinforcing the economic value of used lead acid batteries in the supply chain.
Market Challenges Analysis
Rising Competition from Lithium-Ion Battery Technology
One of the most significant challenges confronting the India automotive lead acid battery market is the growing penetration of lithium-ion batteries, especially in electric vehicle (EV) applications. As the government promotes EV adoption through favorable policies, subsidies, and infrastructure development, lithium-ion batteries are increasingly preferred for their higher energy density, faster charging capability, and longer lifecycle. Although lead acid batteries remain dominant in cost-sensitive segments such as e-rickshaws and entry-level vehicles, the rapid technological advancements and declining costs of lithium-ion batteries are narrowing the price-performance gap. For instance, India’s lithium-ion battery manufacturing landscape is expanding, with projected investments exceeding $2.2 billion to establish domestic production capacity. This shift threatens the long-term demand for traditional lead acid solutions, particularly in urban markets where end-users are becoming more aware of performance benefits and environmental considerations. As more OEMs transition to advanced battery chemistries, lead acid battery manufacturers must innovate or diversify their portfolios to remain competitive in the evolving automotive energy landscape.
Environmental and Safety Concerns in Informal Recycling Practices
Another critical challenge facing the Indian lead acid battery market is the prevalence of unorganized and informal recycling practices, which pose significant environmental and health risks. Despite lead acid batteries being highly recyclable, a substantial portion of battery recycling in India still occurs in unregulated backyard units lacking proper safety standards and pollution controls. These operations often result in lead contamination, unsafe working conditions, and regulatory non-compliance, tarnishing the industry’s sustainability credentials. While the government has introduced Extended Producer Responsibility (EPR) guidelines and stricter environmental norms, enforcement remains inconsistent across regions. This situation creates reputational risks for established manufacturers and deters potential foreign investment in the sector. To overcome this challenge, the industry must prioritize formal recycling infrastructure, enhance supply chain transparency, and collaborate with regulatory bodies to ensure environmentally responsible end-of-life battery management. Addressing these concerns is essential for sustainable market growth and public trust in lead acid battery technology.
Market Opportunities
The India automotive lead acid battery market presents significant growth opportunities due to the expanding vehicle parc and increasing demand for cost-effective energy storage solutions. As vehicle ownership continues to rise in both urban and rural areas, the aftermarket segment for battery replacements is expected to witness substantial growth. This creates consistent revenue potential for manufacturers and distributors, particularly in Tier II and Tier III cities where affordability remains a key consideration. Moreover, the growing penetration of shared mobility services, including taxis and fleet operators, contributes to higher battery usage and more frequent replacement cycles. These trends, coupled with the widespread application of lead acid batteries in two-wheelers, commercial vehicles, and tractors, offer considerable room for market expansion. The preference for lead acid batteries in price-sensitive segments ensures continued relevance despite advancements in competing technologies.
In addition, India’s push toward local manufacturing and self-reliance under initiatives like “Make in India” provides opportunities for domestic players to scale operations and meet rising demand efficiently. Companies investing in modern production facilities, automation, and compliance with environmental norms are better positioned to benefit from government incentives and evolving industry standards. There is also growing scope in the organized retail and digital distribution channels, where battery brands can enhance consumer engagement through service reliability and warranty-backed products. Furthermore, increased awareness around proper recycling and extended producer responsibility (EPR) norms has opened up avenues for companies to invest in closed-loop systems, thereby turning sustainability into a competitive advantage. With advancements in lead acid battery technology, such as longer cycle life and better resistance to deep discharge, the market is poised to tap into emerging needs within electric mobility and auxiliary power applications. These factors collectively provide a favorable landscape for sustained growth and innovation in the Indian automotive lead acid battery market.
Market Segmentation Analysis:
By Battery Type:
The India automotive lead acid battery market is segmented by battery type into Flooded, Starting, Lighting, and Ignition (SLI), Absorbent Glass Mat (AGM), and Enhanced Flooded Battery (EFB). Among these, flooded batteries continue to dominate due to their cost-effectiveness, wide availability, and suitability for basic automotive applications. These batteries are particularly favored in rural areas and in vehicles that do not demand high-end electrical support. SLI batteries, which power the ignition, lights, and other electronics, hold a significant share in the passenger and commercial vehicle segments due to their reliability and affordability. Meanwhile, AGM batteries are gaining traction in premium and utility vehicles, as they offer better resistance to vibration and support deep-cycle usage. EFBs are emerging as a key trend, driven by their compatibility with start-stop systems used in modern fuel-efficient vehicles. Their higher durability and improved charge acceptance make them ideal for urban driving conditions, contributing to their steady growth in the Indian automotive landscape.
By End Use:
Based on end use, the market is segmented into passenger cars, light and heavy commercial vehicles, and 2 & 3 wheelers. The passenger car segment accounts for a substantial share, supported by growing vehicle ownership and frequent battery replacement needs in personal transportation. Urbanization, rising income levels, and availability of affordable car models continue to drive this segment. The commercial vehicle segment, including light and heavy-duty vehicles, also contributes significantly due to the high usage intensity and operational demands that lead to faster battery wear and tear. In particular, logistics and transportation fleets require reliable power sources, making lead acid batteries a dependable choice. Additionally, the 2 & 3 wheelers segment-especially electric scooters and e-rickshaws-is experiencing strong demand for lead acid batteries owing to their low initial cost and accessibility in non-metro markets. As mobility preferences evolve and infrastructure improves, each of these end-use segments offers tailored opportunities for lead acid battery manufacturers to capture targeted market share.
Segments:
Based on Battery Type:
- Flooded
- SLI
- Absorbent Glass Mat
- Enhanced Flooded Battery
Based on End Use:
- Passenger cars
- Light and heavy commercial vehicles
- 2 & 3 Wheelers
Based on Customer:
- OEM
- Aftermarket
Based on the Geography:
- Northern
- Western
- Southern
- Eastern
Regional Analysis
Northern region
Northern region held the largest share of the India automotive lead acid battery market, accounting for approximately 32% of the total market. This dominance is primarily attributed to the high concentration of vehicle registrations in states such as Delhi, Punjab, Haryana, and Uttar Pradesh. The dense population, rapid urbanization, and growing demand for both private and commercial vehicles significantly contribute to the replacement battery segment. Moreover, Northern India experiences extreme weather variations, which often reduce battery life and increase the frequency of replacements. The region also has a strong presence of aftermarket retailers and local service centers, supporting continuous demand. Additionally, the rapid expansion of electric rickshaws in cities and semi-urban areas of Northern India further boosts the consumption of lead acid batteries, particularly in the cost-sensitive public transport segment.
Western region
The Western region accounted for around 28% of the market share in 2023 and remains a key hub for both OEM production and aftermarket demand. Maharashtra and Gujarat, in particular, host several automobile manufacturing units and industrial clusters, generating significant demand for automotive lead acid batteries. The well-developed transportation network and the presence of large vehicle fleets including trucks, buses, and taxis enhance the demand for battery replacements. Furthermore, with many logistics companies operating in the region, commercial vehicle uptime remains a priority, leading to more frequent battery maintenance and purchases. The Western region also benefits from relatively higher per capita income, enabling greater sales of passenger cars and SUVs, which use premium battery variants such as EFBs and AGM batteries. This trend is also supported by increasing consumer awareness and the expansion of organized retail and service networks.
Southern region
The Southern region held an estimated 23% share of the market in 2023. States such as Tamil Nadu, Karnataka, and Andhra Pradesh contribute significantly due to high automotive penetration and the growth of urban transportation networks. The region is also a major center for automotive manufacturing, which supports OEM battery sales. Additionally, the widespread adoption of electric two-wheelers and the increasing number of e-rickshaws in Southern cities are boosting demand for lead acid batteries, especially in low-speed EV applications. The region has also seen a steady rise in vehicle ownership in Tier II and Tier III cities, further driving the aftermarket segment. Moreover, government-led initiatives supporting EV adoption in states like Tamil Nadu are expected to continue fostering the need for affordable battery solutions in the coming years.
Eastern region
The Eastern region represented the smallest share of the market, at approximately 17% in 2023, but is expected to grow steadily due to improving infrastructure and rising vehicle ownership in states such as West Bengal, Odisha, Bihar, and Assam. While the market is currently less saturated compared to other regions, there is a strong opportunity in the replacement battery segment as older vehicles continue to dominate the roads. The increasing presence of electric rickshaws and battery-powered carts for last-mile delivery is also creating demand for lead acid batteries in urban and peri-urban areas. However, the dominance of unorganized players and limited penetration of branded battery retailers pose challenges for market expansion. With the development of road networks and improved rural connectivity, the Eastern region holds potential for future growth, especially if supported by organized distribution and consumer education initiatives.
Key Player Analysis
- Amara Raja Energy & Mobility Limited
- Luminous Power Technologies Pvt. Ltd.
- Clarios
- TATA Green Batteries
- SRBATTERY
- EnerSys
- Exide Industries Ltd.
- HBL Power Systems Ltd.
- Innova Power Systems Pvt. Ltd.
- Panasonic Energy India Co. Ltd.
- Johnson Controls
- Robert Bosch LLC
Competitive Analysis
The India automotive lead acid battery market is highly competitive, with both domestic and international players striving to meet the growing demand across various vehicle segments. Leading companies such as Amara Raja Energy & Mobility Limited, Luminous Power Technologies Pvt. Ltd., Clarios, TATA Green Batteries, SRBATTERY, EnerSys, Exide Industries Ltd., HBL Power Systems Ltd., Innova Power Systems Pvt. Ltd., Panasonic Energy India Co. Ltd., Johnson Controls, Robert Bosch LLC dominate the market through innovative products and extensive distribution networks. These companies focus on technological innovation, such as the development of Enhanced Flooded Batteries (EFBs) and Absorbent Glass Mat (AGM) batteries, to cater to the evolving needs of both OEMs and the aftermarket segment. Companies are also investing heavily in expanding their production facilities and improving supply chain efficiencies to meet the rising demand for batteries across various vehicle types, from passenger cars to commercial vehicles and electric rickshaws. Competition is further intensified by the growing shift towards online and organized retail channels, which allow manufacturers to increase their reach and improve customer service. Furthermore, environmental concerns and regulatory pressures are pushing manufacturers to adopt more sustainable practices, such as enhancing battery recycling processes and minimizing the environmental impact of production. This trend is likely to shape future market dynamics as companies strive to align with both consumer demands and government regulations. The rise of lithium-ion batteries in the electric vehicle market also presents a challenge, as these alternatives offer higher efficiency and longer lifespans, prompting lead acid battery manufacturers to innovate and diversify their product offerings.
Recent Developments
- In November 2024, EnerSys showcased the iQ Mini™ battery monitoring device and maintenance-free NexSys® Thin Plate Pure Lead (TPPL) batteries, which offer longer service life and faster recharge rates.
- In July 2024, Exide Industries Ltd. introduced an advanced Absorbent Glass Mat (AGM) battery for Starting, Lighting, and Ignition (SLI) applications in the automotive market. This new battery is designed to deliver enhanced performance, including improved starting power, and potentially longer lifespan compared to traditional lead-acid batteries.
- In August 2023, Clarios, a global leader in advanced low-voltage battery manufacturing and recycling, is acquiring Paragon GmbH & Co. KGaA’s power business, which specializes in batteries and battery management systems for the automotive industry. This acquisition enhances Clarios' engineering capabilities and supports its low-voltage and lithium-ion projects, significantly expanding the team dedicated to developing new low-voltage architectures.
- In May 2023, C&D Technologies, Inc. introduced the Pure Lead Max (PLM) VRLA battery, designed for long lifespan and improved performance in UPS and data center applications.
- In April 2023, the acquisition of IBCS by EnerSys is a strategic move to expand its motive power services and strengthen its presence in the UK market. This addition will enhance EnerSys's range of battery-related services, including installation, maintenance, repair, and replacement.
Market Concentration & Characteristics
The India automotive lead acid battery market is moderately concentrated, with a mix of established domestic and international players. The market is characterized by high competition, as companies strive to meet the increasing demand from the automotive sector, especially with the rise in vehicle production and sales. While a few large players dominate the market, there is still considerable room for regional and smaller companies to grow by offering cost-effective and high-quality products. The market is driven by the expanding automotive industry, the increasing need for reliable power sources, and a shift towards eco-friendly solutions. Additionally, the rise of electric vehicles (EVs) is influencing the market dynamics, encouraging manufacturers to innovate and offer specialized solutions. Despite the presence of leading brands, the market remains fragmented, with continuous technological advancements and price-sensitive consumers shaping the competitive landscape
Report Coverage
The research report offers an in-depth analysis based on Battery Type, End Use, Customer and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for automotive lead acid batteries in India is expected to grow due to the increasing production and sales of vehicles.
- The shift towards electric vehicles (EVs) will drive innovation in lead acid battery technology to support energy storage solutions.
- Regulatory changes focusing on environmental sustainability will encourage manufacturers to improve battery performance and reduce emissions.
- The growing preference for low-cost alternatives in the automotive sector will make lead acid batteries a popular choice for many consumers.
- Technological advancements in battery life, charging efficiency, and weight reduction will enhance the appeal of lead acid batteries.
- The expansion of the electric vehicle market in India will stimulate the demand for advanced lead acid batteries for EV applications.
- Rising investments in research and development will help improve battery lifespan, performance, and reduce manufacturing costs.
- Growing consumer awareness about eco-friendly solutions will lead to the development of more sustainable battery technologies.
- The market will witness a rise in demand from after-market sectors, including replacement battery sales, due to the increasing number of vehicles on the road.
- Strategic partnerships between domestic and global players will enhance the availability of innovative and high-quality lead acid batteries across India.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Automotive Lead Acid Battery?
What factors are driving the growth of the India Automotive Lead Acid Battery?
What are some challenges faced by the India Automotive Lead Acid Battery?
Who are the major players in the India Automotive Lead Acid Battery?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Automotive Lead Acid Battery Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 India Automotive Lead Acid Battery Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 609.74 million → 2032: USD 1,475.08 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Automotive Lead Acid Battery Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Automotive Lead Acid Battery Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Automotive Lead Acid Battery Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 India Automotive Lead Acid Battery Drivers
- 3.3 India Automotive Lead Acid Battery Restraints & Challenges
- 3.4 India Automotive Lead Acid Battery Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Automotive Lead Acid Battery Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Automotive Lead Acid Battery Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Automotive Lead Acid Battery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Automotive Lead Acid Battery Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. India Automotive Lead Acid Battery Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to India Automotive Lead Acid Battery in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Automotive Lead Acid Battery Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 India Automotive Lead Acid Battery Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 India Automotive Lead Acid Battery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Automotive Lead Acid Battery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in India Automotive Lead Acid Battery
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. India Automotive Lead Acid Battery – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. India Automotive Lead Acid Battery – Priority Domestic Market 1
Chapter 10. India Automotive Lead Acid Battery – Priority Domestic Market 2
Chapter 11. India Automotive Lead Acid Battery – Priority Domestic Market 3
Chapter 12. India Automotive Lead Acid Battery – Priority Domestic Market 4
Chapter 13. India Automotive Lead Acid Battery Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
