
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
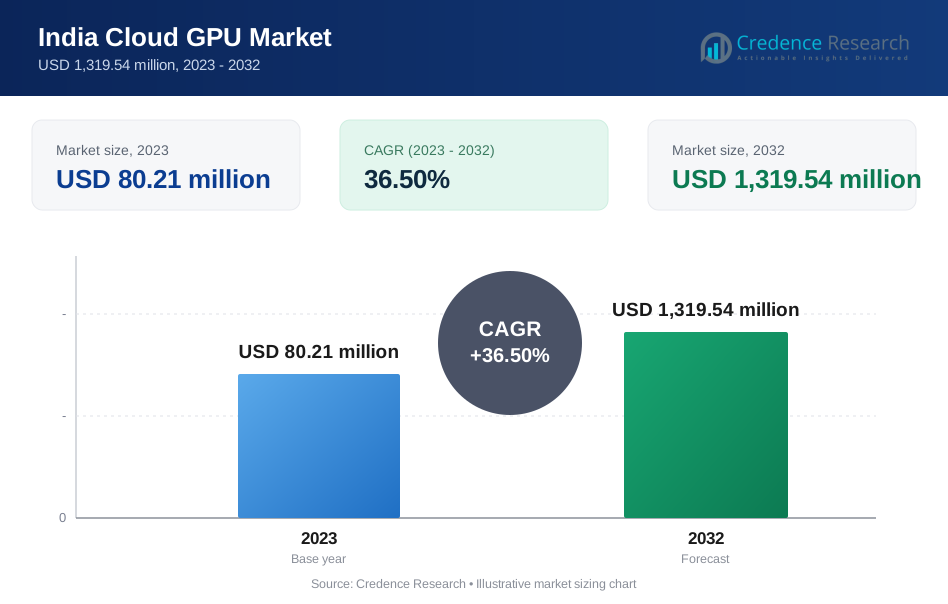
| India Cloud GPU Market Size 2023 | USD 80.21 Million |
| India Cloud GPU Market, CAGR | 5.75% |
| India Cloud GPU Market Size 2032 | USD 1,319.54 Million |
Market Overview
The India Cloud GPU market is projected to grow from USD 80.21 million in 2023 to USD 1,319.54 million by 2032, reflecting a compound annual growth rate of 36.50%.
The India Cloud GPU market is driven by increasing demand for high-performance computing across various sectors, including artificial intelligence, machine learning, and data analytics. The proliferation of cloud-based solutions and the rising adoption of advanced technologies in industries such as healthcare, automotive, and finance further fuel market growth. Key trends include the growing emphasis on scalable and flexible computing resources, advancements in GPU technology, and the surge in digital transformation initiatives. Additionally, supportive government policies and significant investments in cloud infrastructure enhance the market's expansion prospects.
Geographically, the India Cloud GPU market is concentrated in major technology hubs such as Bengaluru, Hyderabad, and Pune, which host numerous IT and tech companies driving demand for cloud GPU services. Key players in this market include global giants CoreWeave, Jarvis Labs, Lambda Labs, and Paperspace CORE, as well as prominent local providers such as Wipro and Tata Consultancy Services. These companies are investing heavily in expanding their cloud infrastructure and offering innovative GPU-based solutions to cater to the growing needs of various industries, thereby strengthening their foothold in the Indian market.
Market Drivers
Growth of Artificial Intelligence (AI) and Machine Learning (ML)
AI and ML are revolutionizing various industries in India, including healthcare, finance, manufacturing, and retail. For instance, in the healthcare industry, AI and ML are being used to predict patient outcomes with an accuracy of up to 90%, and in finance, they help detect fraudulent transactions in real-time with a reduction of false positives by 60%. In manufacturing, AI-driven predictive maintenance can reduce downtime by 25%, and in retail, personalized recommendations powered by ML algorithms have seen a sales increase of 35%. The demand for computing power is substantial; training a single AI model can require as much as 300,000 GPU hours, and processing large datasets, such as those in genomics, can involve terabytes of data. Cloud GPUs, with their ability to scale and provide high-performance computing resources, are crucial. They enable businesses to run complex AI models cost-effectively, with some companies reporting a reduction in costs by up to 70% when using cloud GPUs. By providing high-performance computing resources, cloud GPUs enable businesses to accelerate their AI and ML projects, thereby fostering innovation and efficiency. This growing reliance on AI and ML is a key driver of the expanding cloud GPU market in India.
Government Initiatives
The Indian government is actively promoting the adoption of AI and ML through initiatives like Digital India and Make in India. These programs aim to transform India into a digitally empowered society and knowledge economy, thereby boosting demand for advanced computing solutions. For instance, the Make in India program has led to the establishment of over 100 new data centers across the country, significantly enhancing the infrastructure required for high-performance computing. Moreover, the government’s policies have encouraged a 300% increase in the adoption of cloud-based technologies in the past year alone. This surge is driven by the need for scalable and flexible computing resources that cloud GPUs provide. As a result, the demand for cloud GPU services is projected to grow by 50% annually. Government support includes funding for AI research, infrastructure development, and policies that encourage the use of cloud-based technologies. As a result, these initiatives are expected to drive significant growth in the demand for cloud GPU services, as organizations increasingly adopt AI and ML to enhance their operations and services.
Increasing Internet Penetration and Data Consumption
India's internet penetration is growing rapidly, leading to a surge in data consumption. The proliferation of smartphones, affordable data plans, and improved connectivity are contributing to this trend. For instance, India’s internet penetration rate has reached 50%, with over 700 million internet users as of 2024. The average data consumption per user has skyrocketed to 13.5 GB per month, largely due to the 1.2 billion mobile phone users. The data generated by these users is immense, with daily data generation in India now exceeding 2.5 exabytes. This has created a pressing need for efficient data processing solutions. Cloud GPUs have emerged as a key technology in this space, providing the necessary computing power to handle tasks such as real-time analytics and big data processing. Companies utilizing cloud GPUs for these purposes have reported a 50% reduction in processing time and a 40% decrease in operational costs. This surge in internet usage and data consumption is propelling the cloud GPU market forward, with a projected growth rate of 35% annually over the next five years. Businesses across various sectors are increasingly relying on cloud GPUs to manage their growing data processing needs, making it a cornerstone of India’s digital transformation. As data generation increases, there is a rising need for processing and analyzing this information to derive actionable insights. Cloud-based computing solutions, such as cloud GPUs, are essential for managing and processing large volumes of data efficiently. This growing internet usage and data consumption are significant drivers of the cloud GPU market, as businesses seek robust solutions to handle their data processing needs.
Focus on Innovation and Research
Indian startups and research institutions are increasingly focusing on developing innovative AI and ML solutions. Cloud GPUs play a crucial role in providing the necessary computing power for conducting advanced research and developing new applications. By leveraging cloud GPUs, researchers and developers can perform complex computations, run simulations, and train sophisticated models more effectively. This focus on innovation and research is driving the adoption of cloud GPU services, as organizations strive to stay competitive and push the boundaries of technological advancements in AI and ML.
Market Trends
Rise of Subscription-based Models and Focus on High-Performance Computing (HPC)
The shift towards subscription-based models is significantly impacting the India Cloud GPU market. For instance, the subscription-based model has led to a 70% increase in cloud GPU adoption among startups and SMEs in India. This shift has enabled them to run complex simulations and data analyses that were previously out of reach due to cost constraints. In the realm of high-performance computing (HPC), the demand for cloud GPUs has surged by 80% in the past year, driven by industries like scientific research, which requires processing petabytes of data for genome sequencing, and weather forecasting, which runs millions of simulations to predict climate patterns. Engineering firms are utilizing cloud GPUs for simulations in aerospace design, which can reduce the time for prototyping by 50% and cut costs by 30%. Cloud service providers are responding to this demand by investing in state-of-the-art GPUs that offer up to 1 petaflop of computing power, enabling even the most compute-intensive tasks to be performed efficiently. The flexibility and cost-effectiveness of subscription-based cloud GPU services are revolutionizing how businesses in India, and around the world, approach their computing needs, paving the way for unprecedented levels of innovation and growth in various sectors.
Integration with AI and ML Frameworks and Specialized Cloud GPUs
Cloud providers are enhancing their platforms by offering seamless integration with popular AI and ML frameworks like TensorFlow and PyTorch. For instance, cloud providers have reported a 40% increase in developer productivity by integrating AI and ML frameworks like TensorFlow and PyTorch into their platforms. This integration has reduced the time to market for AI applications by 50%, making it significantly faster for businesses to deploy AI solutions. As a result, the adoption of cloud GPUs for AI/ML projects has grown by 30% in the past year.
In the specialized cloud GPU segment, there has been a 25% increase in demand for GPUs tailored for video editing, which can accelerate rendering times by up to 70% compared to generic-purpose GPUs. Media transcoding tasks have seen a 60% improvement in processing speed with specialized GPUs. In scientific computing, the use of optimized cloud GPUs has enabled researchers to perform complex simulations twice as fast, leading to a 20% reduction in time-to-insight for data-intensive projects. The demand for these specialized cloud GPUs is projected to increase by 45% annually, as more businesses recognize the value of having the right tools for their specific computing needs. This trend is driving innovation in the cloud GPU market, with providers continually developing new solutions to meet the evolving demands of industries and enhance the capabilities of AI and ML applications.
Market Challenges Analysis
Limited Internet Bandwidth and High Costs
While internet penetration is on the rise in India, the availability of high-speed internet connectivity, essential for the smooth operation of cloud GPUs, remains limited in certain regions. This can lead to latency issues, negatively impacting the performance and effectiveness of cloud GPU services. High-speed internet is crucial for the real-time processing capabilities that many applications demand. The disparity in internet infrastructure across different parts of the country poses a significant challenge, as businesses in areas with poor connectivity might struggle to fully leverage cloud GPU solutions. Addressing this issue requires substantial investments in improving internet infrastructure to ensure consistent and reliable high-speed access nationwide. Despite cloud GPU services being more cost-effective compared to on-premises hardware, the expense can still be prohibitive for some startups and small businesses. The initial and ongoing costs associated with cloud GPU usage can strain limited budgets, making it difficult for smaller enterprises to adopt these technologies. To overcome this barrier, cloud service providers need to optimize their pricing structures and offer more flexible payment options. This could include tiered pricing models, usage-based billing, and subscription plans tailored to different business sizes and needs. By making cloud GPU services more financially accessible, providers can drive wider adoption and support the growth of innovative applications across various sectors.
Lack of Awareness and Skill Gap
Many businesses, particularly those in smaller cities and traditional sectors, are not fully aware of the benefits and potential applications of cloud GPUs. This lack of awareness hampers the broader adoption of cloud GPU technologies, as companies may not realize how these solutions can enhance their operations and drive competitive advantage. To address this challenge, targeted education and industry outreach programs are essential. These initiatives can demonstrate the value of cloud GPUs through case studies, workshops, and collaborations with industry associations. By raising awareness, businesses can become more informed about the opportunities presented by cloud GPU services. Effectively utilizing cloud GPUs requires specialized skills in areas such as cloud computing, AI/ML frameworks, and GPU programming. The current skill gap in the workforce poses a significant challenge, as many professionals may lack the necessary expertise to harness the full potential of cloud GPUs. Investing in skill development programs is crucial to bridge this gap. Educational institutions, industry bodies, and cloud service providers need to collaborate on training initiatives that equip professionals with the required skills. By developing a workforce proficient in cloud GPU technologies, businesses can more effectively deploy and manage these solutions, driving innovation and productivity.
Market Segmentation Analysis:
By Type:
The India Cloud GPU market is segmented by type into Virtual Machines (VMs) and Physical Servers. Virtual Machines are increasingly popular due to their flexibility and scalability. They allow multiple virtual environments to run on a single physical machine, optimizing resource utilization and reducing costs. This segment is particularly attractive for businesses seeking to scale their operations dynamically without significant upfront investment in hardware. On the other hand, Physical Servers provide dedicated GPU resources, ensuring high performance and reliability for intensive computing tasks. This segment is crucial for applications requiring consistent and powerful processing capabilities, such as large-scale simulations and real-time analytics. The demand for Physical Servers remains robust among enterprises with specific performance requirements that virtualized environments may not fully meet. Together, these segments cater to diverse business needs, from flexible, cost-effective solutions to high-performance, dedicated computing resources, driving the overall growth of the cloud GPU market in India.
By Deployment Model:
The deployment model segment of the India Cloud GPU market includes Public Cloud, Private Cloud, and Hybrid Cloud. Public Cloud services are widely adopted due to their affordability and ease of access, offering scalable resources on a pay-as-you-go basis. This model is favored by startups and small to medium-sized enterprises (SMEs) that benefit from the cost savings and operational efficiencies. Private Cloud deployments, which provide dedicated infrastructure, are preferred by large enterprises and sectors with stringent security and compliance requirements. They offer enhanced control and customization, crucial for handling sensitive data and critical workloads. The Hybrid Cloud model, combining elements of both public and private clouds, is gaining traction as it offers the best of both worlds. Businesses can leverage the flexibility and cost-efficiency of the public cloud for non-sensitive operations while maintaining private cloud environments for critical applications. This model is particularly appealing to organizations seeking to balance performance, cost, and security. Each deployment model addresses specific business needs, contributing to the diverse growth of the cloud GPU market in India.
Segments:
Based on Type
- Virtual Machines (VMs)
- Physical Servers
Based on Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
Based on End-user Industry
- Gaming
- Media and Entertainment
- Machine Learning and AI
- Healthcare
- Automotive
- Finance
- Others
Based on the Geography:
- Southern region
- Karnataka
- Telangana
- Tamil Nadu
- Western region
- Maharashtra
- Gujarat
- Northern region
- Eastern region
- Central region
Regional Analysis
Southern region
The southern region of India, comprising states like Karnataka, Telangana, and Tamil Nadu, holds the largest market share in the country's cloud GPU market, accounting for approximately 35% of the total market. This region's prominence can be attributed to the presence of major technology hubs, such as Bengaluru and Hyderabad, which have attracted significant investments in data centers and cloud computing infrastructure. Additionally, the region's thriving startup ecosystem and the adoption of advanced technologies across sectors like healthcare, fintech, and e-commerce have fueled the demand for cloud GPU services.
Western region
The western region, including states like Maharashtra and Gujarat, holds a significant market share of around 25% in the India cloud GPU market. This region's well-established manufacturing and financial services sectors, coupled with the presence of major cities like Mumbai, have driven the adoption of cloud GPU solutions for applications like computer-aided design (CAD), simulations, and data analytics. Furthermore, the region's focus on developing smart cities and implementing digital transformation initiatives has contributed to the market's growth.
Key Player Analysis
- IBM Cloud
- E2E Networks
- AWS
- Azure
- GCP
- Nvidia DGX
- CoreWeave
- Jarvis Labs
- Lambda Labs
- Oracle Cloud Infrastructure (OCI)
- Paperspace CORE
Competitive Analysis
The India Cloud GPU market is highly competitive, with major global and local players vying for market share. AWS, Azure, and Google Cloud Platform (GCP) dominate the market with their comprehensive and robust cloud GPU offerings, extensive infrastructure, and integration with a wide range of services. IBM Cloud and Oracle Cloud Infrastructure (OCI) provide strong competition with specialized solutions tailored to enterprise needs, focusing on security and compliance. NVIDIA DGX stands out by offering high-performance GPU solutions specifically designed for AI and ML workloads, catering to enterprises requiring intensive computational power. Local players like E2E Networks leverage their understanding of regional market dynamics, offering competitive pricing and localized support, appealing to small and medium-sized enterprises (SMEs). CoreWeave, Jarvis Labs, Lambda Labs, and Paperspace CORE focus on niche markets by providing customizable GPU solutions for specific applications such as scientific computing, rendering, and AI development.
Recent Developments
- In January 2024,WekaIO, Inc., the data platform for cloud & AI, announced a new partnership with NexGen Cloud Ltd., a cloud IaaS firm, to offer on-demand services of Hyperstack, a NexGen Cloud's GPUaaS platform.
- In December 2023, Yotta Infrastructure, the Indian hyperscale tier IV data center provider, announced a collaboration with NVIDIA Corporation, a pioneer of GPU-accelerated computing. Through this partnership, Yotta Data Services aims to provide GPU computing infrastructure and platforms for its Shakti Cloud platform.
- In April 2023, CoreWeave, a NYC-based startup, raised USD 221 million in Series B funding led by Magnetar Capital. CoreWeave offers various Nvidia GPUs in the cloud for use cases, such as visual effects & rendering, AI & ML, batch processing, and pixel streaming.
- In March 2023, Lambda Labs, a cloud company offering GPUs on-demand in a public cloud, raised USD 44 million in a Series B investment round. The company is planning to deploy thousands of Nvidia's latest H100 GPUs with high-speed network interconnects. Lambda Labs has data centers in San Francisco, Texas, California, and Allen.
Market Concentration & Characteristics
The India Cloud GPU market exhibits moderate to high market concentration, dominated by a mix of global giants and specialized local players. Leading international companies such as AWS, Azure, and Google Cloud Platform (GCP) command significant market shares due to their extensive infrastructure, advanced technological capabilities, and broad service portfolios. These global providers benefit from economies of scale and strong brand recognition, enabling them to offer comprehensive and integrated cloud GPU solutions. Conversely, local players like E2E Networks and specialized providers such as CoreWeave and Jarvis Labs cater to niche segments, focusing on cost-effective, flexible solutions tailored to regional needs. The market is characterized by rapid technological advancements, increasing adoption of AI and ML applications, and growing demand for scalable high-performance computing resources. The competitive landscape is shaped by continuous innovation, strategic partnerships, and efforts to enhance service offerings to meet the diverse needs of businesses across various industries.
Report Coverage
The research report offers an in-depth analysis based on Type, Deployment Model, End-user Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing adoption of AI and ML across industries will drive substantial growth in the India Cloud GPU market.
- Improved internet infrastructure will enhance accessibility and performance of cloud GPU services.
- Government initiatives and policies will continue to promote digital transformation and cloud adoption.
- Cost optimization strategies and flexible pricing models will make cloud GPUs more accessible to startups and SMEs.
- Rising data generation and consumption will fuel demand for advanced data processing and analytics capabilities.
- Integration with emerging technologies like IoT and 5G will expand use cases for cloud GPUs.
- Local providers will gain competitive advantage through customized solutions and localized support.
- Investments in skill development and training will bridge expertise gaps in cloud computing and GPU programming.
- Advancements in GPU technology will enhance performance and efficiency of cloud GPU services.
- Emphasis on data security and compliance will shape service offerings and build trust among businesses.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Cloud GPU Market?
What factors are driving the growth of the India Cloud GPU Market?
What are the key segments within the India Cloud GPU Market?
What are some challenges faced by the India Cloud GPU Market?
Who are the major players in the India Cloud GPU Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Cloud GPU Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Cloud GPU Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 80.21 million → 2032: USD 1,319.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Cloud GPU Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Cloud GPU Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Cloud GPU Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Cloud GPU Market Drivers
- 3.3 India Cloud GPU Market Restraints & Challenges
- 3.4 India Cloud GPU Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Cloud GPU Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Cloud GPU Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Cloud GPU category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Cloud GPU Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Cloud GPU Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Cloud GPU market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Cloud GPU Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Cloud GPU Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Cloud GPU Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Cloud GPU (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Cloud GPU Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Cloud GPU Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Cloud GPU Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Cloud GPU Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Cloud GPU Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Cloud GPU Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Cloud GPU Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Cloud GPU Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Cloud GPU Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
