
Market Overview:
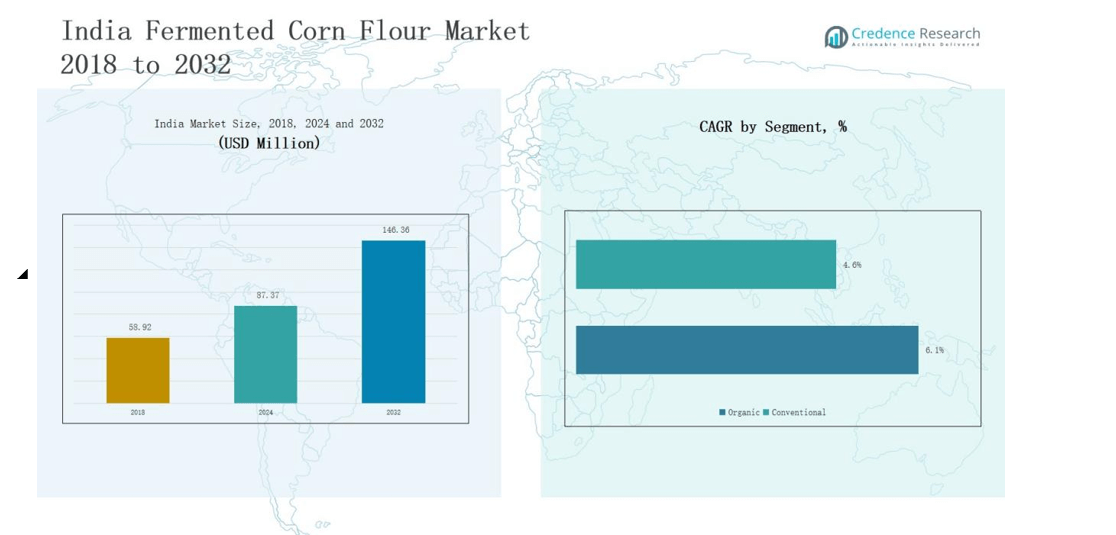
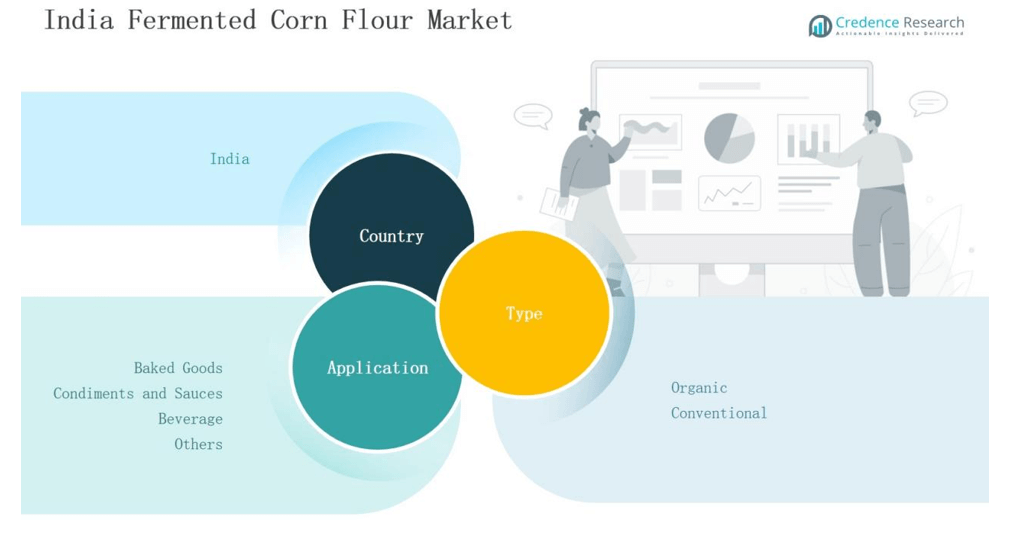
India Fermented Corn Flour Market size was valued at USD 58.92 million in 2018 to USD 87.37 million in 2024 and is anticipated to reach USD 146.36 million by 2032, at a CAGR of 6.20% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Fermented Corn Flour Market Size 2024 | USD 87.37 million |
| India Fermented Corn Flour Market, CAGR | 6.20% |
| India Fermented Corn Flour Market Size 2032 | USD 146.36 million |
The India Fermented Corn Flour Market is shaped by key players such as Prathista Industries, Mittal Cornezza, Shreeji Ingredients (Shreejicorn), Regaal Resources Ltd, Nexus Maize, CMS Industries, and Vedant Agro Foods. These companies compete by expanding product portfolios, focusing on organic variants, and strengthening distribution networks across urban and semi-urban markets. Regional players support market penetration by offering affordable conventional products to price-sensitive consumers. North India emerged as the leading region, holding 34% share in 2024, driven by strong demand from bakery, condiments, and processed food industries.
Market Insights
- The India Fermented Corn Flour Market grew from USD 58.92 million in 2018 to USD 87.37 million in 2024 and is projected to reach USD 146.36 million by 2032, at a CAGR of 6.20%.
- Organic fermented corn flour led with 58% share in 2024, supported by rising health awareness and demand for chemical-free food products, while conventional held 42% driven by affordability.
- Baked goods dominated with 46% share in 2024, followed by condiments and sauces at 24%, beverages at 18%, and others at 12% through snacks and specialty foods.
- North India commanded 34% share in 2024, driven by strong demand from bakery, condiments, and processed foods, while South India followed with 28% due to rising beverage and bakery adoption.
- West India accounted for 22% share with growth from bakery chains and foodservice outlets, whereas East India remained the smallest market at 16%, supported by traditional food and beverage demand.
Market Segment Insights
By Type
Organic fermented corn flour led the market with a 58% share in 2024, driven by rising health awareness and demand for chemical-free food products. Consumers in urban centers are increasingly choosing organic options, supported by government initiatives promoting sustainable farming. Conventional fermented corn flour held the remaining 42% share, favored by small and medium-scale food manufacturers due to its affordability and steady supply, though its growth is slower compared to organic.
- For instance, Cargill launched its PURIS™ line of organic, plant-based ingredients, including corn-derived proteins, to meet rising clean-label demand in North America
By Application
Baked goods dominated with a 46% share in 2024, supported by rising bakery consumption and demand for better texture and nutrition. Condiments and sauces followed with 24%, driven by processed food growth and packaged product popularity. Beverages captured 18%, benefiting from innovations in health drinks and traditional fermented products. The “Others” category accounted for 12%, covering snacks and specialty foods, where plant-based innovation creates new opportunities.
- For instance, Heinz also relaunched its “Zero Added Sugar” ketchup in the U.K., aligning with consumer demand for better-for-you condiments.
Market Overview
Rising Health and Wellness Awareness
India’s growing health-conscious population is driving demand for organic and functional food ingredients, including fermented corn flour. Consumers are increasingly seeking natural, chemical-free products with digestive and nutritional benefits. The flour’s probiotic qualities and ability to enhance gut health make it attractive in daily diets. Expanding urban middle-class households with higher disposable incomes are willing to pay premium prices for healthier options. This rising preference for wellness-focused foods positions fermented corn flour as a key substitute in bakery, beverage, and condiment industries.
- For instance, ITC’s “Aashirvaad Nature’s Superfoods” line introduced high-fiber flours enriched with natural grains, catering to urban buyers willing to adopt healthier staples.
Expanding Bakery and Processed Food Sector
The Indian bakery and processed food sector is rapidly expanding, supported by urbanization and lifestyle shifts. Fermented corn flour is widely used in bread, biscuits, cakes, sauces, and packaged foods for its ability to improve flavor, texture, and shelf life. Quick-service restaurants and retail bakeries are fueling adoption by incorporating it in product innovation. The increasing popularity of western-style bakery items, alongside traditional baked goods, further strengthens demand. This robust growth in processed foods directly enhances the consumption of fermented corn flour.
Supportive Government Policies and Organic Farming Initiatives
Government policies promoting organic farming and sustainable agriculture practices are boosting the availability of organic corn. Subsidies, certification support, and farmer training programs are improving supply consistency for manufacturers. These initiatives align with India’s broader food safety and sustainability goals, creating favorable conditions for organic fermented corn flour adoption. Export-oriented policies are also opening new opportunities for Indian producers in international markets. This institutional support provides long-term stability and encourages investments across the fermented corn flour value chain.
- For instance, Sikkim, recognized as India’s first fully organic state in 2016, now exports certified organic produce to markets in Europe and the U.S., showcasing the viability of policy-driven organic transitions.
Key Trends & Opportunities
Growing Demand for Plant-Based and Functional Foods
The plant-based food movement in India is gaining momentum, creating opportunities for fermented corn flour as a core ingredient. Its ability to provide plant proteins, probiotics, and gluten-free alternatives positions it well in health-focused categories. Start-ups and established brands are using it to create snacks, beverages, and specialty foods. Consumers looking for innovative yet nutritious products are driving experiments with plant-based formulations, making fermented corn flour adoption a trend with strong long-term potential.
- For instance, Plantaway introduced India's first 100% plant protein Chick'n Fillet made entirely from pea protein, offering 19g protein per pack with realistic taste and texture, showcasing how plant proteins are used for meat alternatives with nutritional focus.
Expansion of Online Food and Grocery Retail
commerce platforms and online grocery channels are playing a key role in market growth. Digital platforms enable wider product availability, especially for niche items like fermented corn flour, which may not be easily found offline. Growing consumer preference for doorstep delivery, subscription models, and brand-owned online stores is expanding reach. This trend benefits both large producers and regional players, providing a direct route to health-conscious urban customers. The rising penetration of digital retail significantly boosts visibility and accessibility of fermented corn flour.
- For instance, Instacart helps over 5,500 brand partners reach new customers, with programs that boost sales by more than 15% on average, supporting growth for both large and small specialty food producers through online listings and targeted advertising.
Key Challenges
Price Sensitivity and High Cost of Organic Products
Despite growing demand, the high price of organic fermented corn flour remains a barrier in India’s price-sensitive market. Many consumers continue to prioritize affordability over health benefits, limiting penetration in lower-income groups. Small food manufacturers also hesitate to adopt organic variants due to cost constraints. Balancing premium pricing with broader affordability is a critical challenge for market players. Unless addressed, high costs could restrict organic flour adoption to urban elites and slow down mass-market expansion.
Limited Consumer Awareness Beyond Major Cities
Awareness of fermented corn flour and its nutritional benefits is still largely concentrated in metropolitan and Tier-1 cities. Rural and semi-urban consumers often lack exposure to such products, restricting market reach. Limited marketing efforts and absence of strong retail penetration in these regions further slow adoption. Without targeted campaigns and distribution expansion, growth will remain uneven across geographies. Bridging this knowledge and availability gap is essential to capture the wider Indian consumer base.
Supply Chain and Quality Consistency Issues
Ensuring consistent supply and quality of fermented corn flour poses a challenge for manufacturers. Seasonal variations in corn availability and dependence on small-scale farmers often create fluctuations. Maintaining standard fermentation processes and quality across batches can also be difficult, affecting trust among food manufacturers. Logistics and storage infrastructure gaps, particularly in smaller towns, further add to the problem. Strengthening supply chains and investing in quality assurance will be vital to build confidence and expand long-term market adoption.
Regional Analysis
North India
North India accounted for 34% share in 2024, making it the leading region in the India Fermented Corn Flour Market. Strong demand from bakery and packaged food industries in states such as Punjab, Haryana, and Delhi supported this dominance. Rising health awareness and preference for organic food choices further strengthened market growth. Food processing hubs and easy access to raw corn supply also encouraged manufacturers to expand operations. Demand for condiments, sauces, and traditional snacks remained high, sustaining steady sales. With urbanization and organized retail growth, North India continues to lead consumption and production.
South India
South India captured 28% share in 2024, driven by high consumption of fermented beverages and baked goods. Cities like Bengaluru, Hyderabad, and Chennai showed strong adoption due to a larger base of health-conscious consumers. The region benefits from the rising presence of specialty food stores and modern retail formats. Strong agricultural production and investment in food processing industries further support market expansion. Demand for both conventional and organic variants is increasing, with beverages and condiments showing strong momentum. South India remains an attractive market for manufacturers targeting innovation and premium product lines.
West India
West India held 22% share in 2024, supported by strong industrial presence in Maharashtra and Gujarat. Growing bakery chains and foodservice outlets increased the use of fermented corn flour in baked goods and sauces. Rising consumer awareness of functional foods in urban areas like Mumbai and Pune created opportunities for organic products. Food manufacturing clusters in Gujarat helped strengthen supply and distribution. The region continues to balance demand between mass-market conventional products and premium organic categories. With rising disposable incomes, West India is witnessing a gradual shift toward healthier alternatives.
East India
East India accounted for 16% share in 2024, making it the smallest regional market. Limited awareness and weaker retail penetration constrained faster adoption. However, states like West Bengal and Odisha are showing growing demand through traditional food and beverage segments. The region benefits from an emerging urban middle class, though price sensitivity remains high. Small-scale food manufacturers are key contributors, using conventional flour in local products. Expansion of online food retail is helping raise product visibility, creating long-term growth potential despite current constraints.
Market Segmentations:
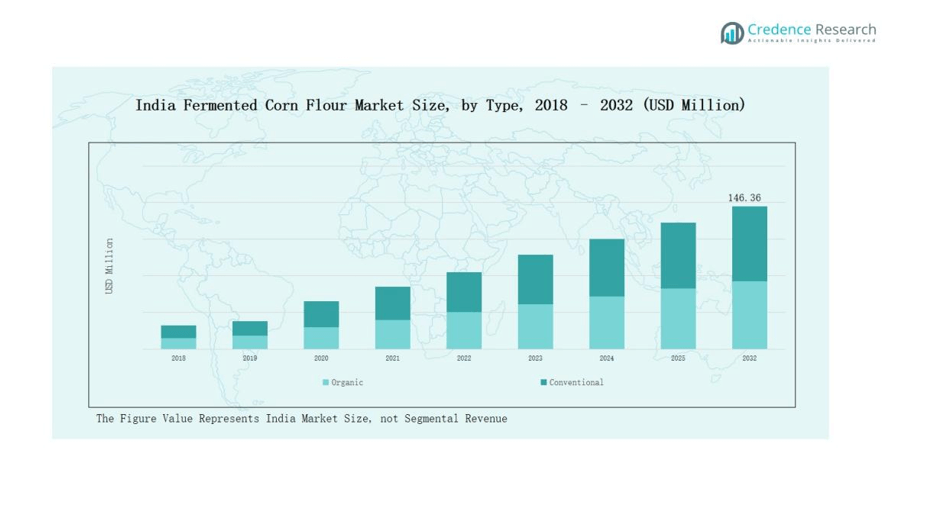
By Type
- Organic
- Conventional
By Application
- Baked Goods
- Condiments and Sauces
- Beverage
- Others
By Region
- North India
- South India
- West India
- East India
Competitive Landscape
The India Fermented Corn Flour Market is moderately fragmented, with a mix of established companies and regional players competing for market share. Key participants such as Prathista Industries, Mittal Cornezza, Shreeji Ingredients, Regaal Resources Ltd, Nexus Maize, CMS Industries, and Vedant Agro Foods lead the market with diversified product portfolios and strong distribution networks. These companies emphasize innovation, focusing on organic variants and customized formulations to meet rising demand from bakery, beverage, and condiment manufacturers. Regional firms cater to cost-sensitive customers by offering conventional flour at competitive prices, ensuring broad accessibility across rural and semi-urban markets. Strategic partnerships with food processing units, investment in quality certifications, and expansion into e-commerce channels are strengthening market presence. The competitive environment is shaped by continuous product development, supply chain improvements, and efforts to balance affordability with premium quality, positioning leading players to capture both mass-market and health-conscious consumer segments.
Key Players
- Prathista Industries
- Mittal Cornezza
- Shreeji Ingredients (Shreejicorn)
- Regaal Resources Ltd
- Nexus Maize
- CMS Industries
- Vedant Agro Foods
Recent Developments
- In May 2023, Prathista Industries launched a new line of organic fermented corn flour, aimed at health-conscious consumers in India.
- In March 2025, Cargill and Saatvik Agro Processors jointly inaugurated a corn milling plant in Gwalior, Madhya Pradesh, India.
- In August 2025, Regaal Resources announced a ₹430 crore expansion at its Bihar plant to double maize-based specialty product output, including corn flour and gluten, while also adding herbal gulal production.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for organic fermented corn flour will rise with increasing health awareness.
- Expansion of bakery and processed food industries will drive consistent market growth.
- Beverages and condiments will emerge as strong application areas in urban markets.
- Online retail and e-commerce channels will enhance accessibility and visibility.
- Regional players will strengthen market presence with cost-effective conventional products.
- Investments in supply chain and quality certifications will improve product reliability.
- Export opportunities will expand with growing interest in organic and plant-based foods.
- Awareness campaigns will support adoption in semi-urban and rural regions.
- Strategic collaborations with food manufacturers will encourage innovation in product use.
- Rising disposable incomes will increase demand for premium and value-added variants.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health and Wellness Awareness
India’s increasingly health-conscious population is driving demand for organic and functional food ingredients like fermented corn flour, valued for its probiotic and digestive benefits. Urban consumers are willing to pay a premium for chemical-free, nutritious products, boosting market growth.
Expansion of Bakery and Processed Food Sector
Rapid growth in India’s bakery and processed food industries is fueling the use of fermented corn flour in breads, biscuits, sauces, and packaged foods, as it enhances flavor, texture, and shelf life. Quick-service restaurants and retail bakeries are key adopters, further increasing demand.
Supportive Government Policies and Organic Farming Initiatives
Government initiatives promoting organic farming, including subsidies and certification support, are increasing the availability of organic corn and encouraging manufacturers to invest in organic fermented corn flour production, aligning with food safety and sustainability goals.
Growth of Online Food and Grocery Retail
The expansion of e-commerce and online grocery platforms is making fermented corn flour more accessible, especially in urban areas where health-focused consumers seek niche and specialty products. Digital retail channels are broadening market reach and visibility.
Plant-Based and Functional Food Trends
The rising popularity of plant-based diets and functional foods in India is creating new opportunities for fermented corn flour, which is used in innovative snacks, beverages, and specialty foods as a gluten-free, protein-rich, and probiotic ingredient.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the India Fermented Corn Flour Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Fermented Corn Flour Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the India Fermented Corn Flour Market?
Who are the leading companies in the India Fermented Corn Flour Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Organic
- 1.2.2 Conventional
- 1.3 By Application
- 1.3.1 Baked Goods
- 1.3.2 Condiments and Sauces
- 1.3.3 Beverage
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 87.37 million → 2032: USD 146.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Fermented Corn Flour Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Fermented Corn Flour Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Fermented Corn Flour Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Fermented Corn Flour Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Fermented Corn Flour Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Fermented Corn Flour Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Fermented Corn Flour Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Fermented Corn Flour Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 87.37 million → 2032: USD 146.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Fermented Corn Flour Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Organic
- 12.3.7.2 Conventional
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Baked Goods
- 12.4.7.2 Condiments and Sauces
- 12.4.7.3 Beverage
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 India Fermented Corn Flour End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Fermented Corn Flour Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Fermented Corn Flour Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Fermented Corn Flour Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Prathista Industries
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mittal Cornezza
- 18.4 Shreeji Ingredients (Shreejicorn)
- 18.5 Regaal Resources Ltd
- 18.6 Nexus Maize
- 18.7 CMS Industries
- 18.8 Vedant Agro Foods
- 18.9 Cargill
- 18.10 Saatvik Agro Processors
- 18.11 ITC Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

