
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
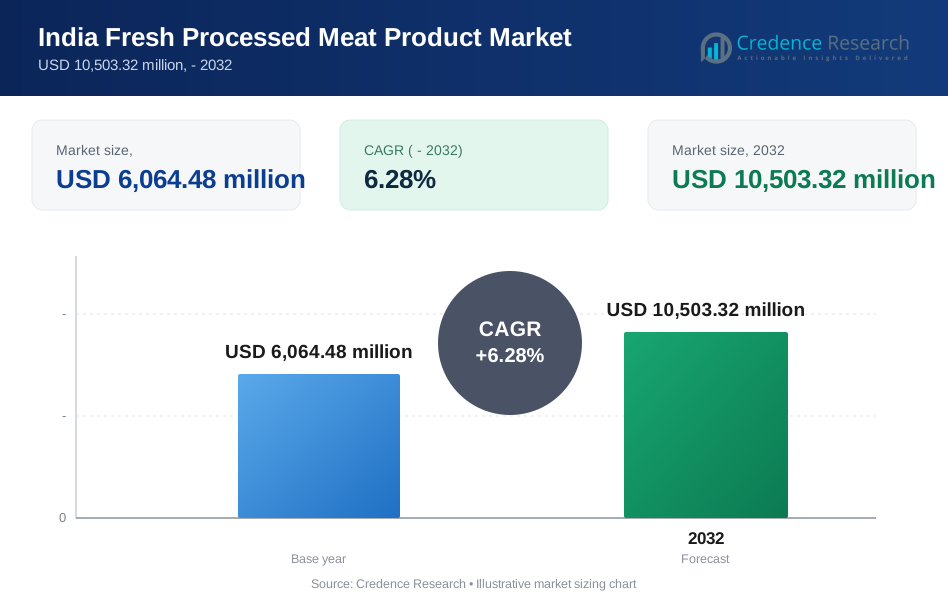
| India Fresh Processed Meat Product Market Size 2023 | USD 6,064.48 Million |
| India Fresh Processed Meat Product Market, CAGR | 6.28% |
| India Fresh Processed Meat Product Market Size 2032 | USD 10,503.32 Million |
Market Overview
The India Fresh Processed Meat Product Market is projected to grow from USD 6,064.48 million in 2023 to an estimated USD 10,503.32 million by 2032, with a compound annual growth rate (CAGR) of 6.28% from 2024 to 2032. This growth reflects increasing demand for processed meat products, driven by changing consumer preferences and urbanization.
Key drivers of this market include the rising consumption of convenience food, increasing disposable incomes, and the growing inclination toward protein-rich diets. Moreover, consumers are seeking more diverse and high-quality meat products, contributing to the expansion of the fresh processed meat sector. Additionally, trends such as innovation in packaging and advancements in processing technologies are expected to further drive market growth.
Geographically, the market is primarily driven by urban areas, with significant growth in Tier 1 and Tier 2 cities. Key players in the market include Marico Ltd., Venkateshwara Hatcheries Pvt. Ltd., and Godrej Agrovet Ltd., which continue to innovate and expand their product offerings to cater to the evolving consumer demands.
Market Insights
- The India Fresh Processed Meat Product Market is projected to grow from USD 6,064.48 million in 2023 to USD 10,503.32 million by 2032, at a CAGR of 6.28%.
- Increasing consumer preference for ready-to-eat and ready-to-cook meat products is driving market growth, especially among urban consumers.
- Higher disposable incomes are boosting demand for premium, high-quality processed meat products.
- Inadequate cold chain infrastructure and distribution inefficiencies in rural areas limit the market's full potential.
- Stricter food safety regulations and compliance requirements can increase operational costs and affect market growth.
- North India dominates the market, accounting for 35% of the total share, driven by a high demand for poultry and mutton.
- South India, with a market share of 25%, is primarily influenced by seafood and poultry consumption, especially in coastal regions.
Market Drivers
Rising Demand for Convenient and Ready-to-Eat Food Products
The demand for convenient and ready-to-eat food products has significantly surged in India due to lifestyle changes and evolving consumer preferences. For instance, India has seen a spike of 45% more consumers using convenience food in the past 12 months. With increasing urbanization, more consumers are opting for processed meat products as they offer ease of preparation, saving time and effort. As busy schedules leave little room for elaborate meal preparation, fresh processed meat products, such as ready-to-cook and ready-to-eat options, are becoming highly popular. The availability of a wide range of convenient, high-quality processed meats such as sausages, burgers, and cold cuts is also contributing to market growth. These products are not only convenient but also provide a consistent taste and quality, which further drives consumer preference. In response to this demand, many companies have been introducing new product lines and packaging innovations to appeal to the on-the-go consumer, making convenience a crucial driver for the market.
Growing Protein Consumption and Changing Dietary Habits
With the rising awareness regarding health and fitness, there has been a marked shift in dietary habits in India. For instance, nearly 70 percent of Indians consumed meat at least occasionally in 2017. Consumers are increasingly prioritizing high-protein diets, and meat, particularly fresh processed varieties, is gaining popularity as a valuable source of protein. As the population becomes more health-conscious, there is a growing focus on maintaining balanced nutrition, and meat products are considered an essential component of this diet. The increasing awareness of the benefits of consuming meat-based protein, especially among fitness enthusiasts, has driven the demand for fresh processed meat products such as chicken sausages, nuggets, and other high-protein options. Additionally, the younger generation, which is more inclined toward global eating habits, is increasingly adopting meat consumption as part of their everyday diet, thus contributing to the growth of the processed meat sector.
Rising Disposable Incomes and Changing Consumer Preferences
The economic growth in India, coupled with a rise in disposable incomes, is playing a vital role in expanding the India Fresh Processed Meat Product Market. For instance, per capita sales of packaged and processed foods in India nearly doubled from 2012 to 2018. As the middle class grows and incomes rise, consumers are increasingly willing to spend on higher-quality meat products that were once considered a luxury. Additionally, there is a noticeable shift in consumer preferences, with more people seeking premium products. As consumers have become more exposed to international food trends, the demand for fresh processed meat products—including international varieties like salami, ham, and other deli meats—has seen an uptick. This trend is especially prevalent in urban areas where exposure to global food cultures is higher. The growing economic stability has also made processed meat more accessible, allowing consumers to explore diverse product ranges. These factors make changing consumer preferences a crucial driver for the market.
Advancements in Meat Processing Technologies and Improved Shelf Life
Technological advancements in meat processing techniques have played a significant role in the expansion of the India Fresh Processed Meat Product Market. Innovations such as vacuum sealing, advanced freezing methods, and new preservation techniques have improved both the shelf life and quality of fresh processed meat products. These technological improvements allow for better preservation of flavor, texture, and nutritional content while extending product shelf life without chemical preservatives. As a result, consumers have greater access to high-quality, long-lasting processed meat products. Furthermore, these advancements help manufacturers reduce waste and improve production efficiency—making fresh processed meat products more affordable for consumers. The ability to retain freshness while enhancing product quality has contributed significantly to the market's expansion, ensuring a steady supply of fresh processed meat products in retail outlets across the country.
Market Trends
Growing Popularity of Plant-Based Meat Alternatives
The increasing demand for plant-based meat alternatives is a significant trend in the Indian market. For instance, brands like GoodDot have expanded their range to include vegan chicken tikka, and Imagine Meats offers mock meat burgers designed to closely mimic traditional meats. Newer entrants like Blue Tribe are also gaining traction by appealing to both vegetarians and flexitarians. This trend is not just about taste; many consumers are opting for plant-based options as healthier substitutes. The rise in consumption of textured vegetable protein in urban centers reflects this shift towards sustainable eating. The appeal of plant-based meats lies in their perceived health benefits and lower environmental impact, driving innovation and expansion in this segment as consumers increasingly seek ethical and healthy food choices.
Focus on Clean Label and Natural Ingredients
The demand for clean label products is reshaping the India Fresh Processed Meat Product Market. Consumers are increasingly conscious of the ingredients in their food, particularly processed items. For instance, many brands are reformulating their products to eliminate artificial preservatives and additives, responding to this demand for natural ingredients. Companies like Vezlay Foods have successfully marketed their offerings as free from harmful chemicals, appealing to health-conscious consumers. This trend aligns with a growing interest in transparency and healthier eating habits, especially among millennials and Gen Z. Brands that offer clear and simple labels, highlighting natural and preservative-free ingredients, are gaining a competitive edge as consumers prioritize health and sustainability in their food choices.
Innovative Packaging and Convenience
The need for convenient and user-friendly packaging for processed meat products is another significant trend. As urbanization continues to evolve lifestyles, consumers require products that are easy to cook and come in convenient packaging. For instance, brands are innovating with microwaveable packs and resealable containers to preserve freshness and ease preparation. Single-serving and family-sized options cater to different consumer needs, enhancing convenience. This demand for quick and easy-to-prepare meals is driven by busy professionals and households looking for efficient solutions. Additionally, eco-friendly packaging is becoming more common, especially in urban areas where sustainability is a growing concern. These innovations meet the demand for convenience while also aligning with environmental consciousness.
Rise in E-Commerce and Online Food Delivery Services
The digital transformation is playing a crucial role in the India Fresh Processed Meat Product Market. The rise of e-commerce platforms and online food delivery services is enabling consumers to access fresh processed meat products with greater ease. For instance, online grocery services like BigBasket and Licious have made it easier for consumers to purchase a variety of products from their homes. This accessibility is key as it aligns with the increasing preference for online shopping among Indian consumers. Online platforms offer the convenience of browsing a wide variety of options, comparing prices, and having products delivered to their doorstep, enhancing the overall consumer experience. As digitalization continues to expand, the online availability of processed meat is expected to further drive growth in the market.
Market Challenges
Supply Chain and Cold Chain Infrastructure Limitations
One of the primary challenges facing the India Fresh Processed Meat Product Market is the inadequacy of the supply chain and cold chain infrastructure. Maintaining the freshness and quality of meat products throughout the distribution process requires a robust cold chain system, which is often underdeveloped in many parts of India. While larger cities may have the necessary infrastructure, rural and semi-urban regions still face logistical challenges when it comes to transporting meat products without compromising quality. The lack of advanced refrigeration, temperature-controlled storage, and efficient distribution channels can lead to spoilage, reduced shelf life, and loss of product quality, ultimately affecting consumer trust. This challenge requires significant investment in cold chain logistics to ensure the products remain fresh from production to retail outlets and consumer homes. Additionally, inconsistent power supply in some regions further exacerbates this problem. Overcoming these supply chain challenges will be crucial for ensuring consistent product availability and quality across the country.
Regulatory and Food Safety Standards
The India Fresh Processed Meat Product Market is also affected by the regulatory and food safety standards that govern the production and sale of meat products. The meat processing industry in India is subject to a variety of regulations imposed by government agencies, such as the Food Safety and Standards Authority of India (FSSAI). While these regulations aim to ensure food safety, they can also pose significant challenges for meat producers, especially smaller manufacturers, who may struggle to comply with the complex and evolving requirements. Issues related to food labeling, hygiene practices, and compliance with quality control standards can hinder product development and market access. Additionally, the enforcement of stricter regulations on preservatives, additives, and packaging could increase production costs, making it more challenging for businesses to offer competitive prices. Ensuring compliance with these standards while maintaining profitability remains a significant challenge for industry players in the fresh processed meat sector.
Market Opportunities
Expansion of Premium and Value-Added Products
The growing demand for premium and value-added meat products presents a significant opportunity for businesses in the India Fresh Processed Meat Product Market. As consumer preferences evolve, there is a noticeable shift towards high-quality, flavorful, and nutritious processed meat options. Consumers are increasingly seeking products that not only offer convenience but also cater to their tastes for innovation, such as gourmet sausages, seasoned cuts, and international meat varieties. This trend is particularly evident in urban centers, where disposable incomes are rising, and consumers are willing to invest in premium products. Additionally, the demand for value-added products that cater to specific dietary needs, such as low-fat, high-protein, and gluten-free options, is also on the rise. Companies that innovate to meet these demands—through enhanced flavors, packaging, or healthier formulations—can tap into the expanding market for premium processed meats, presenting an opportunity for growth and differentiation in a competitive landscape.
Untapped Rural Markets and E-Commerce Growth
While urban areas are the main drivers of market growth, there is significant potential in untapped rural and semi-urban regions. As rural incomes rise and urbanization spreads, more consumers in these regions are gaining access to processed meat products. To cater to this growing demand, companies can expand their distribution networks and tap into these emerging markets. Additionally, the increasing penetration of internet connectivity and e-commerce platforms presents an opportunity for brands to reach a broader audience. Online grocery and food delivery services are gaining popularity, providing a convenient way for consumers across both urban and rural areas to access fresh processed meat products. Leveraging these platforms to promote direct-to-consumer sales can offer new avenues for growth, further expanding the market reach.
Market Segmentation Analysis
By Product Type:
The market is divided into four main product categories: Fresh Meat, Poultry, Seafood, and Others. Among these, Fresh Meat holds the largest share due to its widespread use in daily meals and the increasing demand for protein-rich diets. Poultry products, including chicken, turkey, and duck, are also highly popular due to their affordability and versatility. Seafood, though a smaller segment, is growing steadily as consumers seek healthier alternatives to red meat. The Others category includes specialty meats such as game meat and processed products made from blends of different animal proteins.
By Application:
The market is further segmented based on application into Home Cooking, Foodservice, Ready-to-Eat Meals, Pet Food, and Others. Home Cooking remains a dominant segment as more consumers are cooking at home, often looking for fresh, high-quality meats. Foodservice, encompassing restaurants and catering services, is another significant sector, driven by the demand for processed meat in various cuisines. The Ready-to-Eat Meals segment is expanding rapidly due to increasing consumer preference for convenience foods. Pet Food is a growing application segment as pet owners look for high-protein, nutritious food options for their pets.
Segments
Based on Product Type
- Fresh Meat
- Poultry
- Seafood
- Others
Based on Application
- Home Cooking
- Foodservice
- Ready-to-Eat Meals
- Pet Food
- Others
Based on Packaging type
- Modified Atmosphere Packaging
- Vacuum Packaging
- Tray Packaging
- Others
Based on Certification
- Organic
- Halal
- Kosher
- BRC
- Others
Based on Distribution channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retailers
- Butcher Shops
- Others
Based on Region
- North India
- South India
- West India
- East India
Regional Analysis
North India (35%)
North India holds a substantial share of the India Fresh Processed Meat Product Market, accounting for approximately 35% of the overall market. This region has a strong demand for fresh processed meats, especially poultry, mutton, and pork. Urban centers like Delhi, Punjab, and Haryana have witnessed significant growth in the consumption of processed meat products, driven by rising disposable incomes and changing dietary habits. Additionally, the increasing popularity of convenience foods and ready-to-cook meat products has contributed to the growth in this region. Traditional butchery remains a key player in the market, but supermarkets, hypermarkets, and online retail channels are increasingly gaining market share.
South India (25%)
South India accounts for around 25% of the total market share in the India Fresh Processed Meat Product Market. The demand for poultry, particularly chicken, and seafood is prominent in states like Tamil Nadu, Kerala, and Karnataka. The southern region is known for its preference for fresh, high-quality meat products, with an emphasis on seafood in coastal areas. Furthermore, the growing inclination toward ready-to-eat and ready-to-cook meals is increasing the demand for processed meat in urban areas. The rise of supermarkets and e-commerce platforms is expected to further fuel market growth in this region.
Key players
- Amul (GCMMF) (India)
- Cargill India
- Venky's
- Mapro
- Licious
- National Foods
- HyFun Foods
- Hormel Foods Corporation
- Smithfield Foods
- Maple Leaf Foods
- Johnsonville
- Farmland Foods
Competitive Analysis
The India Fresh Processed Meat Product Market is highly competitive, with both local and global players vying for market share. Amul (GCMMF) leads with a strong brand presence and a diversified product portfolio, leveraging its vast distribution network and trusted reputation. Cargill India and Venky’s also hold significant positions, offering a wide range of processed meat products with a focus on quality and innovation. Licious has established a strong foothold in the online retail space, capitalizing on the growing demand for convenience and home delivery services. Meanwhile, Hormel Foods Corporation and Smithfield Foods represent the strong influence of international brands, bringing global expertise and advanced processing technologies to the Indian market. Additionally, companies like HyFun Foods and Mapro are focusing on specific niches, offering unique value propositions to consumers. As competition intensifies, innovation, product quality, and strategic distribution remain key drivers of success in this market.
Recent Developments
- In February 2025, GCMMF announced plans to establish a ₹600 crore dairy plant in Kolkata, which will feature the world's largest curd facility. This expansion is part of GCMMF's strategy to enhance its product offerings and cater to the growing demand for dairy products, including fresh processed meat options. The company reported an 8% increase in turnover for the 2023-24 financial year, reaching ₹59,445 crore, and anticipates double-digit revenue growth driven by strong demand across all product categories. This investment aligns with their goal of strengthening their presence in the fresh processed meat market by leveraging their extensive supply chain and farmer network to ensure high-quality raw materials.
- In January 2025, Cargill India announced the launch of several new items aimed at urban consumers seeking convenience without compromising quality. This initiative reflects Cargill's commitment to meeting the rising demand for processed meat while ensuring adherence to food safety standards and sustainability practices.
- In November 2024, Venky's launched a new range of marinated chicken products designed for quick meal preparation. This product line caters to the growing trend of convenience foods among busy consumers. The company aims to capture a larger share of the fresh processed meat market by focusing on innovative flavors and packaging that enhance user experience. Venky's marketing strategy emphasizes health-conscious consumers looking for nutritious yet convenient meal options.
- In January 2025, Hormel Foods Corporation unveiled a series of ready-to-eat meals featuring traditional Indian flavors, aiming to attract health-conscious consumers looking for convenient meal solutions. Hormel's strategy includes leveraging local partnerships to ensure the freshness and quality of its products while adhering to international food safety standards.
- In December 2024, Smithfield Foods announced plans to enter the Indian market with a focus on premium processed meat products. The company aims to introduce high-quality bacon and sausage options that cater to evolving consumer preferences for convenience and taste. This expansion reflects Smithfield's commitment to meeting the growing demand for processed meats in India while ensuring sustainable sourcing practices.
- In February 2025, Maple Leaf Foods highlighted their commitment to sustainability and health by launching these new offerings aimed at flexitarian consumers who are increasingly interested in reducing meat consumption while still enjoying flavorful meals.
- In November 2024, Farmland Foods announced that it would be launching a new line of frozen processed meat products designed specifically for the Indian market. This initiative aims to provide convenient meal solutions while maintaining high standards of quality and taste. The company plans to leverage local distribution channels to ensure widespread availability of its products across urban centers in India.
Market Concentration and Characteristics
The India Fresh Processed Meat Product Market exhibits a moderate to high level of concentration, with a mix of well-established domestic brands and international players competing for market share. Major players like Amul (GCMMF), Venky's, and Cargill India dominate the market, leveraging strong distribution networks and product diversification to maintain their position. However, the market is also characterized by the presence of newer, innovative brands such as Licious and HyFun Foods, which are tapping into the growing online retail space and focusing on convenience and premium offerings. The market is increasingly driven by factors such as rising disposable incomes, urbanization, and evolving consumer preferences toward convenience and quality. While larger players maintain significant market shares, smaller, niche players are rapidly gaining traction by offering differentiated products, such as organic, Halal, and value-added meat options, leading to a dynamic and evolving competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Packaging type, Certification, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for ready-to-eat and ready-to-cook meat products will continue to rise as busy lifestyles drive the need for convenience in meal preparation.
- As disposable incomes increase, more consumers will be able to afford premium processed meat products, contributing to market growth.
- The expansion of online grocery and meat delivery services will provide greater access to fresh processed meats, catering to the growing trend of online shopping.
- With an increasing focus on health and fitness, there will be a higher demand for lean, high-protein, and organic processed meat options.
- Advancements in processing technologies, such as improved preservation and packaging methods, will help extend shelf life and reduce waste, boosting market efficiency.
- The growth of plant-based meat substitutes will create new market segments, providing consumers with more sustainable and ethical options.
- Consumers will increasingly demand transparency in ingredients, leading to a surge in clean label processed meat products free from artificial additives and preservatives.
- As urbanization spreads, Tier 2 and Tier 3 cities will see increased demand for processed meat products, offering growth opportunities for manufacturers.
- Investments in cold chain logistics will ensure that fresh processed meat products maintain quality and reach consumers in remote areas, further expanding the market.
- The implementation of stricter food safety standards will drive innovation in quality control processes, enhancing consumer trust and market sustainability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the India Fresh Processed Meat Product Market in 2023 and 2032?
What factors are driving the growth of the India Fresh Processed Meat Product Market?
Which regions are contributing the most to the growth of this market?
Who are the key players in the India Fresh Processed Meat Product Market?
What trends are shaping the India Fresh Processed Meat Product Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Fresh Processed Meat Product Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Fresh Processed Meat Product Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 6,064.48 million → 2032: USD 10,503.32 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Fresh Processed Meat Product Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Fresh Processed Meat Product Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Fresh Processed Meat Product Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Fresh Processed Meat Product Market Drivers
- 3.3 India Fresh Processed Meat Product Market Restraints & Challenges
- 3.4 India Fresh Processed Meat Product Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Fresh Processed Meat Product Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Fresh Processed Meat Product Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Fresh Processed Meat Product category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Fresh Processed Meat Product Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Fresh Processed Meat Product Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Fresh Processed Meat Product market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Fresh Processed Meat Product Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Fresh Processed Meat Product Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Fresh Processed Meat Product Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Fresh Processed Meat Product (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Fresh Processed Meat Product Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Fresh Processed Meat Product Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Fresh Processed Meat Product Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Fresh Processed Meat Product Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Fresh Processed Meat Product Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Fresh Processed Meat Product Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Fresh Processed Meat Product Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Fresh Processed Meat Product Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Fresh Processed Meat Product Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
