
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Human Insulin Market Size 2024 | USD 604.52 million |
| India Human Insulin Market, CAGR | 6.53% |
| India Human Insulin Market Size 2032 | USD 1,069.26 million |
Market Overview
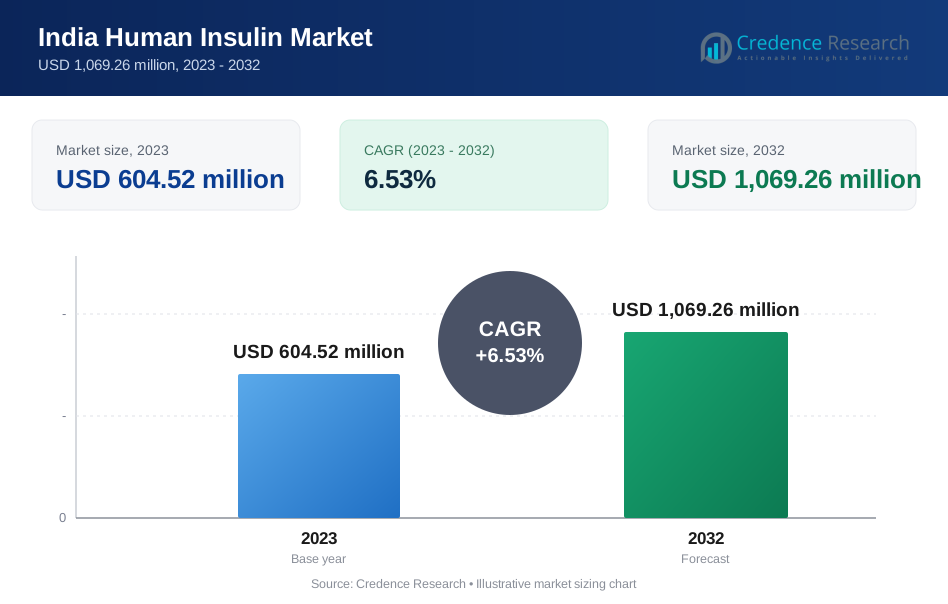
India Human Insulin market size was valued at USD 604.52 million in 2023 and is anticipated to reach USD 1,069.26 million by 2032, at a CAGR of 6.53% during the forecast period (2023-2032).
The India Human Insulin market is driven by the rising prevalence of diabetes, with an increasing number of people being diagnosed each year. Factors such as an aging population, urbanization, and changing dietary habits contribute to this growth. The growing awareness of diabetes management and the importance of insulin therapy further boosts market demand. Additionally, advancements in insulin formulations, such as rapid-acting and long-acting insulin, are enhancing treatment options, making them more accessible and effective. Government initiatives to improve healthcare access and affordability, along with the expansion of healthcare infrastructure, also support market expansion. Trends such as the shift towards biosimilar insulin, which offers a cost-effective alternative to traditional insulin products, are gaining traction. Furthermore, innovations in insulin delivery systems, including insulin pens and pumps, are improving patient convenience and compliance, thereby driving market growth in India.
Geographically, the India Human Insulin market is expanding across all regions, with varying levels of growth driven by factors like urbanization, healthcare infrastructure, and diabetes prevalence. The Northern and Western regions, particularly cities like Delhi, Mumbai, and Pune, dominate the market due to well-established healthcare systems and higher awareness of diabetes management. The Southern region, with major hubs like Bangalore and Chennai, is also seeing significant growth, spurred by increasing healthcare accessibility and growing diabetic populations. The Eastern region, though lagging behind, is gradually catching up as urbanization accelerates and healthcare improves. Key players in the Indian human insulin market include global giants such as Novo Nordisk, Eli Lilly, and Pfizer, along with local pharmaceutical companies like Biocon, Wockhardt, and Lupin. These companies play a crucial role in offering a wide range of insulin products, including both branded and biosimilars, to cater to India’s diverse diabetic population.
Market Insights
- The India Human Insulin market was valued at USD 604.52 million in 2023 and is expected to reach USD 1,069.26 million by 2032, growing at a CAGR of 6.53% from 2023 to 2032.
- The global human insulin market was valued at USD 21,000 million in 2023 and is projected to reach USD 31,208 million by 2032, growing at a CAGR of 4.50% from 2023 to 2032.
- Increasing diabetes prevalence due to urbanization, sedentary lifestyles, and aging population is a major market driver.
- Advancements in insulin delivery devices, such as insulin pens and pumps, are contributing to improved patient convenience and adherence.
- The growing adoption of biosimilar insulin products offers cost-effective alternatives to branded insulin therapies.
- Competition is intense, with key players like Novo Nordisk, Eli Lilly, Biocon, and Lupin leading the market.
- Regulatory challenges, including complex approval processes for new insulin products, are a significant market restraint.
- Regional variations in diabetes prevalence and healthcare infrastructure create diverse growth opportunities across Northern, Southern, Western, and Eastern India.
Report Scope
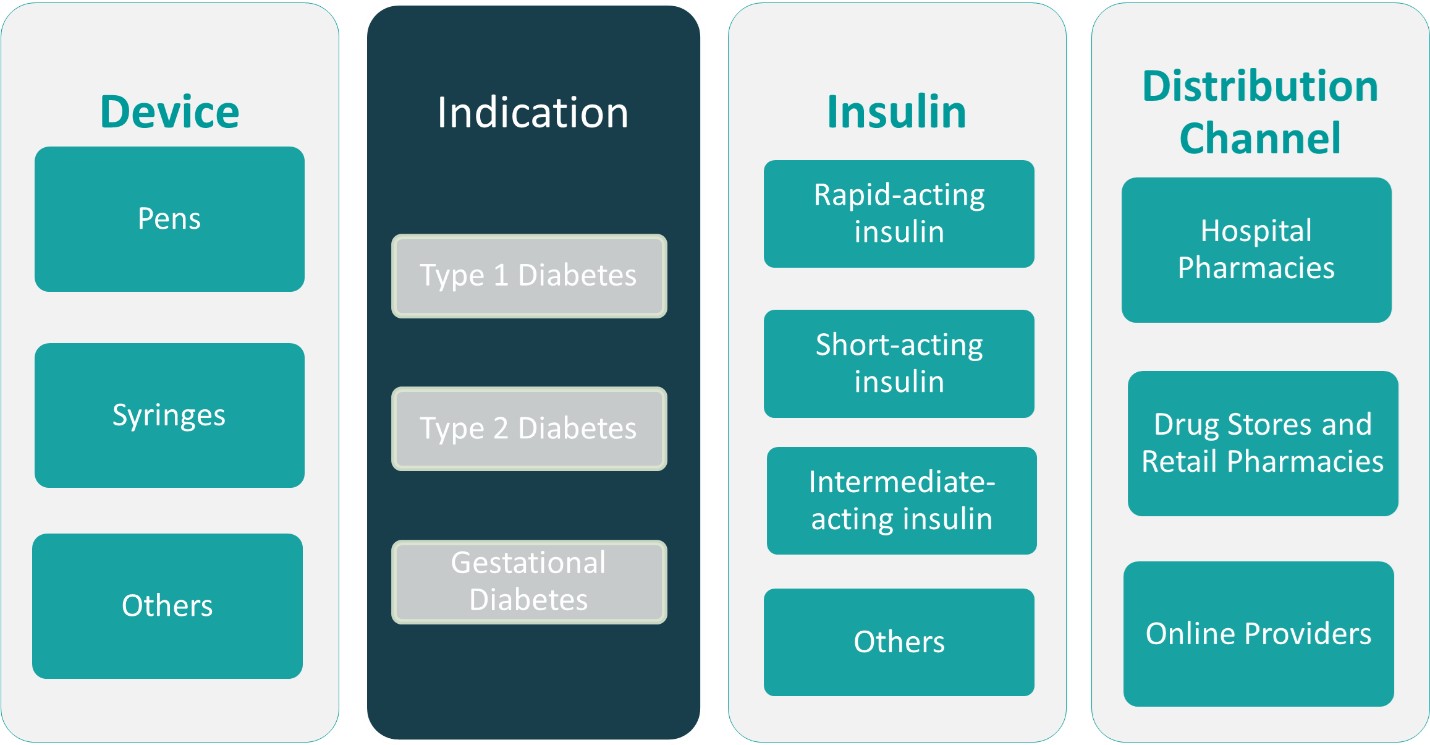
This report segments the India Human Insulin Market as follows:
Market Drivers
Rising Prevalence of Diabetes
One of the primary drivers of the India Human Insulin market is the growing prevalence of diabetes in the country. For instance, according to the International Diabetes Federation (IDF), India is home to the second-largest diabetic population globally, with millions of new diagnoses every year. The increase in diabetes cases is largely attributed to factors such as an aging population, urbanization, sedentary lifestyles, and unhealthy dietary habits. The rise in obesity rates, coupled with reduced physical activity, has led to a higher incidence of type 2 diabetes, further driving demand for insulin products. As more individuals seek effective diabetes management, the need for human insulin therapy is expected to continue growing, creating a substantial market opportunity.
Government Initiatives and Healthcare Access
Government initiatives aimed at improving healthcare access and affordability have played a significant role in the growth of the human insulin market in India. For instance, the National Pharmaceutical Pricing Authority (NPPA) regulates insulin prices under the Drug Price Control Order (DPCO) to prevent overpricing by pharmaceutical companies. The government’s focus on increasing healthcare funding, particularly for diabetes treatment, is helping to make insulin more accessible to a wider population. Public health campaigns designed to raise awareness about diabetes prevention and management also contribute to the market’s expansion. Additionally, the implementation of the Pradhan Mantri Jan Arogya Yojana (PMJAY), a government health insurance scheme, has increased access to essential medicines, including insulin, for millions of low-income families. As the Indian government continues to prioritize healthcare for its citizens, the demand for human insulin is expected to rise, benefiting both patients and manufacturers.
Advancements in Insulin Formulations and Delivery Methods
Technological advancements in insulin formulations and delivery methods have significantly contributed to the growth of the human insulin market in India. Modern insulin formulations, including rapid-acting, long-acting, and premixed insulins, offer improved flexibility and better glycemic control for diabetic patients. These advancements provide patients with more options to manage their diabetes based on their lifestyle and medical needs. Furthermore, innovations in insulin delivery systems, such as insulin pens, pumps, and smart devices, have made insulin administration more convenient, reducing patient discomfort and improving adherence to treatment regimens. These improvements in insulin products enhance the effectiveness of diabetes management and are expected to continue driving market growth.
Growing Adoption of Biosimilar Insulin
The increasing adoption of biosimilar insulin in India is another significant driver of the market. Biosimilars are biologic products that are highly similar to already approved reference insulin products but are more affordable, making them an attractive option for cost-conscious patients. The shift towards biosimilars has been further accelerated by government regulations aimed at promoting the availability of affordable medicines. Biosimilars offer a competitive alternative to patented insulin products, making them more accessible to a larger segment of the population. This trend is helping to address the high cost of diabetes treatment in India and is expected to expand the market for human insulin, particularly in lower-income groups. As more biosimilar products gain approval and acceptance, the Indian human insulin market is poised for continued growth.
Market Trends
Surge in Diabetes Prevalence
India's escalating diabetes burden is a primary driver of the human insulin market. For instance, India has the second-largest diabetic population globally, with over 74 million people diagnosed with diabetes in 2021. Factors such as urbanization, sedentary lifestyles, and poor dietary habits contribute to this surge. The increasing number of diabetes cases necessitates effective management solutions, thereby propelling the demand for insulin therapies. Government initiatives like the National Programme for Prevention and Control of Cancer, Diabetes, Cardiovascular Diseases & Stroke (NPCDCS) aim to address this growing health concern, further boosting the insulin market.
Advancements in Insulin Delivery Devices
Technological innovations in insulin delivery systems are transforming diabetes management in India. For instance, the India Insulin Drug and Delivery Device Market Report highlights the increasing adoption of insulin pens, pumps, and smart devices. These devices offer precise dosing, portability, and user-friendly features, making insulin administration more manageable for patients. The growing preference for home care settings, driven by the COVID-19 pandemic, has further accelerated the demand for these advanced delivery systems.
Emergence of Biosimilar Insulin
The introduction of biosimilar insulin products is reshaping the Indian insulin market by providing cost-effective alternatives to branded insulin therapies. Indian pharmaceutical companies are developing biosimilars to cater to the price-sensitive population, thereby increasing insulin accessibility. Government policies supporting biosimilar development and approval processes have facilitated their entry into the market. This trend is expected to continue, offering patients more affordable treatment options and expanding the insulin market.
Integration of Artificial Intelligence in Diabetes Management
The integration of artificial intelligence (AI) in diabetes care is an emerging trend in India. AI-powered tools and applications are being developed to assist in monitoring blood glucose levels, predicting insulin needs, and providing personalized treatment recommendations. These innovations aim to improve treatment outcomes and patient quality of life. The increasing availability of smartphones and internet connectivity in India supports the adoption of AI-based solutions, indicating a promising future for technology-driven diabetes management.
Market Challenges Analysis
High Cost of Insulin and Affordability Issues
One of the significant challenges facing the India Human Insulin market is the high cost of insulin, particularly branded products, which remains a barrier for many diabetic patients, especially in low-income and rural areas. For instance, the National Pharmaceutical Pricing Authority (NPPA) regulates insulin prices under the Drug Price Control Order (DPCO) to prevent overpricing by pharmaceutical companies. Despite government initiatives to improve healthcare access, the affordability of insulin is still a major issue for a large section of the population. Although biosimilar insulin offers a more affordable alternative, the cost of even these products can be prohibitive for some patients. The lack of universal health insurance coverage for all citizens and the dependence on out-of-pocket expenses for a majority of the population exacerbates this challenge. Ensuring affordable access to insulin for all economic segments remains a key hurdle in the widespread management of diabetes in India.
Regulatory and Supply Chain Challenges
The regulatory environment surrounding the production and approval of insulin in India poses another challenge to market growth. While the Indian government has streamlined approval processes for biosimilars, the regulatory hurdles for introducing new insulin formulations and maintaining quality standards can be complex and time-consuming. Additionally, issues within the supply chain, such as inconsistent cold chain logistics for storing insulin, can impact the availability and efficacy of insulin products, especially in rural and remote areas. These supply chain disruptions often lead to insulin shortages or delays, affecting patient access to treatment. Addressing these regulatory and logistical challenges will be crucial to ensuring that insulin products are consistently available and accessible to the growing diabetic population in India.
Market Opportunities
The India Human Insulin market presents significant opportunities due to the growing burden of diabetes and the increasing need for effective diabetes management solutions. With diabetes rates rising steadily, driven by lifestyle changes, urbanization, and an aging population, there is a growing demand for insulin products. This creates a substantial market opportunity for manufacturers to cater to a broad range of diabetic patients. Additionally, the expansion of healthcare infrastructure and the government’s focus on improving access to healthcare, including the introduction of health insurance schemes like PMJAY, further enhances the accessibility of insulin to a larger segment of the population. This enables market players to reach untapped rural and semi-urban regions, where the prevalence of diabetes is rising but insulin access remains limited.
Furthermore, the increasing adoption of biosimilar insulin products offers considerable market potential. As biosimilars are more affordable compared to branded insulin, they provide an opportunity to reach price-sensitive populations while maintaining high therapeutic efficacy. The Indian government’s favorable policies regarding biosimilar development and approval processes are expected to drive the market’s expansion in this segment. Additionally, the growing trend of home care and advancements in insulin delivery devices, such as insulin pens and smart pumps, present opportunities for companies to innovate and offer more convenient, patient-friendly products. The rise in digital health solutions, including AI-powered tools for diabetes management, further provides opportunities for companies to explore new avenues of growth in the Indian market. These factors position India as a key market for human insulin, offering promising opportunities for both local and international players.
Market Segmentation Analysis:
By Device:
In the India Human Insulin market, the device segment is categorized into pens, syringes, and other insulin delivery systems. Insulin pens hold the largest market share due to their convenience, precision, and ease of use. These pens are designed to be portable and user-friendly, with adjustable dosage settings, making them increasingly popular among diabetic patients. They are preferred for their ability to provide accurate dosing and minimize pain during injection, contributing to higher patient adherence to prescribed regimens. Syringes, although still widely used, have seen a decline in preference in recent years, mainly due to their less convenient and more time-consuming nature. However, syringes remain an essential delivery method, particularly in rural areas with limited access to advanced healthcare devices. Additionally, other delivery systems, such as insulin pumps and continuous glucose monitors, are emerging in the market. These devices offer continuous insulin infusion and better glucose control, especially in patients with more complex diabetes management needs. The adoption of advanced delivery systems is expected to grow as the market shifts towards more personalized and effective diabetes management solutions.
By Indication:
The India Human Insulin market is also segmented based on the indication, including Type 1 diabetes, Type 2 diabetes, and gestational diabetes. Type 2 diabetes represents the largest segment, primarily due to the increasing prevalence of lifestyle-related risk factors such as poor diet, obesity, and a sedentary lifestyle. The rising number of Type 2 diabetes cases in India is driving substantial demand for insulin products. Type 1 diabetes, although less common, remains a key segment as insulin is crucial for managing this autoimmune condition. The growing awareness and early diagnosis of Type 1 diabetes are further contributing to market growth. Gestational diabetes, which affects pregnant women, is another important segment, though smaller in comparison to the other two. As awareness around gestational diabetes increases and more women are diagnosed, the demand for insulin therapies tailored for pregnant women is expected to rise.
Segments:
Based on Device:
- Pens
- Syringes
- Others
Based on Indication:
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes
Based on Insulin:
- Rapid-acting insulin
- Short-acting insulin
- Intermediate-acting insulin
- Others
Based on Distribution Channel:
- Hospital Pharmacies
- Drug Stores and Retail Pharmacies
- Online Providers
Based on the Geography:
- Northern
- Western
- Southern
- Eastern
Regional Analysis
Northern Region
The Northern region of India holds a significant share of the human insulin market, accounting for approximately 30% of the total market. This region’s large share is driven by the high prevalence of diabetes, particularly in states like Delhi, Punjab, Haryana, and Uttar Pradesh. Urbanization, sedentary lifestyles, and dietary changes are major contributing factors to the rising number of diabetic patients in the North. Moreover, the region has a well-established healthcare infrastructure with several private and public hospitals offering insulin therapy, which supports market growth. The increasing awareness of diabetes management and the availability of advanced insulin delivery systems such as insulin pens and pumps are also contributing to the expansion of the insulin market in Northern India.
Western Region
The Western region of India, including states like Maharashtra, Gujarat, Rajasthan, and Madhya Pradesh, holds a market share of approximately 25%. The rise in Type 2 diabetes cases, fueled by factors such as high urbanization rates, changing diets, and increasing obesity levels, is a key driver of insulin demand in this region. Major urban centers like Mumbai, Pune, and Ahmedabad have a well-developed healthcare system, which ensures widespread availability of insulin products. Furthermore, Western India’s pharmaceutical industry, with a strong presence of both international and local manufacturers, plays a vital role in meeting the region’s demand for insulin, including biosimilars. This, coupled with the growing preference for home-based diabetes care, strengthens the region’s market position.
Southern Region
The Southern region, comprising states like Tamil Nadu, Karnataka, Andhra Pradesh, Telangana, and Kerala, holds a 20% share of the India Human Insulin market. The high incidence of diabetes in these states is largely due to dietary habits, increasing stress levels, and urbanization. Cities such as Bangalore, Chennai, and Hyderabad are major healthcare hubs where advanced diabetes treatments, including insulin therapy, are readily available. The rise of healthcare awareness in this region, along with increasing government health programs, has led to a steady increase in insulin demand. Additionally, with the expansion of health insurance coverage, more people in the Southern region are able to afford insulin therapies, further driving market growth.
Eastern Region
The Eastern region of India, which includes states like West Bengal, Odisha, Bihar, and Jharkhand, currently holds the smallest market share of around 15%. While diabetes is on the rise in Eastern India due to factors such as changing dietary patterns and growing obesity rates, the region lags behind in terms of healthcare infrastructure and access to insulin. However, with increasing urbanization and the gradual improvement of healthcare facilities, the insulin market in Eastern India is poised for growth. Awareness campaigns and government health schemes in these states are expected to boost the adoption of insulin products. As healthcare access improves, the region’s share in the overall market is likely to increase over time.
Key Player Analysis
- Novo Nordisk A/S
- MannKind Corporation
- Pfizer
- Wockhardt
- Biocon
- Lupin
- Tonghua Dongbao Pharmaceutical Co
- Eli Lilly and Company
- Eris Lifesciences
Competitive Analysis
The competitive landscape of the India Human Insulin market is dominated by both global and local players, each contributing to the market’s growth through innovation and strategic market positioning. Leading international companies such as Novo Nordisk, Eli Lilly, Pfizer, and MannKind Corporation hold a significant share, offering a range of insulin products including both branded and biosimilar insulin. Global players lead the market with their broad portfolio of insulin products, including both branded and biosimilar insulin, and focus on advanced insulin delivery systems like pens, pumps, and smart devices. Their strong presence is supported by extensive research and development, ensuring continuous improvements in insulin formulations and patient-centric solutions. Local companies have gained considerable traction by offering more affordable insulin alternatives, especially biosimilars, catering to the price-sensitive segment of the market. These players often leverage cost-effective manufacturing practices to meet the demand for insulin products in rural and semi-urban regions, where accessibility and affordability remain key challenges. The competition also extends to the development of patient-friendly delivery devices, as well as the introduction of digital health solutions to improve diabetes management. Overall, the market is highly competitive, with players focusing on product innovation, strategic pricing, and strong distribution networks to maintain their market positions and meet the diverse needs of India’s diabetic population.
Recent Developments
- In April 2025, Novo Nordisk announced the discontinuation of Human Mixtard, India’s largest-selling human insulin brand, as part of a global strategy to prioritize newer, patented diabetes and weight loss therapies such as Ozempic and Wegovy. While vial forms of Mixtard, Actrapid, and Insulatard will remain available, pen devices (Penfills and FlexPens) are being phased out, which is expected to disrupt patient access and preference in India.
- In April 2025, Pfizer discontinued the development of danuglipron, its once-daily oral GLP-1 receptor agonist for obesity and type 2 diabetes, following a case of drug-induced liver injury and after reviewing clinical and regulatory feedback. This decision halts further clinical development for both obesity and diabetes indications.
- In March 2025, Biocon Biologics entered a strategic collaboration with Civica, Inc. to expand access to Insulin Aspart in the United States. Biocon will supply the drug substance, which Civica will formulate and commercialize after completing development and clinical trials.
- In December 2024, Lupin acquired the Huminsulin® portfolio in India from Eli Lilly and Company. The range includes Insulin Human (Huminsulin R, NPH, 50/50, and 30/70) and is indicated for type 1 and type 2 diabetes. Lupin had previously marketed these products under a distribution agreement, and the acquisition is aimed at strengthening its diabetes portfolio.
- In November 2024, MannKind’s Afrezza® (insulin human) Inhalation Powder received approval from India’s CDSCO. MannKind expects to ship product to its partner Cipla by the end of 2025.
- In October 2024, Wockhardt filed for approval of its fast-acting insulin analog, Aspart injection (ASPARAPID™), with the Drugs Controller General of India (DCGI). The product, developed indigenously, will be offered in cartridges, vials, and prefilled disposable pens. This expands Wockhardt’s diabetes biosimilars portfolio and addresses a market with limited competition.
Market Concentration & Characteristics
The India Human Insulin market exhibits moderate concentration, with a mix of global and local players dominating the landscape. A few multinational companies hold a substantial market share due to their extensive product portfolios, which include both branded and biosimilar insulin options. These companies benefit from strong research and development capabilities, offering advanced insulin formulations and delivery systems. However, local players have gained significant traction by providing cost-effective alternatives, particularly in biosimilars, making insulin more accessible to the large, price-sensitive diabetic population in India. The market is characterized by a growing focus on patient-centric solutions, with increasing adoption of insulin pens, pumps, and other user-friendly delivery devices. Moreover, the rise in government initiatives and insurance coverage is making insulin more accessible to a broader demographic. Despite the competition, the market remains dynamic, with ongoing innovation in both insulin products and delivery systems driving the growth of the sector.
Report Coverage
The research report offers an in-depth analysis based on Device, Indication, Insulin, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for human insulin in India is expected to continue growing due to the increasing prevalence of diabetes.
- The market will see a significant shift towards biosimilar insulin products, driven by their affordability.
- Advances in insulin delivery systems, such as insulin pens and pumps, will lead to greater patient convenience and improved adherence.
- There will be a growing focus on digital health solutions, including AI-powered tools for personalized diabetes management.
- The expansion of healthcare insurance coverage will make insulin products more accessible to a larger population.
- Government initiatives and healthcare policies will play a pivotal role in improving access to insulin, especially in rural areas.
- The increasing adoption of home-based diabetes management will further boost the demand for insulin products.
- Regional disparities in healthcare infrastructure will create unique growth opportunities in underserved areas.
- Local manufacturers will continue to expand their presence with cost-effective insulin options to cater to price-sensitive segments.
- As healthcare awareness improves, more people will seek timely insulin treatment, driving market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Human Insulin?
What factors are driving the growth of the India Human Insulin?
What are some challenges faced by the India Human Insulin?
Who are the major players in the India Human Insulin?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Human Insulin Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Human Insulin Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 604.52 million → 2032: USD 1,069.26 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Human Insulin Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Human Insulin Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Human Insulin Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Human Insulin Market Drivers
- 3.3 India Human Insulin Market Restraints & Challenges
- 3.4 India Human Insulin Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Human Insulin Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Human Insulin Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Human Insulin category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Human Insulin Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Human Insulin Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Human Insulin market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Human Insulin Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Human Insulin Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Human Insulin Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Human Insulin (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Human Insulin Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Human Insulin Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Human Insulin Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Human Insulin Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Human Insulin Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Human Insulin Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Human Insulin Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Human Insulin Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Human Insulin Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
