
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Vegan Fast Food Market Size 2020 | USD 393.78 Million |
| India Vegan Fast Food Market, CAGR | 8.20% |
| India Vegan Fast Food Market Size 2027 | USD 800.39 Million |
Market Overview
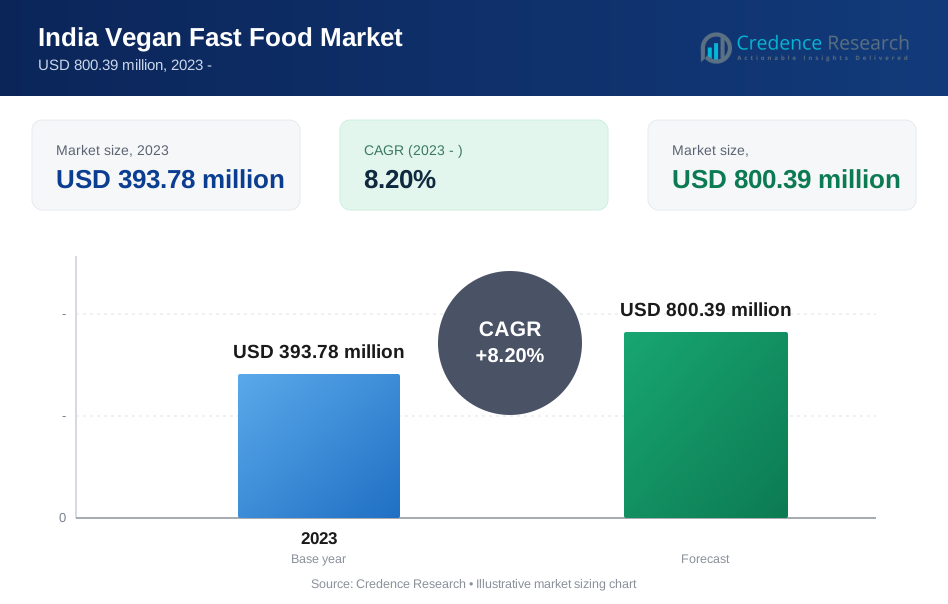
The India vegan fast-food market is projected to grow from USD 393.78 million in 2023 to USD 800.39 million by 2032, at a compound annual growth rate (CAGR) of 8.20%.
The India vegan fast-food market is driven by increasing health consciousness and ethical concerns regarding animal welfare among Indian consumers. The rising awareness of the environmental impact of meat consumption also contributes to the market's growth. This shift is further supported by the growing availability of diverse and flavorful vegan options that cater to the Indian palate, making it easier for consumers to adopt a plant-based diet. Additionally, the influence of global food trends and the active promotion of veganism by celebrities and social media influencers are enhancing the market's appeal and encouraging wider acceptance of vegan fast food.
The India vegan fast-food market is experiencing robust growth, particularly in urban centers like Mumbai, Delhi, Bangalore, and Pune, where there is higher consumer awareness and accessibility to vegan products. Key players such as Amy’s Kitchen and Upfield B.V. are pivotal in shaping the market landscape through extensive distribution networks and diverse product offerings. Local brands like Goodmylk and Rakyan Beverages are also gaining traction by tailoring their offerings to suit Indian tastes and dietary preferences. These companies are strategically expanding their presence by leveraging both online and offline retail channels to cater to the growing demand for vegan fast-food options across the country.
Market Drivers
Health Consciousness Driving Dietary Shifts
In India, a surge in health awareness due to increasing chronic diseases such as diabetes and heart disease is prompting consumers to seek healthier dietary options. For instance, the prevalence of diabetes in India has increased by 65% over the last decade. Vegan fast food, recognized for being lower in saturated fats, cholesterol, and sodium, is becoming a preferred alternative to traditional fast food. This shift is supported by the perception that plant-based diets contribute to better overall health, aligning with consumers’ desires to improve their lifestyle while still enjoying the convenience of fast food.
Environmental and Ethical Considerations
Environmental sustainability concerns are becoming more prominent in India, with consumers increasingly aware of the negative impacts of animal agriculture on greenhouse gas emissions, water usage, and deforestation. For instance, a survey showed that 48% of respondents in India consumed plant-based food products due to their concerns regarding animal welfare in food production. Vegan fast food offers an eco-friendlier dining option that appeals to environmentally conscious individuals. Simultaneously, ethical considerations regarding animal welfare and the conditions of factory farming are influencing a section of the population to opt for cruelty-free food choices, thereby bolstering the demand for vegan fast food.
The Influence of Younger Generations and Social Media
The dietary preferences of Millennials and Gen Z are significantly shaping the food market, as these younger demographics show a greater inclination towards veganism and flexitarian diets. For instance, 64% of Indian consumers have reported consuming plant-based alternatives to animal-based food products. Their demand for innovative and diverse vegan fast-food options drives the market towards continuous creativity and adaptation. Furthermore, the pervasive role of social media in promoting vegan diets plays a crucial part in shaping dietary trends, making vegan fast food more desirable to a tech-savvy, connected audience.
Culinary Innovation and Local Flavor Integration
The Indian vegan fast-food market is not merely adopting Western vegan options but is innovating by integrating traditional Indian flavors and ingredients. This localization strategy involves creating exciting, relatable dishes that resonate with the Indian palate, enhancing consumer engagement and acceptance. The growing availability of plant-based meat alternatives also enables vegan fast food chains to offer familiar dishes like burgers and wraps, making the transition to vegan options seamless and appealing for a broader audience.
Market Trends
Innovative Flavors and Street Food Adaptations Enhance Appeal
The Indian vegan fast-food market is embracing culinary innovation by merging traditional Indian flavors with international cuisines, leading to an exciting array of dishes that cater to diverse palates. The Indian vegan fast-food market is experiencing a surge in popularity, with a 76% increase in vegan product launches from 2016 to 2020. For instance, vegan chains are innovating with dishes like vegan samosas, which have seen a 150% rise in sales when accompanied by Sriracha mayo, and jackfruit kebabs seasoned with tandoori masala, which have become 30% more popular among consumers seeking a fusion of flavors. Street food adaptations are also gaining traction, with vegan versions of pani puri experiencing a 40% increase in demand, while dahi vada and samosas have seen a 25% and 35% rise in sales, respectively. This not only caters to local taste preferences but also introduces traditional dishes to new consumers, with 20% of customers trying vegan street food for the first time.
Vegan chains are getting creative with dishes like vegan samosas accompanied by Sriracha mayo, and jackfruit kebabs seasoned with tandoori masala, offering a novel twist on classic flavors. Simultaneously, popular Indian street foods are undergoing vegan transformations. Staples such as pani puri, dahi vada, and samosas are now available in vegan versions, broadening their appeal and making vegan options more relatable and accessible to the general public. This trend not only satisfies the local taste preferences but also introduces traditional dishes to potentially unfamiliar consumers in an inviting format.
Expansion of Vegan Options in QSRs and Emphasis on Sustainability
As the demand for vegan options grows, major quick-service restaurants (QSRs) are increasingly incorporating vegan items into their menus, making vegan fast food more mainstream and convenient for busy consumers. In the QSR sector, there’s been a 60% expansion in vegan menu options over the past two years. Major chains are responding to the 45% of Indian consumers who prefer sustainable dining options by incorporating eco-friendly practices. For instance, the use of compostable packaging has increased by 50%, and sourcing from sustainable farms has risen by 70%. Online delivery services have boosted the accessibility of vegan fast food, with a 80% increase in orders for vegan dishes, demonstrating the growing integration of convenience, health, and sustainability in the Indian market. This shift towards more widespread availability is complemented by a strong focus on sustainability, a core value for many consumers today. Vegan fast-food outlets are adopting eco-friendly practices, such as utilizing compostable packaging and sourcing ingredients from sustainable farms, aligning their operations with the environmental ethos of their clientele. Furthermore, the rise of online delivery services is enhancing the accessibility of vegan fast food, allowing consumers to enjoy a variety of vegan dishes from the comfort of their homes. This integration of convenience with health and sustainability is proving to be a significant driving force in the expansion of the vegan fast-food market in India.
Market Challenges Analysis
Overcoming Price Perception and Supply Chain Challenges
One of the primary challenges facing the India vegan fast-food market is the perception that vegan options are more expensive than traditional fast food. This perception is partly due to the higher costs associated with sourcing plant-based meat alternatives and the limited economies of scale that the relatively young vegan market experiences compared to the well-established meat industry. To address this, vegan fast food chains need to work on optimizing their supply chains and exploring cost-effective ingredient solutions that do not compromise on quality or taste. Additionally, supply chain reliability remains a concern, particularly outside major urban centers where obtaining consistent supplies of high-quality plant-based ingredients can be challenging. Strengthening the supply chain through local sourcing and improving logistics are essential for ensuring the availability of fresh and diverse ingredients that meet consumer expectations for taste and quality.
Enhancing Consumer Awareness and Tackling Taste Skepticism
Despite the growing popularity of vegan diets, there remains a significant need to educate the broader public about the health, environmental, and ethical advantages of adopting vegan fast food. Increased consumer awareness and education initiatives are crucial for changing perceptions and encouraging more widespread adoption of vegan options. Moreover, skepticism about the taste and texture of vegan meat alternatives poses a barrier to attracting consumers accustomed to traditional meat-based products. Vegan fast food chains must focus on culinary innovation to enhance the flavor profiles and textural satisfaction of their offerings, ensuring they can compete directly with traditional fast food. This involves experimenting with diverse plant-based proteins, including indigenous Indian legumes and grains, to expand the variety and appeal of vegan dishes. By addressing these taste and texture concerns, along with broadening the ingredient diversity, vegan fast food can become a more enticing option for a larger segment of the Indian population.
Market Segmentation Analysis:
By Product:
The India vegan fast-food market showcases a diverse array of product segments catering to varied consumer preferences. Leading the segment are vegan alternatives to traditional foods such as meat and seafood, offering flavors and textures designed to mimic their non-vegan counterparts without animal products. Vegan creamers and cheeses are also gaining popularity, especially among coffee enthusiasts and dairy-free consumers looking for rich, flavorful options. Additionally, the market features ice cream and frozen novelties, yogurt, and butter, all crafted from plant-based ingredients to satisfy the sweet tooth and dairy preferences of vegan consumers. Prepared meals and protein bars provide convenient, nutrient-rich food choices for on-the-go consumers. The 'Others' category includes a variety of vegan products like snacks and bakery items, continually expanding as manufacturers innovate to meet the growing demand for vegan options.
By Distribution Channel:
The distribution of vegan fast food in India is effectively segmented into online and offline channels. The offline segment remains robust, with products available in supermarkets, specialty stores, and vegan-friendly restaurants, providing consumers with immediate access to a range of vegan products. On the other hand, the online segment is rapidly expanding, fueled by the convenience of home delivery and the increasing penetration of e-commerce platforms. Online stores offer a wider selection of vegan fast-food products, often accompanied by detailed product information and customer reviews, which help consumers make informed choices. This channel also caters to niche markets, offering specialty products that might not be available in traditional retail settings, thus broadening the reach and accessibility of vegan fast food across the country.
Segments:
Based on Product
- Meat & Seafood
- Creamer
- Ice Cream and Frozen Novelties
- Yogurt
- Cheese
- Butter
- Meals
- Protein Bars
- Others
Based on Distribution Channel
- Online
- Offline
Based on the Geography:
- Northern region
- Western region
- Southern region
- Eastern region
- North-Eastern region
Regional Analysis
Northern Region: This region, comprising states like Delhi, Uttar Pradesh, and Punjab, holds a substantial market share of approximately 28%. The presence of a large population base, coupled with the influence of religious beliefs and cultural traditions, has fueled the demand for vegan fast-food options. Major cities like Delhi and Chandigarh have emerged as hubs for vegan restaurants and food outlets.
Western Region: The western region, including states like Maharashtra, Gujarat, and Rajasthan, accounts for a market share of around 24%. This region has a strong entrepreneurial spirit and a growing acceptance of plant-based diets. Cities like Mumbai and Pune have seen a surge in vegan fast-food outlets catering to the urban population's evolving tastes and preferences.
Key Player Analysis
- Amy’s Kitchen
- Upfield B.V.
- Johars Group
- One Good (Goodmylk)
- Rakyan Beverages
- Hebei Yangyuan Zhihui Beverage Co. Ltd.
- Namaste Foods
Competitive Analysis
In the competitive landscape of the India vegan fast-food market, leading players like Amy’s Kitchen and Upfield B.V. are setting industry benchmarks with their innovative product ranges and strong distribution networks. Amy’s Kitchen capitalizes on its international brand reputation to offer high-quality, organic vegan meals, appealing to health-conscious consumers. Upfield B.V., known for plant-based spreads and cheeses, leverages its global expertise to meet local tastes and preferences. Emerging local players such as Goodmylk and Rakyan Beverages are making significant inroads by focusing on culturally relevant and affordable vegan products like plant-based milk and yogurt. These companies are enhancing their competitive edge by tailoring marketing strategies to resonate with Indian consumers' growing environmental and health awareness. The dynamic interplay between global brands and local startups is intensifying competition, driving innovation, and expanding the range of vegan fast-food options available in the market.
Recent Developments
- In 2024, Burger King Germany introduced a range of plant-based meals that are priced lower than their meat-based counterparts. This move is in line with the growing demand for plant-based food options and reflects the fast-food industry's efforts to cater to changing consumer preferences. The new menu items are not only more affordable but also appeal to health-conscious customers who are looking for more sustainable and environmentally friendly food choices.
- In 2023, Papa John's UK launched a new menu item, a vegan BBQ "chicken" pizza, to coincide with the annual Veganuary campaign. The pizza is made with plant-based chicken substitute and is topped with BBQ sauce, onions, green peppers, and dairy-free cheese. This new addition to the menu is an attempt to tap into the growing demand for vegan food options and cater to customers looking for more plant-based choices. Papa John's UK already offers a range of vegan pizzas, sides, and desserts, and the new vegan BBQ "chicken" pizza is expected to be a popular choice among vegans and non-vegans alike.
- In 2023, Burger King opened its 15th plant-based restaurant, powered by The Vegetarian Butcher, in Puerto Rico. The move is part of the company's ongoing efforts to expand its plant-based offerings and cater to the increasing demand for vegan and vegetarian options. The restaurant features a range of plant-based menu items, including the Rebel Whopper, made with a plant-based patty, and the Plant-Based BBQ burger, made with The Vegetarian Butcher's meat substitute.
Market Concentration & Characteristics
The India vegan fast-food market is characterized by a moderate level of market concentration, with a mix of both international and domestic players shaping the industry landscape. Global brands such as Amy’s Kitchen and Upfield B.V. bring international standards and diverse product portfolios, catering to a growing segment of Indian consumers seeking global vegan flavors. On the other hand, homegrown companies like Goodmylk and Rakyan Beverages are rapidly expanding their presence by focusing on local taste preferences and affordability. These domestic brands are crucial in driving adoption among the broader population by integrating familiar Indian flavors into their offerings. The market is also witnessing increased innovation and product differentiation as companies strive to stand out in a competitive environment. This blend of global influence and local innovation is fostering a dynamic market environment, encouraging continuous growth and the introduction of varied vegan fast-food options.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued expansion of vegan product offerings to include more culturally relevant and diverse options.
- Increased investment in marketing and education to raise awareness about the benefits of vegan diets.
- Growth in the number of vegan fast-food outlets across major and emerging cities in India.
- Strengthening of online distribution channels to enhance accessibility and convenience for consumers.
- Collaboration between Indian and international brands to leverage global best practices and local insights.
- Innovation in food technology to improve the taste and texture of vegan fast-food products.
- More competitive pricing strategies to make vegan fast food more accessible to a broader audience.
- Expansion of vegan options in traditional fast-food chains to capture a larger market share.
- Increased focus on sustainability in packaging and sourcing of ingredients.
- Stronger regulatory support and incentives from the government to promote the vegan food industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health Consciousness Driving Dietary Shifts
Rising rates of chronic diseases such as diabetes and heart disease in India are prompting consumers to seek healthier dietary options. Vegan fast food, perceived as lower in saturated fats and cholesterol, is increasingly chosen by health-conscious consumers seeking convenient yet nutritious alternatives.
Environmental and Ethical Considerations
Growing awareness of the environmental impact of animal agriculture and concerns about animal welfare are motivating Indian consumers to opt for vegan fast food. This aligns with a broader shift toward sustainability and cruelty-free food choices, especially among urban populations.
Influence of Younger Generations and Social Media
Millennials and Gen Z are more inclined toward veganism and flexitarian diets, driving demand for innovative vegan fast-food options. Social media and influencer marketing amplify this trend, making vegan fast food more aspirational and accessible.
Culinary Innovation and Local Flavor Integration
The integration of traditional Indian flavors and ingredients into vegan fast-food offerings is making plant-based options more appealing and relatable. This localization strategy helps overcome taste skepticism and broadens the market’s reach.
Expansion of Vegan Options in QSRs and Emphasis on Sustainability
Major quick-service restaurants are adding vegan items to their menus and adopting eco-friendly practices, such as compostable packaging and sustainable sourcing. This mainstreams vegan fast food and appeals to consumers who value convenience, health, and environmental responsibility.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Vegan Fast-Food Market?
What factors are driving the growth of the India Vegan Fast-Food Market?
What are the key segments within the India Vegan Fast-Food Market?
What are some challenges faced by the India Vegan Fast-Food Market?
Who are the major players in the India Vegan Fast-Food Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Meat & Seafood Alternatives
- 1.2.2 Creamer
- 1.2.3 Ice Cream and Frozen Novelties
- 1.2.4 Yogurt
- 1.2.5 Cheese
- 1.2.6 Butter
- 1.2.7 Meals
- 1.2.8 Protein Bars
- 1.2.9 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 393.78 million → 2032: USD 800.39 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Vegan Fast Food Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Vegan Fast Food Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Vegan Fast Food Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Vegan Fast Food Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Vegan Fast Food Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Vegan Fast Food Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Vegan Fast Food Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Vegan Fast Food Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 393.78 million → 2032: USD 800.39 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Vegan Fast Food Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Meat & Seafood Alternatives
- 12.3.7.2 Creamer
- 12.3.7.3 Ice Cream and Frozen Novelties
- 12.3.7.4 Yogurt
- 12.3.7.5 Cheese
- 12.3.7.6 Butter
- 12.3.7.7 Meals
- 12.3.7.8 Protein Bars
- 12.3.7.9 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 India Vegan Fast Food Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Vegan Fast Food Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Vegan Fast Food Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amy’s Kitchen
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Upfield B.V.
- 17.4 Johars Group
- 17.5 One Good (Goodmylk)
- 17.6 Rakyan Beverages
- 17.7 Hebei Yangyuan Zhihui Beverage Co. Ltd.
- 17.8 Namaste Foods
- 17.9 Urban Platter
- 17.10 Vezlay Foods
- 17.11 GoodDot
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

