
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Indonesia K-Beauty Product Market Size 2023 | USD 86.29 million |
| Indonesia K-Beauty Product Market, CAGR | 7.30%. |
| Indonesia K-Beauty Product Market Size 2032 | USD 162.95 million |
Market Overview
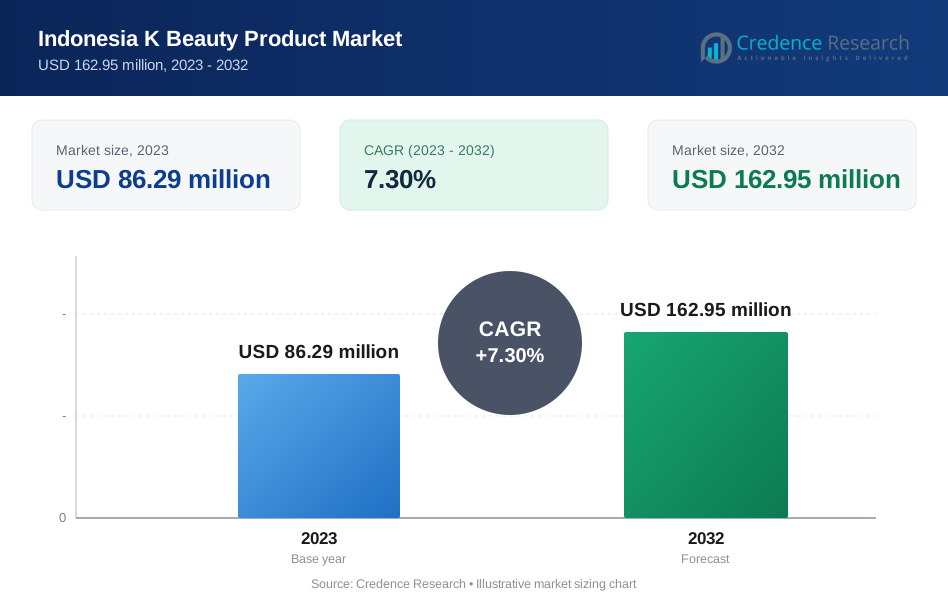
The Indonesia K-Beauty Product Market is projected to grow from USD 86.29 million in 2023 to an estimated USD 162.95 million by 2032, with a compound annual growth rate (CAGR) of 7.30% from 2024 to 2032. This robust growth is driven by increasing consumer awareness of skincare benefits, the rising influence of K-beauty trends through social media, and the expanding middle-class population with higher disposable incomes.
Key market drivers include the strong cultural affinity for Korean beauty standards, the proliferation of digital marketing and e-commerce platforms, and the growing demand for natural and organic beauty solutions. Trends such as the integration of advanced skincare technologies, personalized beauty routines, and sustainable packaging are shaping the market landscape. Additionally, collaborations between Korean beauty brands and local Indonesian retailers are enhancing product accessibility and consumer trust, fostering a favorable environment for market growth.
Geographically, major urban centers like Jakarta, Surabaya, and Bali are the primary hubs for K-beauty product consumption, driven by higher income levels and greater exposure to international beauty trends. These regions exhibit the highest adoption rates due to the presence of specialty stores, beauty salons, and robust online retail infrastructure. Key players in the Indonesia K-Beauty Product Market include renowned Korean brands such as Innisfree, Laneige, and Etude House, alongside emerging local brands that are leveraging unique formulations and effective marketing strategies to capture market share. The competitive landscape is characterized by continuous innovation, strategic partnerships, and a focus on enhancing the consumer experience to sustain growth in this dynamic market.
Market Insights
- The market is projected to grow from USD 86.29 million in 2023 to USD 162.95 million by 2032, with a CAGR of 7.30% from 2024 to 2032.
- The growing influence of Korean culture, including K-dramas and K-pop, significantly drives the demand for K-beauty products in Indonesia.
- Increasing disposable income and a rising middle-class population are fueling consumer demand for premium K-beauty products.
- Continuous product innovation, such as multi-functional products and natural ingredients, is a key driver in the market’s expansion.
- Strict regulatory requirements and high compliance costs for foreign brands can be a barrier to entry for new players.
- Urban centers like Jakarta, Surabaya, and Bali are the primary hubs for K-beauty consumption, benefiting from better exposure to global trends and higher income levels.
- The rise of online shopping platforms and digital marketing strategies is transforming how K-beauty products reach Indonesian consumers, particularly among younger, tech-savvy demographics.
Market Drivers
Cultural Influence and Popularity of Korean Wave (Hallyu)
The rising influence of Korean culture, known as Hallyu, plays a pivotal role in driving the demand for K-beauty products in Indonesia. Popular K-dramas, K-pop idols, and Korean celebrities significantly influence consumer behavior, especially among younger demographics. For instance, a survey indicated that around 62% of Indonesian respondents recognize the popularity of Korean beauty in their country, showcasing a strong cultural alignment with Korean entertainment and aesthetics. This influence is further amplified through social media platforms where local influencers merge K-beauty styles with traditional Indonesian beauty practices, enhancing consumer interest in K-beauty products. As Indonesian consumers associate these products with the flawless appearances of their favorite stars, a strong demand for similar beauty regimens emerges. The endorsement of K-beauty brands by celebrities on platforms like Instagram and TikTok creates a ripple effect on purchasing decisions, making these products highly sought after. As more Indonesians embrace Korean culture and its beauty standards, the market for K-beauty products continues to thrive, reflecting a broader trend of cultural exchange that enriches both consumer experiences and market dynamics.
Innovation in Product Offerings and Multi-functionality
Innovation is at the core of the K-beauty industry, attracting Indonesian consumers with advanced formulations and multi-functional products. K-beauty brands consistently introduce cutting-edge solutions that cater to diverse skin types and needs. For example, snail mucin-based skincare and cushion foundations have gained popularity due to their multifunctionality and effectiveness. Local brands are also adapting these innovations by incorporating trendy ingredients that resonate with Indonesian consumers. The emphasis on multi-functional products aligns well with the fast-paced lifestyles of many Indonesians who seek efficiency in their beauty routines. Additionally, these innovations enhance product efficacy while catering to the value-for-money preference prevalent among the Indonesian middle class. As consumers increasingly seek out products that deliver multiple benefits-such as hydration, sun protection, and coverage-K-beauty brands are well-positioned to meet these demands. This focus on innovation not only drives market growth but also fosters a competitive landscape where brands continuously strive to offer unique solutions that appeal to the evolving preferences of Indonesian consumers.
Shift Toward Natural, Sustainable, and Cruelty-Free Products
The growing awareness of sustainable and ethical practices among Indonesian consumers has significantly influenced the K-beauty market. Many consumers now prioritize products featuring natural ingredients, eco-friendly packaging, and adherence to cruelty-free production standards. Brands such as Innisfree and Laneige effectively meet these demands by emphasizing their commitment to sustainability through responsibly sourced ingredients and environmentally conscious practices. For instance, Innisfree’s use of Jeju Island’s natural resources not only highlights its dedication to purity but also resonates deeply with environmentally conscious consumers in Indonesia. This shift in consumer preference is crucial as it reflects a broader trend toward ethical consumption choices among younger demographics who are increasingly vocal about their values. The emphasis on natural extracts and skin-friendly formulations aligns perfectly with this growing demand for transparency and responsibility in beauty products. As more Indonesian consumers seek out sustainable options that align with their values, K-beauty brands that prioritize ethical practices are likely to see continued support from this conscientious audience, bolstering their growth trajectory in the competitive beauty market.
Expansion of E-commerce and Digital Marketing
E-commerce platforms and digital marketing strategies have revolutionized how K-beauty products reach Indonesian consumers. With increasing internet penetration and smartphone usage, a larger segment of the population can now access a wide range of K-beauty products online. Major e-commerce giants like Tokopedia, Shopee, and Lazada have dedicated sections for beauty products, often featuring attractive discounts and exclusive deals that entice consumers to explore K-beauty offerings. Furthermore, social media platforms such as Instagram, TikTok, and YouTube serve as powerful marketing tools that enable brands to engage directly with their target audience through tutorials, reviews, and influencer endorsements. For instance, many beauty influencers showcase their favorite K-beauty products through engaging content that resonates with young audiences seeking authentic recommendations. This seamless integration of digital channels not only boosts consumer awareness but also enhances purchase convenience by allowing customers to shop from the comfort of their homes. As online shopping becomes increasingly popular among Indonesian consumers, this digital transformation is propelling the growth of the K-beauty market while fostering a vibrant community around beauty trends and innovations.
Market Trends
Rising Popularity of Minimalist Skincare Regimens
In recent years, Indonesian consumers have embraced minimalist skincare routines, moving away from the elaborate 10-step regimens traditionally associated with K-beauty. This shift reflects a preference for efficiency and simplicity, particularly among urban millennials and Gen Z consumers. For instance, a survey revealed that Gen Z female respondents typically use around five products in their morning skincare routines, which include essentials like facial wash, toner, moisturizer, sunscreen, and serum. This inclination towards fewer products aligns with the rise of skinimalism, where multifunctional products are favored for their ability to deliver multiple benefits. K-beauty brands have responded by introducing innovative offerings such as BB creams that combine skincare with sun protection and hybrid serums that serve as both moisturizers and primers. This trend resonates with the fast-paced lifestyles of Indonesian consumers while maintaining the high efficacy and innovation for which K-beauty is known.
Increased Focus on Customization and Skin-Specific Solutions
As Indonesian consumers become more knowledgeable about skincare, there is a growing demand for products tailored to specific skin concerns and types. Many K-beauty brands now offer personalized solutions for common issues in Indonesia, such as acne and hyperpigmentation. For example, targeted formulations featuring effective ingredients like niacinamide and centella asiatica have gained popularity due to their efficacy in addressing these concerns. A significant portion of consumers now seeks customizable skincare routines that cater to individual needs, enhancing their overall experience. Brands that offer these tailored solutions not only drive consumer loyalty but also foster deeper engagement by empowering users to take control of their skincare journeys. This trend underscores the importance of understanding local skin issues and preferences, allowing brands to build stronger connections with their audience.
Preference for Clean, Sustainable, and Cruelty-Free Beauty
Sustainability and ethical practices have become essential in consumer decision-making within the Indonesian K-beauty market. With increased awareness of environmental issues, many Indonesian consumers actively seek products that are eco-friendly, sustainably packaged, and cruelty-free. Brands like Innisfree have gained traction by highlighting their commitment to sustainable sourcing and environmentally responsible initiatives. For instance, Innisfree’s focus on using natural ingredients and recyclable packaging resonates with health-conscious consumers looking for clean beauty options. Additionally, the trend towards mindful consumption is evident as more individuals prioritize products free from harmful chemicals. This shift not only reflects a broader movement towards sustainability but also enhances brand loyalty among consumers who value ethical practices. As a result, K-beauty brands that align with these values are likely to see continued growth in Indonesia's evolving beauty landscape.
Growing Influence of Digital Marketing and Social Commerce
The digital transformation of retail and marketing has significantly shaped trends in the Indonesian K-beauty market. Social media platforms such as Instagram, TikTok, and YouTube are central to how K-beauty brands connect with consumers. Influencer marketing has become a key strategy for brands to demonstrate product effectiveness through reviews and tutorial videos. For instance, many brands utilize livestreams to engage audiences in real time, showcasing product benefits while fostering a sense of community among consumers. Additionally, social commerce-where products are sold directly through social media-has gained momentum in Indonesia. This seamless shopping experience enhances brand visibility while allowing consumers to interact with brands more personally. As digital engagement continues to grow, K-beauty brands that leverage these platforms effectively will be better positioned to capture the attention of Indonesian consumers who increasingly rely on online channels for their beauty purchases.
Market Challenges
Intense Competition and Price Sensitivity
One of the primary challenges facing the Indonesia K Beauty Product Market is the intense competition both from local brands and international players. While K-beauty products are highly popular in Indonesia, local brands are increasingly offering similar products at lower prices, often with formulations that cater to the specific needs of Indonesian consumers. This price sensitivity is prevalent, particularly in the middle-class segment, where affordability is a key consideration in purchasing decisions. K-beauty brands must strike a delicate balance between maintaining their premium image and meeting the cost expectations of Indonesian consumers. The influx of affordable alternatives can make it difficult for established K-beauty brands to maintain market share unless they continue to innovate and offer compelling value propositions.
Regulatory Hurdles and Consumer Awareness
Another challenge in the Indonesian K-beauty market is navigating the regulatory landscape and ensuring consumer trust. Indonesia's stringent regulatory environment for cosmetic and skincare products, particularly regarding ingredients and claims, can be difficult for foreign brands to comply with. Ensuring that products meet local standards and are registered with the National Agency of Drug and Food Control (BPOM) is essential but can be time-consuming and costly. Additionally, while K-beauty products are becoming increasingly popular, many consumers in Indonesia still lack full awareness of the benefits and proper usage of these products. Misconceptions about ingredients and efficacy can limit the widespread adoption of K-beauty, especially in rural areas where education on skincare is less developed. Brands must invest in consumer education and brand-building to overcome these hurdles and expand their market reach.
Market Opportunities
Expanding Middle-Class Consumer Base
Indonesia’s rapidly growing middle class presents a significant opportunity for the K-beauty product market. As disposable incomes rise, particularly in urban areas such as Jakarta and Surabaya, consumers are increasingly seeking premium beauty products that promise high efficacy and innovative solutions. For instance, the middle-class population in Indonesia reached approximately 57.33 million people in 2019, but this number has significantly declined to about 47.85 million by 2024, indicating a loss of nearly 9.5 million individuals from this demographic over a five-year period. This shift underscores a critical opportunity for K-beauty brands to target the remaining middle-class consumers who are eager to invest in skincare regimens and self-care routines. The increasing number of young, beauty-conscious individuals in Indonesia is likely to fuel demand for Korean beauty products, known for their cutting-edge formulations and appeal to the latest beauty trends. By offering customized, affordable, and high-quality products tailored to the needs of this evolving demographic, K-beauty brands can effectively tap into the expanding market and establish a strong foothold in Indonesia's beauty landscape.
Growth of E-commerce and Digital Engagement
The ongoing expansion of e-commerce platforms and digital engagement in Indonesia offers a compelling opportunity for K-beauty brands to reach a broader audience. With the widespread use of smartphones and high internet penetration, Indonesian consumers are increasingly shopping online for beauty products. E-commerce platforms such as Tokopedia, Lazada, and Shopee have transformed the retail landscape, making it easier for consumers to access a variety of products from the comfort of their homes. This trend is supported by rising domestic travel and discretionary spending on entertainment since 2019, indicating a growing willingness among consumers to invest in personal care and beauty products. Additionally, digital marketing strategies like influencer partnerships, social media campaigns, and live-streamed product launches allow brands to connect with Indonesia’s tech-savvy youth demographic effectively. By leveraging these e-commerce channels and engaging with consumers through innovative digital strategies, K-beauty brands can accelerate their market penetration and strengthen their presence in Indonesia’s dynamic beauty market.
Market Segmentation Analysis
By Type
In the Indonesia K-beauty market, sheet masks are highly popular due to their convenience and immediate results, offering targeted solutions for hydration, brightening, and anti-aging. Cleansers, including both foam and oil-based formulations, are gaining popularity for their gentle yet effective cleansing, which removes impurities while preserving the skin’s natural moisture. Moisturizers, such as creams, serums, and gels, are in high demand for their ability to provide deep hydration and maintain the skin barrier, with lightweight and non-comedogenic options being preferred in Indonesia’s humid climate. Additionally, the "others" category, which includes serums, sunscreens, exfoliators, and treatment masks, continues to grow, with products offering multiple skincare benefits in a single formulation becoming increasingly popular to address concerns like acne, pigmentation, and aging.
By Application
The application of K-beauty products in Indonesia spans multiple sectors. The beauty business segment, which includes professional skincare treatments in salons and spas, plays a significant role, with beauty professionals recommending high-performance products for both immediate and long-term benefits. Personal use remains the largest segment, as increasing consumer awareness of Korean skincare routines drives individuals to incorporate these products into their daily self-care routines to address specific skin concerns. Additionally, the others segment covers institutional and commercial uses, such as for gift sets, promotional events, and business-to-business sales.
Segments
Based on Type
- Sheet Masks
- Cleansers
- Moisturizers
- Others
Based on Application
- Beauty Business
- Personal
- Others
Based on End User
- Male
- Female
- Children and Teenage
Based on Distribution Channel
- Online Retail
- Supermarket/Hypermarket
- Specialty/Monobrand Stores
Based on Region
- Java
- Bali and Sumatra
- Other Islands
Regional Analysis
Java (60%)
Java, particularly the urban centers such as Jakarta, Surabaya, Bandung, and Yogyakarta, dominates the Indonesia K Beauty Product Market. The region accounts for approximately 60% of the market share due to its high population density, higher disposable incomes, and a large concentration of young, beauty-conscious consumers. Jakarta, as the capital city, is the primary hub for K-beauty products, with a thriving e-commerce ecosystem and numerous retail outlets offering a variety of Korean skincare and cosmetics. This region also benefits from greater exposure to global beauty trends and a high concentration of influencers who promote K-beauty through social media platforms such as Instagram, YouTube, and TikTok.
Bali (15%)
Bali, with its status as a major tourist destination, accounts for approximately 15% of the market share. The region’s demand for K-beauty products is driven not only by locals but also by international tourists seeking premium skincare solutions. Many high-end beauty salons, spas, and wellness centers in Bali offer Korean beauty treatments, further boosting the demand for K-beauty products. Additionally, the influx of expatriates and tourists from East Asia and other parts of the world familiar with K-beauty trends plays a significant role in sustaining demand for these products in the region.
Key players
- Able C & C Ltd
- Adwin Korea Corporation
- Amorepacific Corporation
- CLIO COSMETICS Co. Ltd
- Cosrx Inc
- LG H&H Co. Ltd. (LG Corporation)
- The Crème Shop Inc
- The Face Shop Inc
- Purederm
- Nykaa
- Nikkei Asia
Competitive Analysis
The Indonesia K Beauty Product Market is highly competitive, with established international and regional brands striving for dominance. Companies like Amorepacific Corporation, LG H&H, and Cosrx Inc. lead the market, leveraging their strong global presence, wide product portfolios, and innovative formulations. These brands benefit from established brand recognition and significant distribution networks, including retail partnerships and e-commerce channels. Emerging players like Nykaa and The Crème Shop Inc are capitalizing on the growing trend of online retail and targeted marketing through social media. Their ability to connect with the younger, tech-savvy consumer base in Indonesia gives them an edge in driving market share. Meanwhile, regional players such as Adwin Korea Corporation and The Face Shop Inc focus on catering to local preferences, offering skincare products with natural ingredients tailored to the Indonesian climate. This diverse mix of global and regional players creates a dynamic competitive landscape in the market.
Recent Developments
- In April 2024, Able C&C expanded its partnership with Japan’s Daiso, launching an exclusive makeup line called Pure Candy. This line features three color cosmetics products-blusher, lip tint, and lip balm-priced at approximately USD 2.19 each. The products are inspired by vibrant candy colors and aim to provide hydration along with color.
- In November 2023, Amorepacific's nutricosmetics brand, Vital Beautie, introduced a new retinol-based dietary supplement designed to be safe for sensitive individuals. This launch emphasizes the company's commitment to innovative skincare solutions that cater to diverse consumer needs.
- In June 2024, LG H&H announced the launch of a new skincare line under its popular brand The Face Shop, specifically targeting the Indonesian market. This line focuses on natural ingredients and aims to meet the rising demand for effective skincare solutions among local consumers.
- In March 2024, The Crème Shop launched a new collection of vegan skincare products in Indonesia, aligning with the growing trend towards cruelty-free and environmentally friendly beauty options. This collection has been well-received by Indonesian consumers who prioritize ethical beauty choices.
Market Concentration and Characteristics
The Indonesia K Beauty Product Market exhibits a moderate level of market concentration, with a few dominant global players such as Amorepacific Corporation, LG H&H Co. Ltd., and Cosrx Inc. leading the market, while several smaller and regional players, including The Face Shop Inc. and Purederm, also maintain a significant presence. These major brands dominate the market by leveraging strong brand recognition, extensive product portfolios, and well-established distribution channels. However, the market is characterized by high competition, as both international and local brands increasingly cater to the growing demand for K-beauty products through online retail, social media marketing, and personalized skincare solutions. The rise of e-commerce and social commerce, particularly among younger, tech-savvy consumers, has opened opportunities for both established players and new entrants to capture market share, making the market dynamic and highly competitive.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Indonesia K Beauty Product Market is expected to grow significantly, driven by rising disposable incomes and growing consumer awareness of Korean beauty trends. The market is projected to reach USD 162.95 million by 2032, with a robust CAGR of 7.30% from 2024 to 2032.
- E-commerce platforms will continue to play a crucial role in market growth, offering greater accessibility to K-beauty products. The convenience of online shopping and digital promotions will enhance product visibility across Indonesia's diverse regions.
- Consumers are expected to prioritize sustainable and cruelty-free K-beauty products, leading brands to adopt eco-friendly packaging and ethical sourcing. This shift will align with the global trend toward mindful consumption and environmental responsibility
- The demand for personalized skincare will rise, with brands offering customized products tailored to specific skin concerns. As consumers seek products that meet their unique needs, personalization will become a key selling point.
- The male skincare segment will continue to expand as more Indonesian men embrace grooming and skincare routines. K-beauty brands will increasingly target male consumers with tailored product lines designed for their specific skincare needs.
- Korean beauty products will gain more traction in secondary cities and rural areas of Indonesia. As internet penetration increases, more consumers outside major urban centers will access and purchase K-beauty products online.
- K-beauty brands will continue to innovate, introducing advanced skincare formulations that incorporate cutting-edge technologies. Consumers will benefit from more effective products designed to address a range of skin issues, from acne to aging.
- Social media will remain a powerful tool for promoting K-beauty products, with influencers and beauty vloggers shaping consumer preferences. Brands will increasingly collaborate with digital influencers to engage Indonesia's younger demographic.
- Consumers will increasingly seek multi-functional products that combine several skincare steps into one. K-beauty brands will respond by offering convenient and time-saving solutions, such as BB creams with SPF and anti-aging benefits.
- While online retail will continue to dominate, the expansion of K-beauty stores and pop-up shops in major cities will increase. These physical stores will provide consumers with the opportunity to experience products firsthand, strengthening brand loyalty and trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Cultural Influence and Korean Wave (Hallyu)
The popularity of Korean culture, including K-dramas and K-pop, strongly influences Indonesian consumers, especially younger demographics, driving demand for K-beauty products that promise the flawless looks of Korean celebrities.
Expansion of E-commerce and Digital Marketing
The rapid growth of e-commerce platforms and digital marketing in Indonesia has made K-beauty products more accessible, allowing brands to reach a wider audience and engage consumers through influencer partnerships and social media campaigns.
Innovation and Multi-functional Product Offerings
K-beauty brands are known for continuous innovation, introducing advanced formulations and multi-functional products that appeal to Indonesian consumers seeking efficiency and value in their skincare routines.
Shift Toward Natural, Sustainable, and Cruelty-Free Products
Increasing consumer awareness of sustainability and ethical practices is driving demand for K-beauty products with natural ingredients, eco-friendly packaging, and cruelty-free claims, aligning with the values of health-conscious and environmentally aware Indonesians.
Rising Disposable Income and Expanding Middle Class
Growth in Indonesia's middle-class population and rising disposable incomes, particularly in urban centers, are enabling more consumers to purchase premium K-beauty products, fueling overall market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Indonesia K-Beauty Product Market in 2023 and 2032?
What factors are driving the growth of the Indonesia K-Beauty Product Market?
Which regions in Indonesia are leading the K-Beauty Product consumption?
What trends are shaping the Indonesia K-Beauty Product Market?
Who are the key players in the Indonesia K-Beauty Product Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sheet Masks
- 1.2.2 Cleansers
- 1.2.3 Moisturizers
- 1.2.4 Others
- 1.3 By End User
- 1.3.1 Male
- 1.3.2 Female
- 1.3.3 Children and Teenage
- 1.4 By Application
- 1.4.1 Beauty Business
- 1.4.2 Personal
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 86.29 million → 2032: USD 162.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Indonesia K Beauty Product Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Indonesia K Beauty Product Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Indonesia K Beauty Product Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Indonesia K Beauty Product Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Indonesia K Beauty Product Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Indonesia K Beauty Product Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Indonesia K Beauty Product Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Indonesia K Beauty Product Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 86.29 million → 2032: USD 162.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Indonesia K Beauty Product Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sheet Masks
- 12.3.7.2 Cleansers
- 12.3.7.3 Moisturizers
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Male
- 12.4.7.2 Female
- 12.4.7.3 Children and Teenage
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Beauty Business
- 12.5.7.2 Personal
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Indonesia K Beauty Product End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Indonesia K Beauty Product Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Indonesia K Beauty Product Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Indonesia K Beauty Product Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amorepacific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG H&H Co. Ltd.
- 18.4 Cosrx Inc
- 18.5 Able C & C Ltd
- 18.6 Adwin Korea Corporation
- 18.7 CLIO COSMETICS Co. Ltd
- 18.8 The Face Shop Inc
- 18.9 The Crème Shop Inc
- 18.10 Purederm
- 18.11 Nykaa
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

