
Market Overview:
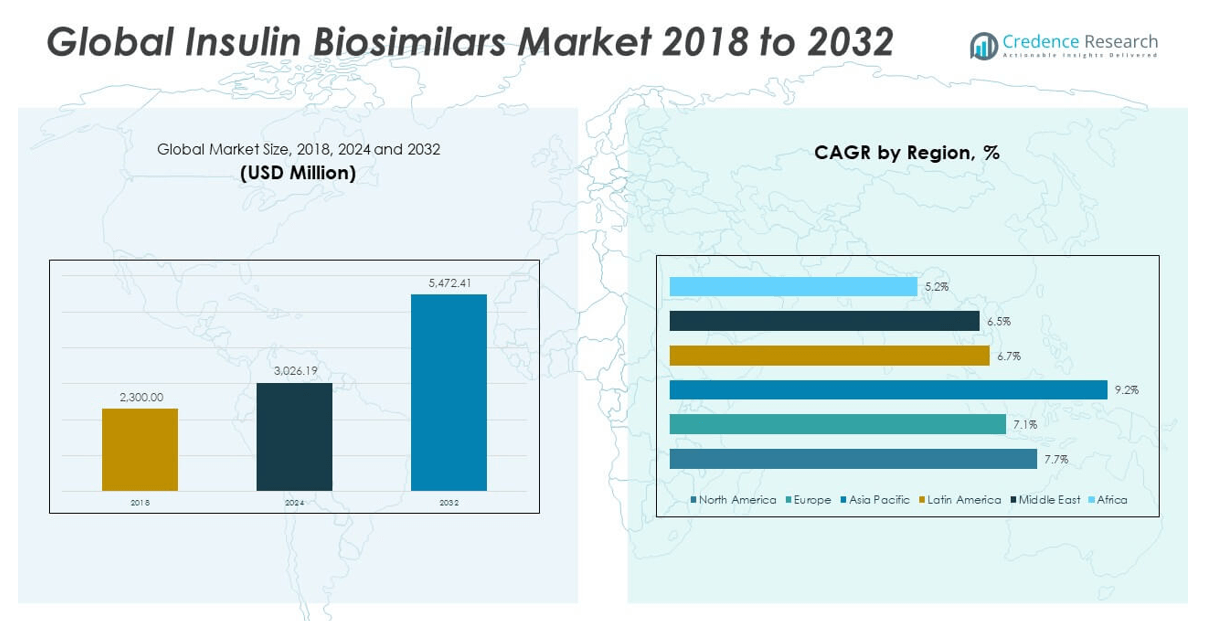
The Global Insulin Biosimilars Market size was valued at USD 2,300.00 million in 2018 to USD 3,026.19 million in 2024 and is anticipated to reach USD 5,472.41 million by 2032, at a CAGR of 7.72% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Insulin Biosimilars Market Size 2024 | USD 3,026.19 million |
| Insulin Biosimilars Market, CAGR | 7.72% |
| Insulin Biosimilars Market Size 2032 | USD 5,472.41 million |
The market is gaining traction due to the rising prevalence of diabetes, growing geriatric population, and increasing demand for cost-effective treatment alternatives. Healthcare systems and payers actively promote biosimilars to reduce expenditure while maintaining therapeutic efficacy. Patent expirations of blockbuster insulin brands open doors for biosimilar entries, and regulatory support from agencies such as the FDA and EMA further accelerates market adoption. Manufacturers invest in expanding production and improving formulations to enhance affordability and accessibility.
Geographically, North America leads the insulin biosimilars market due to high diabetes incidence and a robust biosimilar approval framework in the United States. Europe follows closely, supported by favorable reimbursement policies and widespread physician acceptance. The Asia Pacific region is emerging rapidly, driven by rising healthcare demand in China and India, where governments encourage biosimilar adoption to increase affordability. Latin America and the Middle East & Africa show gradual growth, fueled by increasing awareness and improving healthcare infrastructure.
Market Insights:
- The Global Insulin Biosimilars Market was valued at USD 3,026.19 million in 2024 and is projected to reach USD 5,472.41 million by 2032, growing at a CAGR of 7.72%.
- Rising diabetes prevalence and increasing insulin dependency in aging populations drive global demand for cost-effective biosimilar insulin.
- Expiration of branded insulin patents allows new biosimilar entries, encouraging competitive pricing and broader accessibility.
- Limited physician and patient trust in biosimilar interchangeability restricts faster adoption in some developed markets.
- Regulatory complexity and high manufacturing standards create barriers for smaller players entering the biosimilar insulin segment.
- North America leads the market due to established regulatory frameworks and high diagnosis rates, while Asia Pacific emerges rapidly with growing diabetic populations and public healthcare support.
- Europe maintains strong market momentum through reimbursement policies favoring biosimilars and healthcare system alignment with cost-saving goals.
Market Drivers:
Rising Global Prevalence of Diabetes and Insulin Dependency among Aging Populations:
The Global Insulin Biosimilars Market benefits from the sharp rise in diabetes cases worldwide, driven by lifestyle changes, aging populations, and increasing obesity rates. Millions of patients rely on insulin for effective glucose control. As the aging population expands, especially in developed and emerging economies, the number of insulin-dependent individuals grows significantly. This rising burden accelerates the need for cost-effective insulin therapies. Insulin biosimilars present a practical alternative to expensive branded options. It supports public health systems under pressure from chronic disease management costs. Governments and private insurers show growing support for biosimilar adoption. This shift directly supports volume growth and market penetration.
- For instance, Biocon Biologics reported that its insulin biosimilar portfolio treated over 300,000 patients globally by 2024, with a 25% year-over-year increase in biosimilar insulin prescriptions across emerging demographics.
Expanding Healthcare Access in Emerging Economies and Public Policy Support:
Emerging markets such as India, China, Brazil, and parts of Southeast Asia continue to invest in healthcare infrastructure. These countries also promote affordability in chronic disease care. The Global Insulin Biosimilars Market gains from these policy shifts favoring biosimilar entry and reimbursement coverage. National programs that expand access to essential medicines encourage biosimilar inclusion. It opens new revenue streams for biosimilar producers, especially local or regional manufacturers. Demand rises in parallel with improved diagnosis and treatment adherence. Governments actively promote bulk procurement of biosimilars to reduce fiscal burden. These factors make insulin biosimilars an integral part of diabetes care in resource-constrained regions.
Expiration of Key Patents and Growing Regulatory Streamlining for Biosimilars:
The market gains momentum from the expiration of patents on several leading branded insulin formulations. This opens pathways for biosimilar manufacturers to enter with competitive products. Regulatory authorities in key markets including the U.S. and Europe have streamlined biosimilar approval pathways. The Global Insulin Biosimilars Market benefits from such aligned regulatory frameworks that enable faster market access. It boosts investor confidence and reduces development risks for biosimilar players. Competitive pricing strategies further accelerate acceptance among payers. This environment supports strong biosimilar pipelines and accelerates time-to-market. It encourages new players to compete across global and regional levels.
- For instance, The U.S. FDA and EMA have adopted streamlined biosimilar approval frameworks to decrease approval times from approximately 10 years to under 5 years in many cases.
Cost Efficiency for Payers and Growing Preference among Healthcare Providers:
Insulin biosimilars offer substantial cost savings without compromising clinical outcomes. Hospitals, clinics, and healthcare systems recognize the value in switching patients to biosimilar therapies. Payers such as insurance providers and government-funded healthcare programs push for wider biosimilar adoption. The Global Insulin Biosimilars Market benefits from this payer-driven shift, which directly impacts prescribing behaviors. It enables broader access across socioeconomic groups. Increased physician awareness and education programs help strengthen market trust. Procurement agencies increasingly prioritize biosimilars in tenders and formulary listings. These cost efficiencies reshape procurement decisions in both developed and developing markets.
Market Trends:
Increasing Strategic Collaborations between Biosimilar Developers and Regional Distributors:
Manufacturers seek strategic collaborations to extend geographic reach and regulatory alignment. Global players partner with regional distributors and pharma firms to navigate local licensing, logistics, and compliance challenges. The Global Insulin Biosimilars Market sees frequent alliances aimed at faster rollout and reduced market entry risks. Such partnerships often involve co-marketing or co-manufacturing agreements. It helps biosimilar developers tap into established distribution networks. These collaborations improve affordability and speed up product access in underserved regions. Stakeholders jointly manage supply chain and post-market surveillance. This cooperative trend accelerates market saturation in new territories.
- For instance, Sandoz, a Novartis division, entered a partnership with Medison Pharma in 2024, expanding distribution of its insulin biosimilars to over 15 countries in the Middle East and Africa, enhancing supply chain efficiency and regulatory compliance.
Growing Adoption of Digital Health Tools to Support Insulin Delivery and Monitoring:
Digital health tools and connected devices are transforming insulin delivery and treatment adherence. Smart insulin pens, glucose monitors, and mobile apps support patients using biosimilar insulin. The Global Insulin Biosimilars Market integrates with these technologies to improve therapy outcomes. It encourages remote monitoring and better disease control. Real-time dosage tracking boosts patient engagement and safety. Tech-enabled adherence solutions are gaining traction across healthcare providers. These tools complement biosimilar insulin use in both wearable and handheld formats. The synergy between digital health and biosimilars helps improve compliance and lower long-term treatment costs.
- For instance, Eli Lilly’s partnership with Livongo enabled users of biosimilar insulin to engage with smart pens and glucose monitoring apps in 2024, reporting a 15% improvement in patient adherence and glucose level stabilization.
Pharmaceutical Investments in Low-Cost Manufacturing and Cold Chain Expansion:
Biosimilar producers invest heavily in scalable, cost-effective manufacturing technologies. Modern production sites across Asia and Latin America reduce per-unit costs and enhance competitive positioning. The Global Insulin Biosimilars Market benefits from these supply chain optimizations. It supports high-volume distribution across global markets. Cold chain logistics capacity is expanding to support temperature-sensitive insulin biosimilars. Better storage and transport systems ensure product stability and reduce wastage. These infrastructure improvements enable efficient last-mile delivery. Efficient logistics also facilitate hospital and retail pharmacy replenishment.
Emphasis on Patient Education and Clinical Acceptance through Real-World Evidence:
Efforts to build physician and patient trust remain a vital trend in the market. Stakeholders deploy educational campaigns to address concerns around efficacy and interchangeability. The Global Insulin Biosimilars Market relies on clinical trials and real-world data to demonstrate comparable safety. Physicians increasingly acknowledge these findings and shift prescriptions accordingly. Advocacy groups and healthcare institutions support awareness programs. Patient groups respond positively to therapy options that reduce costs. The focus on clinical validation strengthens confidence in switching from originators. Market trust is improving across major health systems.
Market Challenges Analysis:
Limited Patient and Physician Trust in Biosimilar Interchangeability and Efficacy:
Trust in biosimilars remains a concern, particularly regarding interchangeability with branded insulin. Some physicians remain hesitant to switch stable patients from originators to biosimilars. This resistance slows biosimilar penetration in high-value markets. The Global Insulin Biosimilars Market faces delays in formulary inclusion and substitution protocols. Misconceptions about efficacy and safety create barriers to adoption. Patient groups also express reluctance without clear education. Marketing efforts from originator companies often reinforce doubts. These psychological and behavioral barriers persist despite scientific equivalence.
Complex Regulatory and Manufacturing Requirements Impact Market Entry Speed:
Insulin biosimilars involve complex development and manufacturing processes compared to chemical generics. Companies must meet stringent analytical, clinical, and pharmacovigilance standards. It raises entry barriers, especially for small and mid-sized firms. The Global Insulin Biosimilars Market experiences bottlenecks due to lengthy approval timelines in some countries. Harmonizing requirements across jurisdictions remains a challenge. Cold chain maintenance and batch consistency add operational pressure. Manufacturers must also manage scale-up costs effectively. These hurdles limit the number of qualified competitors.
Market Opportunities:
Expansion Potential in Low-Income and Underserved Diabetic Populations Worldwide:
Emerging markets hold significant growth potential due to large undiagnosed diabetic populations. National governments are expanding access to affordable care. The Global Insulin Biosimilars Market can address demand in underserved areas where branded insulin is unaffordable. Local production partnerships and tiered pricing models create entry pathways. Mobile health initiatives also support biosimilar insulin delivery in remote settings. Manufacturers can secure long-term contracts through public procurement schemes.
Pipeline Growth through Next-Generation Insulin Biosimilar Innovation:
Companies invest in developing biosimilars for new-generation insulin analogs with better pharmacokinetics. These innovations increase switching potential across patient types. The Global Insulin Biosimilars Market can grow by introducing value-added biosimilars that offer superior patient experience. Dual-action and ultra-long-acting formulations are under development. These options support lifecycle extension and competitive differentiation.
Market Segmentation Analysis:
By Type
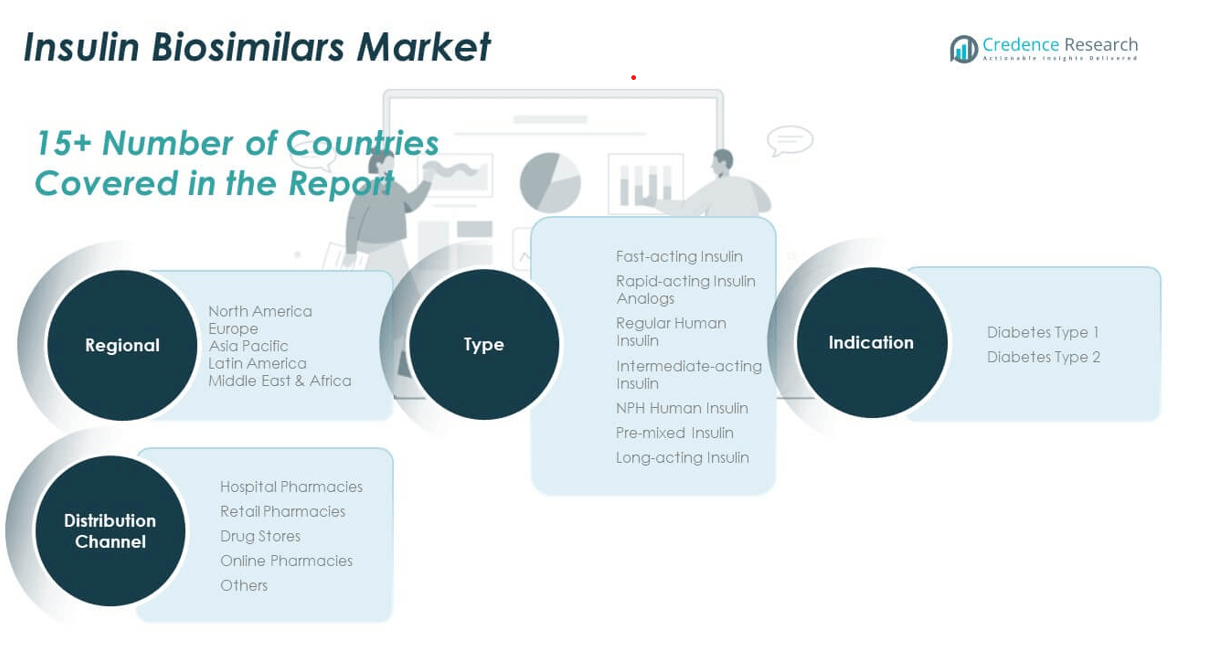
The Global Insulin Biosimilars Market includes fast-acting insulin, rapid-acting insulin analogs, regular human insulin, intermediate-acting insulin, NPH human insulin, pre-mixed insulin, and long-acting insulin. Long-acting insulin holds the largest share due to its extended duration of action and reduced injection frequency, supporting better patient adherence. Rapid-acting and fast-acting variants are widely used for postprandial glucose control. Regular and NPH human insulin continue to serve cost-sensitive markets. Intermediate-acting and pre-mixed formulations remain preferred among patients requiring fewer daily doses and simplified management.
- For instance, Eli Lilly’s Rezvoglar (insulin glargine-aglr), launched in the U.S. , complements its rapid-acting insulin products in supporting postprandial glucose control. While specific unit volumes are confidential, Eli Lilly reported distribution to over 120,000 pharmacy outlets nationwide within the first six months post-launch, indicating broad adoption in this segment.
By Indication
The market is segmented into wearable devices and handheld devices. Wearable devices dominate due to rising adoption of insulin pumps and smart systems that allow continuous insulin delivery with minimal intervention. These devices improve treatment accuracy and patient compliance. Handheld devices remain essential for traditional insulin administration in hospitals, clinics, and home settings where simplicity and portability are required.
- For instance, Biocon Biologics, a major biosimilar insulin manufacturer, has supplied over 9.2 billion doses globally of regular human insulin and NPH insulin formulations, mainly targeting cost-sensitive markets in Asia and Africa.
By Distribution Channel
Distribution channels include hospital pharmacies, retail pharmacies, drug stores, online pharmacies, and others. Hospital pharmacies lead due to their centralized role in chronic disease management and prescription-based supply. Retail pharmacies follow closely, offering convenient access for outpatients. Drug stores and online pharmacies are expanding rapidly with rising consumer preference for direct access and delivery. The 'others' category includes specialized care centers and diabetes clinics that provide tailored solutions and advanced insulin management support. Each channel plays a distinct role in ensuring product availability and patient outreach.
Segmentation:
By Type
- Fast-acting Insulin
- Rapid-acting Insulin Analogs
- Regular Human Insulin
- Intermediate-acting Insulin
- NPH Human Insulin
- Pre-mixed Insulin
- Long-acting Insulin
By Indication
- Wearable Devices
- Handheld Devices
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Drug Stores
- Online Pharmacies
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Insulin Biosimilars Market size was valued at USD 814.20 million in 2018 to USD 1,057.94 million in 2024 and is anticipated to reach USD 1,910.43 million by 2032, at a CAGR of 7.7% during the forecast period. It accounted for approximately 34.96% of the global market share in 2024. The Global Insulin Biosimilars Market in this region is driven by a strong regulatory framework, high diabetes prevalence, and widespread adoption of biosimilar therapies. The U.S. leads the region due to favorable FDA guidelines, payer support, and rising healthcare expenditures. Market participants actively engage in public-private partnerships and clinical trials. Strong demand from healthcare providers and pharmacy benefit managers sustains market momentum. Insulin biosimilars continue to gain physician trust with increasing clinical evidence. Companies benefit from insurance coverage and government initiatives promoting cost-saving options.
Europe
The Europe Insulin Biosimilars Market size was valued at USD 704.95 million in 2018 to USD 896.58 million in 2024 and is anticipated to reach USD 1,544.60 million by 2032, at a CAGR of 7.1% during the forecast period. It represented around 29.62% of the global market share in 2024. The region remains a key growth area due to mature biosimilar regulation, widespread reimbursement systems, and policy-driven substitution. Countries such as Germany, France, and the UK lead adoption through national formularies and physician incentives. The European Medicines Agency has streamlined approval procedures for biosimilars, supporting faster entry. Growing pressure to reduce public healthcare costs encourages biosimilar uptake. Hospitals and clinics incorporate insulin biosimilars into treatment plans. Companies collaborate with national health systems for broader reach. The market continues to expand steadily across Western and Eastern Europe.
Asia Pacific
The Asia Pacific Insulin Biosimilars Market size was valued at USD 489.90 million in 2018 to USD 677.40 million in 2024 and is anticipated to reach USD 1,369.75 million by 2032, at a CAGR of 9.2% during the forecast period. It contributed approximately 22.37% to the global market in 2024. The Global Insulin Biosimilars Market in Asia Pacific is witnessing rapid growth due to expanding diabetic populations, government incentives, and strong domestic manufacturing capacity. China and India lead in volume demand, supported by public healthcare reforms and local production. Regional players focus on affordability, while international companies pursue joint ventures and licensing deals. Increasing awareness, diagnosis rates, and reimbursement coverage fuel demand. Health agencies prioritize affordable insulin access in rural and urban zones. Biosimilars are included in essential medicine lists in several countries. Regional supply chains and distribution networks are improving steadily.
Latin America
The Latin America Insulin Biosimilars Market size was valued at USD 145.36 million in 2018 to USD 189.41 million in 2024 and is anticipated to reach USD 317.78 million by 2032, at a CAGR of 6.7% during the forecast period. It accounted for 6.26% of the global market share in 2024. The region experiences growing demand driven by the increasing burden of type 2 diabetes and budget constraints in public healthcare systems. Countries like Brazil and Argentina lead regional uptake through national tenders and price-focused procurement. Biosimilar companies benefit from partnerships with regional pharmaceutical firms. Healthcare providers and pharmacies seek affordable alternatives amid pricing pressures. Regulatory agencies are gradually streamlining biosimilar approval pathways. Market growth remains moderate but steady, supported by awareness campaigns and insurance expansion. Demand centers on urban areas where healthcare access is improving.
Middle East
The Middle East Insulin Biosimilars Market size was valued at USD 97.98 million in 2018 to USD 121.63 million in 2024 and is anticipated to reach USD 200.87 million by 2032, at a CAGR of 6.5% during the forecast period. It captured 4.02% of the global market share in 2024. Market growth is supported by rising diabetes incidence, increasing healthcare expenditure, and government efforts to reduce treatment costs. The Gulf Cooperation Council countries show strong demand for biosimilars, with the UAE and Saudi Arabia leading adoption. Public health systems aim to improve access to essential medicines. Multinational companies target the region through distributor partnerships. Regulatory reforms are underway to ease biosimilar registration. Urban hospitals and clinics promote biosimilar use for cost-effective chronic care. Physician education and digital tools contribute to acceptance.
Africa
The Africa Insulin Biosimilars Market size was valued at USD 47.61 million in 2018 to USD 83.23 million in 2024 and is anticipated to reach USD 128.98 million by 2032, at a CAGR of 5.2% during the forecast period. It comprised about 2.75% of the global market share in 2024. The Global Insulin Biosimilars Market in Africa faces infrastructure limitations but shows potential in densely populated countries. Governments and NGOs focus on improving access to essential insulin therapies. South Africa and Egypt lead regional consumption, driven by donor funding and public procurement. Local production capacity remains limited, prompting reliance on imports. Biosimilars are increasingly seen as viable solutions for underserved populations. Price sensitivity and inconsistent reimbursement slow adoption rates. Awareness and diagnostic capabilities are improving gradually. Pilot programs and regional partnerships aim to enhance market presence.
Key Player Analysis:
- Eli Lilly and Company
- Sanofi SA
- BIOTON S.A.
- WOCKHARDT
- Julphar
- Biocon Ltd.
- Tonghua Dongbao
- Polfa Tarchomin S.A.
- Popular Pharmaceuticals Ltd
- SEDICO Co.
- Advanced Chemical Industries Limited
- Aristopharma Ltd.
- Denver Farma S.A.
Competitive Analysis:
The Global Insulin Biosimilars Market features a moderately consolidated landscape dominated by key players including Biocon Ltd., Eli Lilly and Company, Sanofi SA, and Wockhardt. It is marked by intense competition based on pricing, regulatory approvals, therapeutic equivalence, and geographic expansion. Companies invest in biosimilar development pipelines, regional partnerships, and production efficiency to strengthen their positions. Players focus on gaining regulatory approvals across high-growth markets such as Asia Pacific and Latin America. Strategic alliances with distributors and co-marketing agreements help extend reach. Product differentiation remains limited, making price and accessibility key competitive levers. Market leaders actively promote clinical equivalence through real-world data and education. The competitive environment encourages both innovation and affordability, driving broader patient access.
Recent Developments:
- In April 2025, Eli Lilly and Company launched Rezvoglar (insulin glargine-aglr), an insulin glargine biosimilar, in the United States. Rezvoglar is the second interchangeable insulin biosimilar approved by the FDA, designed to improve glycemic control in adult and pediatric patients with type 1 and type 2 diabetes. The product was introduced at a 78% discount to the reference product Lantus, enhancing patient access and affordability.
- In February 2025, Sanofi SA received FDA approval for Merilog (insulin-aspart-szjj), a rapid-acting insulin biosimilar to Novo Nordisk’s Novolog. Merilog represents the first insulin aspart biosimilar approved in the US and the third insulin biosimilar overall, improving options for glycemic control in both adult and pediatric diabetes patients. It is available in prefilled pen and multiple-dose vial formats.
Market Concentration & Characteristics:
The Global Insulin Biosimilars Market shows moderate concentration with a few dominant players and several regional entrants. It is characterized by high regulatory scrutiny, complex manufacturing requirements, and price-sensitive demand. Barriers to entry remain substantial due to biosimilar development costs and rigorous clinical validation. It exhibits volume-driven growth, supported by government policies and public health priorities. Market characteristics include high dependence on formulary access, payer influence, and therapeutic interchangeability. Companies must maintain consistency in quality, scalability, and global compliance to succeed.
Report Coverage:
The research report offers an in-depth analysis based on type, indication, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will grow steadily due to the increasing global diabetic population and preference for cost-effective therapies.
- Patent expirations of major branded insulin will continue to create opportunities for biosimilar developers.
- Regulatory harmonization across emerging economies will ease market entry for biosimilar manufacturers.
- Technological advancements in drug delivery devices will improve patient adherence to insulin biosimilars.
- Growing healthcare expenditure and payer pressure will push biosimilar inclusion in treatment plans.
- Expansion in public procurement programs will support volume growth in low- and middle-income countries.
- Strategic partnerships between global and regional players will enhance market penetration.
- Investments in local production facilities will reduce costs and improve distribution efficiency.
- Education campaigns will help address trust issues and increase physician acceptance of biosimilars.
- Biosimilar innovations targeting next-generation insulin analogs will create new differentiation opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Prevalence of Diabetes and Insulin Dependency
The increasing incidence of diabetes worldwide, particularly among aging populations, is driving demand for insulin therapies. As more patients require long-term insulin management, biosimilars offer a cost-effective alternative to branded products, supporting broader access and market growth.
Patent Expirations and Regulatory Streamlining
The expiration of patents on major branded insulin products has opened the market to biosimilar competition. Streamlined regulatory pathways in key markets like the US and Europe have reduced approval timelines, encouraging new entrants and accelerating the availability of biosimilar options.
Healthcare Cost Containment and Payer Support
Governments and insurance providers are actively promoting biosimilar insulin adoption to reduce healthcare expenditures. Favorable reimbursement policies and bulk procurement initiatives are increasing biosimilar uptake, especially in public health systems facing budget constraints.
Expansion of Healthcare Access in Emerging Markets
Emerging economies are investing in healthcare infrastructure and policies that support biosimilar entry and reimbursement. This is expanding access to affordable insulin therapies in regions with large, underserved diabetic populations, fueling market growth.
Technological Advancements in Insulin Delivery
The integration of biosimilar insulin with digital health tools, such as smart pens and wearable devices, is improving treatment adherence and outcomes. These innovations are making biosimilar insulin more attractive to both patients and healthcare providers, supporting market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Insulin Biosimilars Market?
What factors are driving the growth of the Global Insulin Biosimilars Market?
What are some challenges faced by the Global Insulin Biosimilars Market?
Who are the major players in the Global Insulin Biosimilars Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Fast-acting Insulin
- 1.2.2 Rapid-acting Insulin Analogs
- 1.2.3 Regular Human Insulin
- 1.2.4 Intermediate-acting Insulin
- 1.2.5 NPH Human Insulin
- 1.2.6 Pre-mixed Insulin
- 1.2.7 Long-acting Insulin
- 1.3 By Indication
- 1.3.1 Wearable Devices
- 1.3.2 Handheld Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,026.19 million → 2032: USD 5,472.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Insulin Biosimilars Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Insulin Biosimilars Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Insulin Biosimilars Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Insulin Biosimilars Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Insulin Biosimilars Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Insulin Biosimilars Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Insulin Biosimilars Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Insulin Biosimilars Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,026.19 million → 2032: USD 5,472.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Insulin Biosimilars Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fast-acting Insulin
- 12.3.7.2 Rapid-acting Insulin Analogs
- 12.3.7.3 Regular Human Insulin
- 12.3.7.4 Intermediate-acting Insulin
- 12.3.7.5 NPH Human Insulin
- 12.3.7.6 Pre-mixed Insulin
- 12.3.7.7 Long-acting Insulin
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wearable Devices
- 12.4.7.2 Handheld Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Insulin Biosimilars Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Insulin Biosimilars Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Insulin Biosimilars Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Eli Lilly and Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Sanofi SA
- 17.4 Biocon Ltd.
- 17.5 WOCKHARDT
- 17.6 BIOTON S.A.
- 17.7 Julphar
- 17.8 Tonghua Dongbao
- 17.9 Polfa Tarchomin S.A.
- 17.10 SEDICO Co.
- 17.11 Denver Farma S.A.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

