
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Integrated Enterprise Resource Planning (ERP) System Market Size 2024 | USD 71,454 million |
| Integrated Enterprise Resource Planning (ERP) System Market, CAGR | 14.9% |
| Integrated Enterprise Resource Planning (ERP) System Market Size 2032 | USD 217,063.49 million |
Market Overview
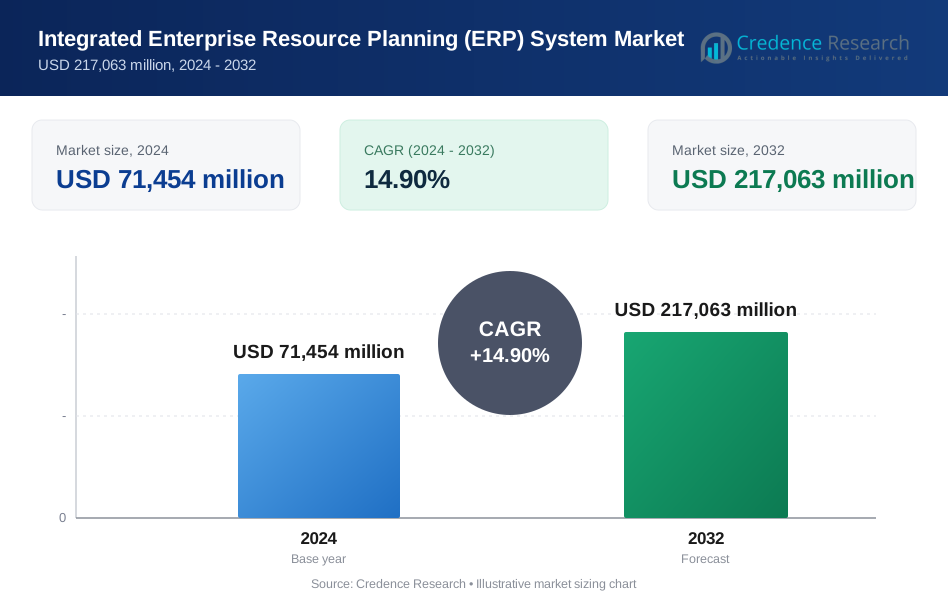
The Integrated Enterprise Resource Planning (ERP) System market is projected to grow from USD 71,454 million in 2024 to USD 217,063.49 million by 2032, with a compound annual growth rate (CAGR) of 14.9%.
The Integrated Enterprise Resource Planning (ERP) System market is driven by the increasing demand for streamlined business operations, improved decision-making, and real-time data access. As organizations strive for digital transformation, ERP systems help integrate core business functions, enhancing efficiency and productivity. The growing adoption of cloud-based solutions and artificial intelligence (AI) within ERP systems further supports this trend, offering scalability, cost-effectiveness, and advanced automation. Additionally, the shift toward data-driven insights and advanced analytics has fueled the need for ERP systems to support strategic decision-making. Industries such as manufacturing, retail, and healthcare are increasingly implementing ERP solutions to optimize operations and improve customer experiences. Moreover, the rise of remote work and the need for flexible, mobile-accessible platforms have accelerated ERP system adoption, ensuring business continuity and agility. As the market evolves, ERP systems will continue to evolve with emerging technologies, further driving their integration into business processes across various sectors.
The Integrated Enterprise Resource Planning (ERP) system market exhibits strong regional variations, with North America holding the largest market share at 34%, driven by technological advancements and cloud adoption. Europe follows with a 29% share, led by robust demand from SMEs and industries like manufacturing and finance. The Asia-Pacific region, with a 23% share, is growing rapidly due to digital transformation in emerging markets like China and India. Latin America holds an 8% share, and the Middle East and Africa account for 6%, with both regions gradually adopting ERP solutions. Key players like IBM Corp, SAP SE, Oracle Corporation, Microsoft Corporation, and Infor Inc. are leveraging their global presence to cater to these diverse regions, offering tailored ERP solutions that meet the varying demands of different industries and regulatory environments across regions.
Market Insights
- The ERP system market is projected to grow from USD 71,454 million in 2024 to USD 217,063.49 million by 2032, with a CAGR of 14.9%.
- The increasing demand for operational efficiency, digital transformation, and real-time data access is a primary driver of ERP market growth.
- Cloud-based solutions and AI integration are key trends, enhancing scalability, cost-effectiveness, and automation within ERP systems.
- Data-driven decision-making and advanced analytics are fueling the need for ERP systems to support strategic insights and improve business operations.
- Industries like manufacturing, retail, and healthcare are increasingly adopting ERP solutions to optimize their operations and customer experiences.
- North America holds the largest market share at 34%, driven by advanced technologies and early adoption of mobile ERP solutions.
- The Asia-Pacific region is experiencing rapid growth, particularly in emerging markets like China and India, driven by digital transformation and cloud ERP adoption.
Market Drivers
Increased Demand for Operational Efficiency
The primary driver behind the growth of the Integrated Enterprise Resource Planning (ERP) System market is the increasing demand for streamlined business operations. Organizations across various sectors are seeking ways to integrate core functions such as finance, procurement, sales, and human resources into a unified system. For instance, Reid MFG, a custom cabinets and door systems manufacturer, implemented Cetec ERP to address data integration issues between quoting and production. ERP solutions eliminate data silos and enable real-time information sharing, thus enhancing collaboration and decision-making. By automating routine tasks and centralizing data, businesses can achieve significant efficiency gains, reducing operational costs and boosting overall productivity.
Adoption of Cloud-Based Solutions
The rapid shift towards cloud-based technologies is another key factor propelling the ERP market. Cloud ERP solutions offer flexibility, scalability, and lower upfront costs, making them an attractive option for businesses of all sizes. These solutions allow for seamless updates, remote access, and real-time data sharing, enhancing collaboration across geographically dispersed teams. Cloud ERP platforms also help organizations avoid the significant capital expenditures associated with on-premise systems, making them particularly appealing to small and medium-sized enterprises (SMEs) seeking affordable solutions with enterprise-level capabilities.
Integration of Advanced Technologies
The incorporation of advanced technologies such as Artificial Intelligence (AI), Machine Learning (ML), and data analytics into ERP systems is driving market growth. For instane, SAP has introduced its Joule AI copilot, which enhances accessibility and operational efficiency across business systems. AI-powered ERP solutions can provide predictive analytics, automate decision-making processes, and offer personalized insights, which enhance operational performance. These technologies also enable businesses to anticipate market trends, optimize resource allocation, and improve customer satisfaction. As enterprises increasingly recognize the value of data-driven strategies, the demand for AI-integrated ERP solutions continues to rise, further fueling market expansion.
Growing Focus on Data-Driven Decision-Making
The increasing emphasis on data-driven decision-making across industries is contributing to the rise of ERP systems. Companies are prioritizing access to real-time, accurate data to gain insights into business performance and improve strategic planning. ERP systems that offer robust reporting, analytics, and dashboards provide organizations with the tools necessary to make informed decisions quickly. This ability to leverage data for better forecasting, trend analysis, and performance tracking is crucial in today’s competitive business environment, making ERP systems an essential tool for businesses aiming for sustained growth and success.
Market Trends
Cloud ERP Adoption Surge
The ongoing shift towards cloud-based ERP solutions remains one of the most significant trends in the Integrated Enterprise Resource Planning (ERP) system market. Organizations are increasingly moving away from on-premise systems in favor of cloud solutions due to their scalability, lower maintenance costs, and improved accessibility. Cloud ERP platforms enable businesses to reduce infrastructure costs, streamline updates, and ensure that data is available in real-time, from anywhere. This trend is particularly popular among small and medium-sized enterprises (SMEs), which find cloud ERP to be a cost-effective and flexible solution that grows with their business needs.
Artificial Intelligence Integration
The integration of Artificial Intelligence (AI) into ERP systems is gaining traction as businesses look to harness automation and advanced analytics to drive growth. AI-powered ERP solutions offer predictive capabilities, automate routine tasks, and enable smarter decision-making. By leveraging machine learning algorithms, ERP systems can provide insights into future trends, customer behavior, and operational inefficiencies. For instance, Zara implemented an AI-powered ERP solution using Odoo to streamline processes, improve decision-making, and enhance customer experiences. This trend empowers companies to optimize their processes, enhance customer experiences, and stay ahead of competition by making data-driven decisions faster and more accurately.
Mobile ERP Solutions
The demand for mobile access to ERP systems is increasing as businesses adopt more flexible work models and seek to enhance workforce mobility. Mobile ERP solutions allow employees to access critical business data and perform tasks from anywhere, at any time, using their smartphones or tablets. This trend aligns with the growing emphasis on remote work and flexible working arrangements, enabling employees to stay connected and productive regardless of their location. Mobile ERP solutions are particularly valuable for industries with field operations, such as manufacturing, logistics, and sales, where real-time access to data is crucial.
Focus on User Experience (UX) Design
A notable trend in the ERP market is the increased focus on improving the user experience (UX) of ERP systems. As ERP solutions become more complex, vendors are prioritizing intuitive, user-friendly interfaces to reduce the learning curve and enhance adoption rates. For instance, Workday, specializing in HR and financial management, focuses on human-centered design, allowing employees to effortlessly navigate the system with conversational UI, chatbot assistance, and a mobile-first approach, making it ideal for remote employees. A seamless UX design ensures that users can navigate the system efficiently, resulting in better productivity and fewer errors. This trend reflects the broader push toward ensuring that technology solutions are accessible and easy to use for employees at all levels within an organization.
Market Challenges Analysis
Complexity and High Implementation Costs
One of the significant challenges faced by organizations adopting Integrated Enterprise Resource Planning (ERP) systems is the complexity and high costs associated with implementation. Deploying an ERP system requires substantial investments in both time and resources, including system customization, data migration, and training. For instance, SAP's S/4HANA implementation projects often require substantial investments in system customization, data migration, and training, with average deployment times ranging from 6 to 18 months depending on the organization's size and complexity. The implementation process can be lengthy and disrupt ongoing operations, particularly for large enterprises with intricate workflowsdditionally, organizations may struggle to align the ERP system with their specific business processes, leading to potential delays, increased costs, and even project failures if not carefully managed. Smaller businesses often face financial constraints, making it difficult to justify the upfront expense of ERP solutions, especially when long-term ROI is not immediately apparent. For these companies, securing funding for ERP adoption and ensuring a smooth transition to a more integrated system can be a significant barrier to realizing the benefits of ERP technology.
Integration and Data Security Concerns
Another key challenge is the integration of ERP systems with existing legacy systems and third-party applications. Many businesses still rely on older technologies that may not be fully compatible with modern ERP solutions, creating barriers to smooth integration and data synchronization. This can result in operational inefficiencies, data discrepancies, and additional costs for system modifications or even replacing outdated infrastructure. Furthermore, the growing reliance on cloud-based ERP systems raises concerns about data security, privacy, and compliance. As sensitive business information is stored and processed in the cloud, organizations must ensure robust cybersecurity measures are in place to prevent data breaches, cyberattacks, and unauthorized access. Businesses may be hesitant to fully embrace cloud ERP solutions due to these security concerns, particularly in industries handling sensitive customer data or operating under strict regulatory frameworks. Balancing the need for accessibility with rigorous security protocols remains a significant challenge for ERP providers and end-users alike.
Market Opportunities
The Integrated Enterprise Resource Planning (ERP) system market presents significant growth opportunities driven by the increasing digitalization of businesses across various industries. As organizations continue to prioritize efficiency and real-time data-driven decision-making, the demand for ERP solutions that streamline operations and integrate diverse business functions is rising. Small and medium-sized enterprises (SMEs) represent a key growth segment, as they increasingly seek affordable, cloud-based ERP systems that offer scalability, reduced operational costs, and faster implementation times. Cloud ERP solutions, in particular, provide businesses with flexible and cost-effective options, making them an attractive choice for companies looking to enhance their digital transformation initiatives without heavy upfront investments. This expanding market presents a strong opportunity for ERP providers to tailor their offerings to meet the needs of SMEs and other emerging markets.
Another notable opportunity in the ERP system market lies in the integration of advanced technologies such as artificial intelligence (AI), machine learning (ML), and data analytics. By embedding these technologies into ERP solutions, businesses can unlock new capabilities like predictive analytics, automated decision-making, and enhanced customer insights. This will help organizations optimize their supply chain management, improve resource allocation, and anticipate future trends. The growing emphasis on data security and compliance also opens up opportunities for ERP providers to offer solutions that address these concerns, particularly in industries dealing with sensitive data such as healthcare and finance. Furthermore, as remote work continues to be a prevalent trend, the demand for mobile ERP solutions will drive opportunities for businesses to develop flexible, user-friendly platforms that cater to today’s increasingly mobile workforce.
Market Segmentation Analysis:
By Component The ERP system market is segmented into software and services. The software segment includes core ERP applications, such as finance management, supply chain management, and human resources, driving market growth. The services segment encompasses consulting, implementation, training, and support, playing a crucial role in the effective deployment and optimization of ERP systems.
By Deployment Model The deployment model segment is categorized into on-premise, cloud, and hybrid solutions. Cloud-based ERP solutions are gaining significant traction due to their flexibility, scalability, and lower upfront costs. On-premise ERP is preferred by large enterprises with strict data security needs. Hybrid models combine the best of both, allowing organizations to balance security and scalability.
By Business Function The business function segment includes finance, human resources, supply chain, customer management, inventory management, and manufacturing modules. Finance and human resources are critical for automation and data-driven decision-making, while supply chain and inventory management modules are essential for optimizing operations. Manufacturing ERP solutions ensure efficient production processes, with customer management modules enhancing customer relationship management and sales functions.
Segments:
Based on Component
- Software
- Services
Based on Deployment Model
- On-premise
- Cloud
- Hybrid
Based on Business Function
- Finance
- Human Resource
- Supply Chain
- Customer Management
- Inventory Management
- Manufacturing Module
- Others
Based on Enterprise Size
- Large Enterprises
- Medium Enterprise
- Small Enterprises
Based on End User
- Manufacturing
- BFSI
- Healthcare
- Retail & Distribution
- Government & Utilities
- IT & Telecom
- Construction
- Aerospace & Defense
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a dominant position in the Integrated Enterprise Resource Planning (ERP) system market, accounting for a market share of 34% in 2024. The region's growth is driven by the high adoption of advanced technologies, including cloud-based solutions, AI, and machine learning, which are integrated into ERP systems to enhance business operations. The United States, in particular, is home to a large number of global ERP vendors, such as SAP, Microsoft, and Oracle, contributing to the region's market leadership. Additionally, the increasing focus on automation and digital transformation across industries such as manufacturing, healthcare, and retail further drives ERP adoption. North American businesses are also early adopters of mobile ERP solutions, which cater to the growing demand for workforce mobility and real-time data access.
Europe
Europe is the second-largest market for ERP systems, with a market share of 29% in 2024. The region benefits from a high concentration of small and medium-sized enterprises (SMEs) that are increasingly adopting cloud ERP solutions for enhanced efficiency and scalability. Countries like Germany, the United Kingdom, and France are leading the way in ERP implementation, with businesses seeking to streamline operations and improve supply chain visibility. Furthermore, Europe is seeing increased demand for ERP solutions in industries such as manufacturing, automotive, and finance. Regulatory requirements, such as GDPR, have also prompted organizations to adopt ERP systems that ensure data security and compliance with European standards.
Asia-Pacific
The Asia-Pacific (APAC) region is witnessing rapid growth in the ERP system market, with a market share of 23% in 2024. This growth is primarily driven by the digital transformation initiatives of emerging economies like China, India, and Japan. APAC's diverse industrial base, including manufacturing, retail, and IT services, fuels the need for ERP systems to enhance operational efficiency and decision-making. Additionally, the growing number of SMEs in the region is contributing to the demand for cost-effective, cloud-based ERP solutions. The shift towards automation, supply chain optimization, and AI-based ERP tools is also playing a significant role in accelerating market expansion across APAC.
Latin America
Latin America holds a market share of 8% in 2024 for ERP systems. The adoption of ERP solutions in this region is gradually increasing, driven by the demand for operational efficiency, cost reduction, and real-time data access in industries such as manufacturing, retail, and logistics. Brazil, Mexico, and Argentina are leading the ERP market in Latin America, where SMEs are increasingly turning to cloud ERP solutions for scalability and flexibility. However, challenges such as limited technological infrastructure and budget constraints are slowing down widespread adoption compared to more developed regions.
Middle East and Africa
The Middle East and Africa (MEA) region accounts for a market share of 6% in 2024. The ERP market in this region is growing as businesses look to automate and optimize operations, particularly in industries such as oil and gas, manufacturing, and retail. The UAE and Saudi Arabia are leading the way, driven by investments in digital transformation and a growing focus on modernizing business processes. While the adoption of ERP systems is relatively slow in some African countries, demand is increasing as businesses strive to improve their competitive edge and streamline operations.
Key Player Analysis
- Sage Group plc
- NetSuite Inc.
- Workday Inc.
- Oracle Corporation
- QAD Inc.
- IBM Corp
- Microsoft Corporation
- Epicor Software Corporation
- Infor Inc.
- SAP SE
- Unit4
- Deltek Inc.
Competitive Analysis
The Integrated Enterprise Resource Planning (ERP) system market is highly competitive, with leading players such as IBM Corp, SAP SE, Oracle Corporation, Microsoft Corporation, Infor Inc., Epicor Software Corporation, NetSuite Inc., Sage Group plc, Workday Inc., Unit4, Deltek Inc., and QAD Inc. These companies dominate the market by offering comprehensive ERP solutions that cater to diverse industries, including manufacturing, finance, and retail. SAP SE and Oracle Corporation are recognized for their robust, scalable ERP systems, particularly for large enterprises, while Microsoft and Infor focus on integrating AI and cloud solutions to enhance user experience and operational efficiency. Workday and Sage Group provide strong ERP offerings tailored to HR and financial management needs, attracting a wide range of SMEs. Epicor and NetSuite focus on delivering highly specialized ERP solutions for industries such as manufacturing and e-commerce. As ERP technology continues to evolve, these companies are expanding their capabilities through cloud-based deployments and integrating emerging technologies like AI and machine learning to stay ahead in a competitive landscape.
Recent Developments
- In March 2023, Microsoft introduced Dynamics 365, a copilot that integrates both ERP and CRM, offering AI-powered, interactive assistance across various business functions. This tool enables enterprises to empower their employees with AI tools tailored for sales, marketing, service, operations, and supply chain management.
- In May 2023, SAP, in collaboration with IBM, expanded its ERP offerings by incorporating IBM Watson AI smarts. This integration includes digital assistants like SAP Start, which serves as a combined entry point to SAP's cloud-based software, enhancing the overall ERP experience with AI-driven insights.
- In September 2023, SAP Africa strengthened its partnership with Microsoft to provide RISE with SAP to clients across global markets, including Africa. This complete solution combines ERP software and services designed to help enterprises transition their core SAP ERP to the cloud, leveraging Microsoft’s cloud hosting capabilities.
- In December 2023, the Finnish Defense Forces teamed up with Accenture to launch a digital transformation program aimed at modernizing its existing legacy ERP system. The initiative focuses on improving user experience, system performance, and advanced reporting and analytics capabilities.
Market Concentration & Characteristics
The Integrated Enterprise Resource Planning (ERP) system market exhibits moderate to high concentration, with a few dominant players holding substantial market share. Companies like SAP SE, Oracle Corporation, IBM Corp, and Microsoft Corporation are key players that provide comprehensive ERP solutions to large enterprises across various industries. These players maintain a competitive edge through continuous innovation, extensive global reach, and strong brand recognition. The market is characterized by increasing investments in cloud-based ERP solutions, artificial intelligence (AI), and machine learning, which are integrated to enhance automation, predictive analytics, and overall system efficiency. There is a growing trend toward modular ERP systems that allow businesses to customize and scale their solutions based on specific needs. Additionally, the increasing adoption of ERP systems by small and medium-sized enterprises (SMEs) is contributing to market diversification. The market is also marked by continuous mergers, acquisitions, and strategic partnerships to expand product offerings and geographic presence.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Model, Business Function, Enterprise, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of cloud-based ERP solutions will continue to rise as businesses seek scalable and cost-effective alternatives to on-premise systems.
- The integration of artificial intelligence and machine learning will enhance ERP systems, enabling better decision-making and process automation.
- Mobile ERP solutions will see significant growth, allowing businesses to manage operations on the go and improve workforce flexibility.
- SMEs will increasingly embrace ERP systems due to the availability of affordable, cloud-based solutions tailored to their needs.
- The demand for ERP systems in emerging markets, particularly in Asia-Pacific and Latin America, will continue to grow as digital transformation accelerates.
- ERP vendors will focus on enhancing user experience through intuitive interfaces and seamless integrations with third-party applications.
- Data security and privacy concerns will drive the development of more robust ERP systems to comply with regional and global regulatory standards.
- Industries such as manufacturing, retail, and healthcare will remain key adopters of ERP systems to improve operational efficiency and supply chain management.
- Customizable ERP solutions will gain popularity as businesses seek systems tailored to their specific industry requirements.
- Strategic partnerships and acquisitions between ERP vendors and technology providers will continue to reshape the competitive landscape and expand product offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Integrated Enterprise Resource Planning (ERP) System Market?
What factors are driving the growth of the Integrated Enterprise Resource Planning (ERP) System Market?
What are the key segments within the Integrated Enterprise Resource Planning (ERP) System Market?
Who are the major players in the Integrated Enterprise Resource Planning (ERP) System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 71,454 million → 2032: USD 217,063 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Integrated Enterprise Resource Planning (ERP) System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Integrated Enterprise Resource Planning (ERP) System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Integrated Enterprise Resource Planning (ERP) System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Integrated Enterprise Resource Planning (ERP) System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Integrated Enterprise Resource Planning (ERP) System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Integrated Enterprise Resource Planning (ERP) System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Integrated Enterprise Resource Planning (ERP) System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Integrated Enterprise Resource Planning (ERP) System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 71,454 million → 2032: USD 217,063 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Integrated Enterprise Resource Planning (ERP) System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Integrated Enterprise Resource Planning (ERP) System Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Integrated Enterprise Resource Planning (ERP) System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Integrated Enterprise Resource Planning (ERP) System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
