
Market Overview
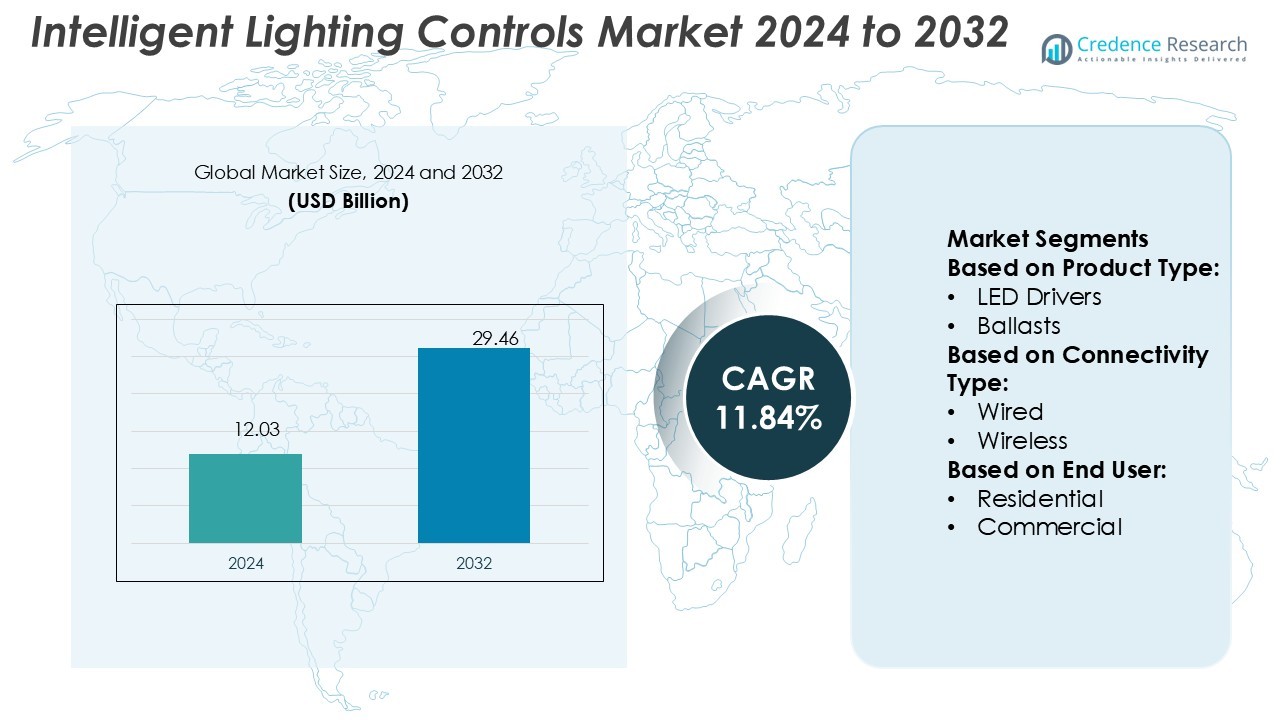
Intelligent Lighting Controls Market size was valued USD 12.03 billion in 2024 and is anticipated to reach USD 29.46 billion by 2032, at a CAGR of 11.84% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Intelligent Lighting Controls Market Size 2024 | USD 12.03 Billion |
| Intelligent Lighting Controls Market, CAGR | 11.84% |
| Intelligent Lighting Controls Market Size 2032 | USD 29.46 Billion |
The intelligent lighting controls market is shaped by top players including Schneider Electric, Hubbell Incorporated, Control4 Corporation (Snap One), OSRAM Licht AG (ams OSRAM), Acuity Brands Inc., Signify (formerly Philips Lighting), Honeywell International Inc., Lutron Electronics Co. Inc., Leviton Manufacturing Co. Inc., and LSI Industries Inc. These companies drive competition through advanced LED integration, IoT-enabled systems, and wireless connectivity solutions across residential, commercial, and industrial applications. North America leads the market with a 37% share in 2024, supported by early adoption of smart technologies, strong regulatory frameworks promoting energy efficiency, and significant investments in smart city infrastructure.
Market Insights
- The Intelligent Lighting Controls Market was valued at USD 12.03 billion in 2024 and is expected to reach USD 29.46 billion by 2032, growing at a CAGR of 11.84% during the forecast period.
- Market growth is driven by rising demand for energy efficiency, smart city development, and integration of IoT-enabled systems across residential, commercial, and industrial applications.
- Key trends include the dominance of wireless systems with 61% share and growing adoption of human-centric lighting, enhancing user experience in workplaces, healthcare, and homes.
- Competitive dynamics are shaped by leading players such as Schneider Electric, Signify, OSRAM Licht AG, Honeywell, and Acuity Brands, focusing on LED innovation, automation, and scalable connectivity solutions.
- North America leads with 37% market share in 2024, followed by Europe at 29% and Asia-Pacific at 24%, while sensors hold the largest product share at 34%, supported by energy regulations and demand for advanced building automation.
Market Segmentation Analysis:
By Product Type
In the Intelligent Lighting Controls Market, sensors hold the largest share at 34% in 2024. Their dominance stems from rising adoption in smart buildings and energy-efficient systems, where occupancy and daylight sensors reduce power consumption by up to 30%. LED drivers and ballasts follow closely, driven by widespread LED penetration in both retrofits and new installations. Switches, dimmers, and transmitters remain relevant but cater more to secondary use cases. The increasing focus on automation and compliance with energy regulations continues to boost sensor integration across residential and commercial projects.
- For instance, Hubbell’s AD1277 wall-switch sensor covers about 1,000 square feet (≈93 m²) and supports load capacities up to 800 W (incandescent) or 1,800 W (fluorescent at 277 V). Its adaptive firmware automatically adjusts the time delay to prevent false-OFF events, providing "install and forget" operation for maintenance-free use.
By Connectivity Type
Wireless systems lead this segment with a 61% market share in 2024, supported by the growing demand for flexibility and ease of installation. Technologies like Zigbee, Bluetooth, and Wi-Fi enable scalable and cost-effective solutions, particularly in smart homes and connected commercial spaces. Wired systems remain significant in industrial and large-scale commercial projects where stability and reliability are critical. However, the shift toward wireless is accelerated by IoT integration, rising adoption of Building Management Systems (BMS), and government initiatives promoting smart city infrastructure worldwide.
- For instance, Control4 uses its proprietary Control4 Zigbee PRO (based on IEEE 802.15.4) running at 250 kbps over the 2.405–2.475 GHz band; their ZigBee IO modules provide 2 relays, 4 contact inputs, and internal temperature/humidity sensing (5%–90%) in one compact unit.
By End-user
The commercial sector dominates with 46% share in 2024, driven by strong adoption in offices, retail complexes, and hospitality facilities. The focus on reducing operational costs, enhancing employee comfort, and meeting sustainability targets drives demand. Residential use follows, supported by rising smart home adoption and consumer preference for app-controlled and voice-enabled lighting systems. Industrial facilities leverage intelligent lighting for safety, energy management, and productivity. Highways and roadway lighting is expanding with the deployment of smart streetlights, integrated with adaptive brightness control and centralized monitoring to improve urban energy efficiency.
Key Growth Drivers
Rising Demand for Energy Efficiency
The push for sustainable infrastructure is driving strong adoption of intelligent lighting controls. Governments and organizations prioritize reducing electricity consumption in buildings, where lighting accounts for nearly 15–20% of total energy use. Advanced systems with occupancy sensors, daylight harvesting, and automated dimming help cut energy costs significantly. Businesses and municipalities are investing in these solutions to comply with green building certifications such as LEED and BREEAM. The ability to achieve measurable savings while meeting sustainability goals positions intelligent lighting controls as a key enabler of efficiency.
- For instance, An Light Bridge (nBRG 8) offers 8 RJ-45 ports to expand a wired nLight network's reach by aggregating traffic from daisy-chained devices. For wireless installations, the nLight ECLYPSE system controller can manage up to 750 wired and/or wireless nLight devices in a network.
Smart City Development Initiatives
Global smart city projects are fueling growth in intelligent lighting controls. Municipalities deploy adaptive street lighting integrated with IoT platforms to improve safety, reduce emissions, and optimize energy consumption. Intelligent lighting systems enable real-time monitoring, fault detection, and remote control, lowering maintenance costs for city authorities. Countries in Asia-Pacific and Europe lead these initiatives, supported by government-backed infrastructure programs. The scalability of smart streetlights into larger IoT ecosystems makes them central to urban digital transformation strategies, reinforcing their role as a long-term growth driver.
- For instance, Signify has more than 156 million IoT-connected light points globally, many operating with Zigbee, Matter, Bluetooth, and Wi-Fi protocols to ensure interoperability across smart home ecosystems.
Integration with IoT and Smart Homes
The expansion of connected ecosystems is accelerating demand for intelligent lighting controls in residential and commercial spaces. IoT-enabled lighting integrates seamlessly with voice assistants, mobile apps, and building management systems, providing enhanced user experience and automation. Rising consumer preference for smart homes, particularly in developed markets, is creating consistent demand for wireless lighting controls. In commercial buildings, integration with HVAC and security systems enhances operational efficiency. The rapid penetration of IoT platforms and declining costs of connected devices are expanding adoption across multiple end-user segments.
Key Trends & Opportunities
Shift Toward Wireless Connectivity
Wireless lighting control systems are emerging as the dominant choice due to ease of installation and scalability. Technologies such as Zigbee, Bluetooth, and Wi-Fi are being increasingly adopted in smart homes, offices, and industrial spaces. This shift reduces infrastructure costs and enables greater flexibility for retrofitting older buildings. Vendors are focusing on developing interoperable solutions that support multiple protocols, addressing compatibility concerns. The growing adoption of wireless solutions also creates opportunities for service providers to offer subscription-based lighting-as-a-service models.
- For instance, Inventronics (the company that now owns the former Osram HubSense product line) offers the QBM IoT Gateway, which supports up to 200 nodes (including LED drivers and sensors) in a single qualified Bluetooth mesh network, enabling robust control in wholesale-scale lighting installations.
Focus on Human-Centric Lighting
Human-centric lighting is gaining traction as workplaces and healthcare facilities recognize its impact on well-being and productivity. Intelligent controls allow dynamic adjustment of light color temperature and intensity to align with circadian rhythms. This enhances concentration during work hours and supports relaxation in residential environments. Hospitals and eldercare centers are adopting these systems to improve patient recovery outcomes. The trend opens opportunities for manufacturers to design solutions tailored to health and wellness, expanding beyond traditional energy efficiency benefits to holistic user experiences.
- For instance, Dialight’s Vigilant® High Bay offers lumen outputs in a wide range, from approximately 11,000 to 41,300 lumens, with modern models boasting efficacies reaching up to 200 lm/W.
Key Challenges
High Initial Installation Costs
Despite long-term savings, the high upfront cost of intelligent lighting control systems remains a barrier. Expenses related to sensors, controllers, and integration with building management systems can deter adoption, particularly among small and medium enterprises. Retrofitting existing infrastructure adds further cost pressures. While government subsidies and falling sensor prices are easing the challenge, many end-users remain cautious. Vendors need to emphasize total cost of ownership (TCO) benefits and develop financing models, such as lighting-as-a-service, to overcome this adoption hurdle.
Complexity of System Integration
Integrating intelligent lighting controls with existing building automation systems poses significant challenges. Compatibility issues arise when devices operate on different communication protocols, creating risks of inefficiency and downtime. Enterprises require skilled technicians to manage installation and maintenance, adding complexity and costs. In large-scale projects, integration with HVAC, security, and IoT platforms further complicates deployment. Lack of standardized frameworks also hampers interoperability. Addressing these challenges will require industry-wide collaboration, development of universal protocols, and user-friendly plug-and-play solutions to simplify system deployment and scalability.
Regional Analysis
North America
North America dominates the intelligent lighting controls market with a 37% share in 2024. The region benefits from strong adoption of smart building technologies, stringent energy efficiency regulations, and advanced infrastructure. The United States leads demand, supported by large-scale commercial real estate projects and government incentives promoting green construction. Canada is also witnessing rapid uptake in smart residential and commercial lighting systems. Integration with IoT platforms and the rise of connected homes further enhance market growth. Investments in smart city projects, including adaptive street lighting, continue to position North America as a key revenue-generating region.
Europe
Europe holds 29% of the intelligent lighting controls market in 2024, driven by sustainability-focused policies and wide-scale deployment of energy-efficient technologies. Countries such as Germany, the United Kingdom, and France lead adoption, supported by EU directives on carbon reduction and smart city expansion. Strong emphasis on building automation and retrofitting projects accelerates integration of advanced controls across residential and commercial spaces. Growth is also supported by increased demand for human-centric lighting in workplaces and healthcare facilities. Europe’s commitment to renewable energy and green infrastructure reinforces its position as a mature and steadily expanding regional market.
Asia-Pacific
Asia-Pacific accounts for 24% of the global intelligent lighting controls market in 2024, emerging as the fastest-growing region. China, Japan, and India are driving demand with large-scale infrastructure projects, rapid urbanization, and strong government backing for smart cities. Growing adoption of smart homes and connected devices boosts residential demand, while commercial buildings and industrial facilities implement energy-efficient lighting solutions for cost savings. Wireless controls and IoT integration are expanding quickly, supported by declining device costs. Increasing investments in road and highway lighting projects further reinforce Asia-Pacific’s growth trajectory, positioning the region as a key driver of future global expansion.
Latin America
Latin America holds a 4% share of the intelligent lighting controls market in 2024, with Brazil and Mexico leading adoption. The region benefits from growing urbanization, energy conservation initiatives, and rising investments in smart infrastructure. Commercial projects such as shopping complexes, hotels, and office buildings drive demand for intelligent lighting systems. Governments are encouraging energy-efficient solutions to address rising electricity costs, particularly in urban areas. Residential adoption is also growing with increased availability of wireless and app-controlled solutions. While challenges related to infrastructure remain, Latin America shows promising potential for expansion in the coming years.
Middle East & Africa
The Middle East & Africa region represents 6% of the global intelligent lighting controls market in 2024, showing steady growth potential. GCC countries, including the UAE and Saudi Arabia, lead adoption through smart city initiatives such as NEOM and Dubai Smart City. Demand is supported by investments in commercial real estate, highways, and large-scale infrastructure projects. Africa is at an early adoption stage but is witnessing growth in urban centers, particularly in South Africa. Rising focus on energy efficiency, coupled with the deployment of LED-based smart streetlights, supports gradual expansion across this region.
Market Segmentations:
By Product Type:
- LED Drivers
- Ballasts
By Connectivity Type:
- Wired
- Wireless
By End User:
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the intelligent lighting controls market features leading players such as Schneider Electric, Hubbell Incorporated, Control4 Corporation (Snap One), OSRAM Licht AG (ams OSRAM), Acuity Brands Inc., Signify (formerly Philips Lighting), Honeywell International Inc., Lutron Electronics Co. Inc., Leviton Manufacturing Co. Inc., and LSI Industries Inc. The intelligent lighting controls market is characterized by rapid innovation, strategic partnerships, and expanding applications across residential, commercial, industrial, and roadway segments. Companies are focusing on integrating IoT, wireless technologies, and human-centric lighting to differentiate their offerings and capture market share. Mergers, acquisitions, and collaborations are common strategies to enhance product portfolios and extend geographic reach. Increasing demand for energy-efficient and sustainable solutions is pushing vendors to invest in R&D, while service-based models such as lighting-as-a-service are gaining traction. This dynamic environment fosters competition, accelerates innovation, and drives long-term market growth.
Key Player Analysis
- Schneider Electric
- Hubbell Incorporated
- Control4 Corporation (Snap One)
- OSRAM Licht AG (ams OSRAM)
- Acuity Brands Inc.
- Signify (formerly Philips Lighting)
- Honeywell International Inc.
- Lutron Electronics Co. Inc.
- Leviton Manufacturing Co. Inc.
- LSI Industries Inc.
Recent Developments
- In January 2025, Lutron Electronics announced the launch of its wireless RadioRA 3 lighting control system in the UK. With an array of controls, smart lighting, and automated window treatments that all communicate and coordinate with one another wirelessly.
- In October 2024, Bajaj Lighting, with over 80 years of generational expertise in lighting solutions, announced its revamped positioning under the tagline “Built to Shine.” This strategic shift is expected to drive positive impacts on business growth and reinforce Bajaj’s dominance in the lighting industry.
- In August 2024, Philips Hue ventured into affordability with the launch of the new Tento ceiling light lineup. Philips has tons of fully integrated smart lamps - and with modern LEDs, it’s not like you’ll be changing a lot of bulbs, anyway.
- In March 2024, Casambi, a smart lighting control solution provider unveiled Salvador, its latest innovation in DALI controllers. This launch marks a significant step into the wired lighting control sector, positioning the company as a major player in the mainstream lighting controls market. With Salvador, the firm enhances its portfolio, demonstrating its commitment to advanced and reliable solutions in wired lighting control.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Connectivity Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with wider adoption of smart building technologies.
- Wireless systems will continue to dominate due to scalability and ease of installation.
- Human-centric lighting will gain importance in workplaces, healthcare, and residential spaces.
- Integration with IoT platforms will enhance automation and energy efficiency.
- Smart city initiatives will drive large-scale deployment of adaptive street lighting.
- Declining sensor and control device costs will improve affordability for end-users.
- Service-based models such as lighting-as-a-service will attract new customers.
- Demand will rise in developing regions with rapid urbanization and infrastructure growth.
- Interoperability standards will improve, reducing integration complexities for enterprises.
- Sustainability goals will accelerate replacement of conventional lighting with intelligent solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy Efficiency Regulations
Stringent government policies and green building certifications are pushing organizations to adopt intelligent lighting controls, which help reduce electricity consumption and operational costs in buildings where lighting accounts for a significant portion of energy use.
Smart City Development
Global investments in smart city infrastructure are driving large-scale deployment of adaptive and IoT-integrated lighting systems, enabling real-time monitoring, remote control, and energy optimization for urban environments.
IoT and Smart Home Integration
The proliferation of IoT platforms and connected devices is accelerating the adoption of intelligent lighting controls in both residential and commercial spaces, as users seek seamless automation, voice control, and integration with broader building management systems.
Wireless Technology Adoption
The shift toward wireless lighting control systems, enabled by protocols like Zigbee, Bluetooth, and Wi-Fi, is reducing installation complexity and costs, making it easier to retrofit existing buildings and scale solutions across diverse environments.
Focus on Human-Centric Lighting
Growing awareness of the impact of lighting on health and productivity is increasing demand for intelligent controls that enable dynamic adjustment of light intensity and color temperature, particularly in workplaces, healthcare, and residential settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Intelligent Lighting Controls Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Intelligent Lighting Controls Market projected to grow between 2025 and 2032?
Which Intelligent Lighting Controls Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Intelligent Lighting Controls Market?
Who are the leading companies in the Intelligent Lighting Controls Market?
Which region commanded the largest share of the Intelligent Lighting Controls Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.2.4 Highways & Roadways
- 1.3 By Product Type
- 1.3.1 Sensors
- 1.3.2 LED Drivers
- 1.3.3 Ballasts
- 1.3.4 Switches
- 1.3.5 Dimmers
- 1.3.6 Transmitters
- 1.4 By Connectivity Type
- 1.4.1 Wired
- 1.4.2 Wireless
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.03 billion → 2032: USD 29.46 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Intelligent Lighting Controls Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Intelligent Lighting Controls Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Intelligent Lighting Controls Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Intelligent Lighting Controls Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Intelligent Lighting Controls Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Intelligent Lighting Controls Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Intelligent Lighting Controls Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Intelligent Lighting Controls Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.03 billion → 2032: USD 29.46 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Intelligent Lighting Controls Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.7.4 Highways & Roadways
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sensors
- 12.4.7.2 LED Drivers
- 12.4.7.3 Ballasts
- 12.4.7.4 Switches
- 12.4.7.5 Dimmers
- 12.4.7.6 Transmitters
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Connectivity Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wired
- 12.5.7.2 Wireless
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Intelligent Lighting Controls End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Intelligent Lighting Controls Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Intelligent Lighting Controls Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Intelligent Lighting Controls Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schneider Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hubbell Incorporated
- 18.4 Control4 Corporation (Snap One)
- 18.5 OSRAM Licht AG (ams OSRAM)
- 18.6 Acuity Brands Inc.
- 18.7 Signify (formerly Philips Lighting)
- 18.8 Honeywell International Inc.
- 18.9 Lutron Electronics Co. Inc.
- 18.10 Leviton Manufacturing Co. Inc.
- 18.11 LSI Industries Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

