
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Interactive Wound Dressing Market Size 2024 | USD 5201.5 Million |
| Interactive Wound Dressing Market, CAGR | 5.9% |
| Interactive Wound Dressing Market Size 2032 | USD 8228.03 Million |
Market Overview:
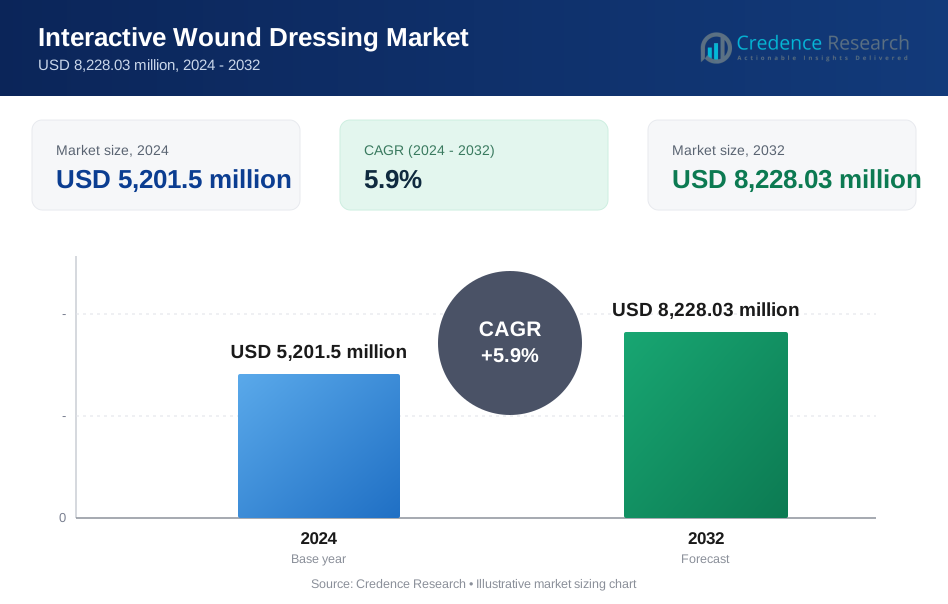
The Interactive Wound Dressing Market is projected to grow from USD 5201.5 million in 2024 to an estimated USD 8228.03 million by 2032, with a compound annual growth rate (CAGR) of 5.9% from 2024 to 2032.
Key market drivers propelling the Interactive Wound Dressing Market include a growing focus on enhancing healthcare efficiency, reducing treatment costs, and meeting the rising demand for advanced wound care solutions. Interactive wound dressings, which promote an optimal healing environment, are increasingly being adopted due to their effectiveness in managing complex and chronic wounds such as pressure ulcers, diabetic foot ulcers, and post-surgical wounds. The market is further bolstered by significant investments in research and development, leading to innovations such as antimicrobial dressings, moisture-balancing technologies, and dressings that adapt to specific wound needs. Additionally, improved reimbursement policies and regulatory support have encouraged the widespread use of these solutions, making them a preferred choice for healthcare providers seeking to optimize patient outcomes and enhance care standards.
From a regional perspective, North America commands a leading share of the Interactive Wound Dressing Market due to high healthcare expenditure, a substantial volume of surgical procedures, and strong acceptance of advanced wound care technologies. Europe also holds a significant market position, supported by a growing geriatric population, robust healthcare systems, and favorable regulatory environments that encourage the use of advanced dressings. Meanwhile, the Asia-Pacific region is witnessing rapid market expansion, driven by rising healthcare investments, increased prevalence of chronic diseases, and growing patient awareness regarding advanced wound care therapies. This region presents considerable growth opportunities as improving healthcare infrastructure and economic development enable greater access to innovative wound care solutions.
Market Drivers:
Growing Prevalence of Chronic Wounds and Aging Population:
The increasing prevalence of chronic wounds, such as diabetic foot ulcers, pressure ulcers, and venous leg ulcers, is a major driver of growth in the Interactive Wound Dressing Market. For instance, chronic wounds affect approximately 2% of the population in developed countries. These wounds often require specialized care, prolonged healing time, and effective management to prevent complications, which underscores the need for advanced wound care products like interactive dressings. These dressings provide an optimal environment for wound healing by controlling moisture, promoting cell proliferation, and reducing the risk of infections. Additionally, the aging global population, which is more prone to developing chronic wounds due to age-related factors, further amplifies the demand for innovative wound care solutions. By 2050, the number of people aged 60 years and older is expected to double to 2.1 billion
Advancements in Wound Care Technology:
Ongoing innovations and technological advancements in wound care have significantly enhanced the functionality and effectiveness of interactive wound dressings. Modern dressings incorporate features such as antimicrobial properties, moisture balance, and smart sensors that monitor wound healing progress. These advancements provide healthcare professionals with more precise tools to tailor wound care, improving patient outcomes and reducing overall treatment costs. The adoption of technologies like bioactive dressings and hydrocolloids further illustrates the industry's commitment to leveraging innovation for better wound management. As a result, the market is experiencing accelerated growth, fueled by the potential for more effective and efficient wound healing solutions.
Increased Focus on Minimally Invasive and Cost-Effective Solutions:
The healthcare industry’s emphasis on minimally invasive treatments and cost-effective solutions has played a pivotal role in driving demand for interactive wound dressings. Unlike traditional wound care approaches, these advanced dressings reduce the need for frequent changes, minimize patient discomfort, and promote faster healing, ultimately reducing hospital stays and overall healthcare costs. As healthcare systems worldwide strive for improved patient outcomes with minimal resources, interactive wound dressings align with these goals by delivering superior therapeutic benefits. This cost-effective nature and efficiency of interactive dressings have made them a preferred choice among healthcare providers, especially for treating complex wounds in outpatient settings.
Supportive Regulatory Frameworks and Favorable Reimbursement Policies:
Supportive regulatory frameworks and favorable reimbursement policies for advanced wound care products have also played a crucial role in market growth. Many countries have established guidelines that prioritize and promote the use of interactive wound dressings for specific wound types, thereby encouraging their adoption in healthcare settings. For instance, the FDA has specific guidelines for the approval and use of advanced wound care products. Moreover, the presence of reimbursement programs that cover advanced wound care products helps reduce the financial burden on patients and healthcare providers. This regulatory support has encouraged both established and emerging manufacturers to invest in research and development of new and improved dressing solutions, thereby driving innovation and market expansion. The overall result is an environment conducive to the widespread adoption of interactive wound dressings, supported by effective policy measures and economic incentives.
Market Trends:
Rise of Antimicrobial and Bioactive Dressings:
The increasing incidence of infections associated with chronic wounds has fueled a strong demand for antimicrobial and bioactive dressings within the Interactive Wound Dressing Market. Unlike traditional dressings, antimicrobial dressings incorporate active agents such as silver, iodine, and honey, which effectively reduce microbial load and prevent wound infection. Meanwhile, bioactive dressings, which contain substances like growth factors and collagen, actively promote cell growth and tissue repair. This trend is gaining momentum as healthcare providers recognize the importance of accelerating wound healing while reducing infection rates, particularly in high-risk patients. The consistent demand for infection-preventing technologies has led to significant innovation and market expansion, offering improved clinical outcomes and transforming the standards of wound care.
Integration of Smart Technology and Digital Monitoring:
The market is witnessing a surge in demand for smart interactive dressings equipped with sensors and digital capabilities to monitor wound healing. These intelligent dressings collect real-time data on wound conditions such as moisture levels, pH balance, and temperature, enabling healthcare professionals to make informed decisions on treatment adjustments. This trend aligns with the growing movement toward personalized and data-driven medicine, which emphasizes continuous monitoring and tailored interventions. For instance, 3M has introduced smart dressings that collect real-time data on wound conditions such as moisture levels and temperature, with an accuracy rate of ±0.5°C for temperature monitoring. The integration of digital technology not only enhances patient engagement and compliance but also facilitates remote monitoring, an especially valuable feature for patients in rural or underserved areas. As healthcare shifts towards precision medicine, smart dressings are rapidly becoming a key differentiator in the market, attracting attention from investors and innovators.
Eco-Friendly and Biodegradable Dressing Solutions:
Another notable trend in the Interactive Wound Dressing Market is the rising demand for eco-friendly and biodegradable products. With growing awareness of environmental issues and regulatory pressure to minimize healthcare waste, manufacturers are focusing on creating sustainable dressing solutions. These biodegradable dressings, typically derived from natural and biocompatible materials, decompose safely after use, reducing environmental impact. This trend has resonated well with healthcare providers and environmentally conscious consumers alike, driving interest and adoption of these products. The shift towards sustainable healthcare practices not only contributes to a cleaner environment but also reflects evolving consumer preferences and regulatory mandates that prioritize environmentally responsible solutions.
Expansion of Emerging Markets and Increasing Access to Advanced Care:
Emerging markets in Asia-Pacific, Latin America, and the Middle East are experiencing rapid growth due to improving healthcare infrastructure and increased access to advanced wound care solutions. As governments invest in healthcare modernization, the adoption of interactive wound dressings is expanding beyond established markets in North America and Europe. This trend is further supported by rising healthcare awareness, an increasing prevalence of chronic diseases, and a growing middle-class population seeking quality medical care. The expansion into emerging markets represents a significant growth opportunity for manufacturers, encouraging them to tailor products and strategies to meet diverse regional needs. This geographic expansion is reshaping the competitive landscape, with companies vying to establish a foothold in these high-potential regions.
Market Restraints and Challenges:
High Cost of Advanced Wound Care Products:
One of the key restraints in the Interactive Wound Dressing Market is the high cost associated with advanced wound care products. Interactive dressings, which offer superior healing capabilities and advanced features such as antimicrobial properties or digital monitoring, often come at a premium price compared to traditional wound dressings. For instance, a survey by the National Wound Care Strategy Programme (NWCSP) in the UK found that the cost of treating chronic wounds was approximately £3.1 billion annually. This cost disparity can make it challenging for healthcare providers, especially in low- and middle-income regions, to adopt these innovative solutions on a large scale. The affordability issue may also deter patients from seeking advanced treatments, particularly in regions with limited or inconsistent healthcare reimbursement policies.
Limited Awareness and Training Among Healthcare Providers:
Despite their effectiveness, interactive wound dressings face adoption hurdles due to limited awareness and inadequate training among healthcare providers. Many clinicians remain accustomed to traditional wound care methods and may not fully understand the benefits or appropriate application of interactive dressings. This knowledge gap can result in underutilization, suboptimal patient outcomes, and missed opportunities to enhance care. Bridging this gap requires investment in comprehensive training and education programs to ensure that healthcare professionals are well-equipped to integrate interactive dressings into their wound management protocols.
Regulatory and Reimbursement Challenges:
The regulatory landscape for interactive wound dressings can be complex and varies significantly across regions. Stringent approval processes, lengthy clinical trials, and evolving standards often pose challenges for manufacturers looking to bring new products to market quickly. Additionally, inconsistent reimbursement policies can further hinder market growth by creating uncertainty for healthcare providers and patients regarding coverage and costs. Without comprehensive and consistent reimbursement structures, adoption rates may remain constrained, particularly for newer and more advanced interactive dressing technologies. This regulatory complexity and reimbursement inconsistency are significant challenges that the market must address to achieve widespread acceptance and growth.
Market Segmentation Analysis:
The Interactive Wound Dressing Market is segmented based on product, application, and end-use, each playing a crucial role in driving market dynamics.
By product, semi-permeable film dressings, semi-permeable foam dressings, and hydrogel dressings dominate the market. Semi-permeable film dressings are favored for their breathability and ability to create a protective barrier, while semi-permeable foam dressings offer enhanced absorption capabilities, making them ideal for moderate to heavily exuding wounds. Hydrogel dressings, known for their cooling and moisturizing effects, are widely utilized for wounds requiring moisture control and pain relief, such as burns and ulcers.
By application, the market is divided into chronic and acute wounds. Chronic wounds, including pressure ulcers, diabetic foot ulcers, and venous leg ulcers, represent the largest segment due to their prevalence and need for ongoing, specialized care. Interactive dressings' ability to create an optimal healing environment makes them essential for managing these long-term conditions. The acute wounds segment, encompassing surgical wounds and trauma injuries, also demonstrates strong demand, driven by the need for rapid healing and infection prevention.
By end-use, hospitals hold a significant share due to the large volume of wound care procedures performed in these settings. Outpatient facilities and home care settings are witnessing growth as patients increasingly seek cost-effective and convenient care options. The research and manufacturing segment contributes to market expansion through continuous development and testing of innovative interactive dressing solutions, further enhancing market growth and adoption.
Segmentation:
By Product
- Semi-permeable films dressing
- Semi-permeable foams dressing
- Hydrogel dressing
By Application
- Chronic Wounds
- Acute Wounds
By End-use
- Hospitals
- Outpatient Facilities
- Home care
- Research & manufacturing
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Interactive Wound Dressing Market is geographically segmented into North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, each exhibiting distinct market dynamics and growth trends.
North America holds the largest share of the market, driven by high healthcare expenditure, advanced medical infrastructure, and strong adoption of innovative wound care technologies. The region's demand is further fueled by a high prevalence of chronic conditions such as diabetes and obesity, which often result in chronic wounds. The United States leads the market in this region, followed by Canada, supported by favorable reimbursement policies, extensive research initiatives, and widespread use of advanced wound care solutions.
Europe represents another major market for interactive wound dressings, supported by a well-established healthcare system, an aging population, and strong awareness of advanced wound care products. Countries like Germany, the UK, and France are key players due to their robust healthcare infrastructure and adoption of state-of-the-art wound management technologies. Regulatory support and clinical guidelines promoting the use of advanced dressings further drive adoption across the region.
The Asia-Pacific region is anticipated to experience the fastest growth in the market over the coming years. This growth is attributed to a large and growing population, increasing prevalence of chronic diseases, rising healthcare expenditures, and improving healthcare infrastructure. Countries such as China, India, and Japan are leading the region’s growth, focusing on the adoption of innovative wound care solutions and enhancing patient access to advanced treatments. Increasing awareness of wound care management and government initiatives to boost healthcare accessibility further contribute to the region’s expansion.
Latin America and the Middle East & Africa hold smaller market shares compared to other regions but are gradually expanding. In Latin America, growth is driven by increasing healthcare awareness, better access to healthcare services, and a focus on enhanced wound care management, with Brazil and Mexico as key contributors. In the Middle East & Africa, efforts to modernize healthcare systems are helping drive adoption, although the market penetration remains lower than in more developed regions. The rising prevalence of chronic wounds and diabetes presents opportunities for further growth as healthcare infrastructure improves.
Key Player Analysis:
- 3M Company
- Acelity L.P. Inc. (a subsidiary of 3M)
- Advancis Medical Ltd.
- B. Braun Melsungen AG
- Coloplast A/S
- ConvaTec Group PLC
- DermaRite Industries, LLC
- Gentell, Inc.
- Integra LifeSciences Holdings Corporation
- Lohmann & Rauscher GmbH & Co. KG
- Medline Industries, Inc.
- Medtronic plc
- Mölnlycke Health Care AB
- Paul Hartmann AG
- Smith & Nephew plc
Competitive Analysis:
The Interactive Wound Dressing Market is characterized by intense competition, driven by rapid innovation and strong demand for advanced wound care solutions. Key market players include established companies like Smith & Nephew, Mölnlycke Health Care, ConvaTec Group, 3M Company, and Johnson & Johnson, all of which are focusing on expanding their product portfolios through research and development and strategic acquisitions. These companies emphasize the development of advanced technologies, such as antimicrobial dressings and bioactive materials, to enhance healing and reduce treatment times. New entrants and regional manufacturers are increasingly making their presence known by offering cost-effective and innovative solutions tailored to emerging market needs. Competitive differentiation centers on product efficacy, pricing, technological innovation, and partnerships with healthcare providers to drive adoption. The market’s competitive dynamics are further shaped by regulatory compliance and the ability to meet evolving patient and healthcare provider requirements.
Recent Developments:
- Mölnlycke Health Care AB announced the launch of a new range of Mepilex Border Flex dressings on October 15, 2024. These dressings integrate advanced technology to provide enhanced flexibility and comfort for patients with chronic wounds.
- Smith & Nephew plc entered a strategic partnership with Teleflex on November 5, 2024, aimed at developing innovative wound management solutions that leverage both companies' technologies to improve patient outcomes and streamline healthcare processes.
- 3M Company launched an updated version of its 3M Tegaderm™ CHG IV Securement Dressing on September 20, 2024, which now features enhanced antimicrobial properties to better protect against infection in patients with chronic wounds.
Market Concentration & Characteristics:
The Interactive Wound Dressing Market is moderately concentrated, with a mix of dominant global players and smaller, innovative companies competing within the space. Major industry leaders, including Smith & Nephew, Mölnlycke Health Care, ConvaTec Group, 3M Company, and Johnson & Johnson, account for a significant portion of the market share due to their established brand presence, comprehensive product offerings, and extensive distribution networks. The market is characterized by continuous innovation, with a strong emphasis on developing advanced wound care solutions that enhance healing efficiency and reduce patient recovery times. Key differentiators among competitors include technological capabilities, product efficacy, pricing, and targeted solutions for specific wound types. Emerging players and regional manufacturers also compete by offering cost-effective alternatives and customized products tailored to meet local healthcare needs. Regulatory compliance and the ability to adapt to changing clinical guidelines further influence market dynamics and growth.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Application and By End-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing prevalence of chronic diseases and an aging population will drive demand for advanced wound care solutions.
- Innovations in antimicrobial and bioactive technologies are expected to boost product development and adoption.
- Growing focus on minimally invasive and personalized wound care treatments will fuel market expansion.
- Rising healthcare expenditure and awareness in emerging markets will open new growth opportunities.
- Integration of smart technologies for wound monitoring will enhance patient care and engagement.
- Regulatory and reimbursement reforms are likely to streamline market entry and adoption of advanced dressings.
- Demand for eco-friendly and biodegradable products will increase, driven by sustainability initiatives.
- Expansion of telehealth and home care services will elevate the use of interactive dressings for remote and self-care treatment.
- Strategic partnerships and acquisitions among market players will continue to drive innovation and competitive positioning.
- Challenges related to high costs may push manufacturers toward developing cost-effective solutions for broader market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size and projected growth for the Interactive Wound Dressing Market?
What factors are driving the growth of this market?
Which region leads the market?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Interactive Wound Dressing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Interactive Wound Dressing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,201.5 million → 2032: USD 8,228.03 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Interactive Wound Dressing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Interactive Wound Dressing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Interactive Wound Dressing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Interactive Wound Dressing Market Drivers
- 3.3 Interactive Wound Dressing Market Restraints & Challenges
- 3.4 Interactive Wound Dressing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Interactive Wound Dressing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Interactive Wound Dressing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Interactive Wound Dressing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Interactive Wound Dressing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Interactive Wound Dressing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Interactive Wound Dressing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Interactive Wound Dressing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Interactive Wound Dressing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Interactive Wound Dressing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Interactive Wound Dressing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Interactive Wound Dressing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Interactive Wound Dressing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Interactive Wound Dressing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Interactive Wound Dressing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Interactive Wound Dressing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Interactive Wound Dressing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Interactive Wound Dressing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Interactive Wound Dressing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Interactive Wound Dressing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
