
Market Overview:
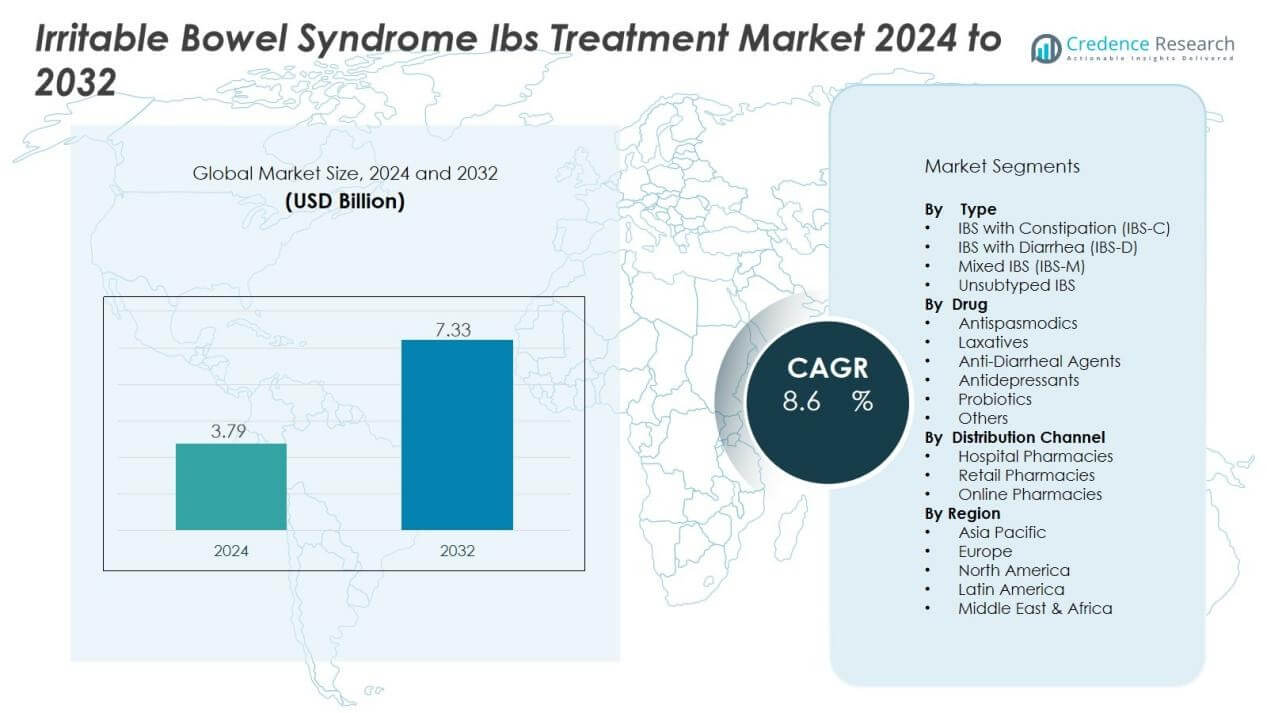
The irritable bowel syndrome treatment market size was valued at USD 3.79 billion in 2024 and is anticipated to reach USD 7.33 billion by 2032, at a CAGR of 8.6 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Irritable Bowel Syndrome Treatment Market Size 2024 | USD 3.79 Billion |
| Irritable Bowel Syndrome Treatment Market, CAGR | 8.6% |
| Irritable Bowel Syndrome Treatment Market Size 2032 | USD 7.33 Billion |
Market growth is primarily fueled by rising global prevalence of IBS, linked to lifestyle changes, dietary patterns, and stress levels. Demand for improved gastrointestinal therapies, particularly those addressing multiple IBS symptoms, supports expansion. Pharmaceutical companies are investing in novel drugs, probiotics, and dietary supplements to broaden treatment options. Greater focus on patient-centered care, early diagnosis, and improved healthcare infrastructure also enhances accessibility, boosting treatment adoption across different demographics.
Regionally, North America leads the IBS treatment market due to advanced healthcare systems, high awareness, and strong presence of pharmaceutical players. Europe follows, supported by favorable reimbursement policies and ongoing research in gastrointestinal disorders. Asia-Pacific shows the fastest growth, driven by rising diagnosis rates, improving healthcare access, and increasing investments in gastrointestinal therapeutics. Latin America and the Middle East & Africa exhibit steady growth, supported by growing healthcare expenditure and expanding treatment availability.
Market Insights:
- The irritable bowel syndrome (IBS) treatment market was valued at USD 3.79 billion in 2024 and is projected to reach USD 7.33 billion by 2032 at a CAGR of 8.6%.
- Rising global prevalence of IBS, linked to lifestyle changes, poor dietary habits, and stress levels, continues to drive market growth.
- Demand for targeted therapies addressing multiple symptoms such as abdominal pain, diarrhea, and constipation supports expansion.
- Pharmaceutical companies are investing in novel drugs, probiotics, and biologics while strengthening R&D pipelines to improve treatment outcomes.
- High treatment costs and limited reimbursement frameworks remain key challenges, restricting adoption in low- and middle-income regions.
- North America leads with 42% market share, supported by strong healthcare infrastructure, advanced therapies, and widespread insurance coverage.
- Asia-Pacific records the fastest growth with 21% share, driven by improving healthcare access, rising diagnosis rates, and higher awareness levels.
Market Drivers:
Rising Prevalence of IBS and Lifestyle-Related Disorders:
The irritable bowel syndrome (IBS) treatment market is primarily driven by the rising prevalence of gastrointestinal disorders linked to changing lifestyles and dietary habits. Increased stress, irregular eating patterns, and consumption of processed foods have led to higher diagnosis rates worldwide. It is supported further by improved patient awareness and growing acceptance of IBS as a chronic condition requiring consistent management. This trend creates a significant need for effective treatments across both developed and emerging economies.
- For instance, Ironwood Pharmaceuticals achieved significant commercial success with LINZESS (linaclotide), reporting U.S. net sales of $248 million in Q2 2025 with 10% year-over-year prescription demand growth
Growing Demand for Targeted and Symptom-Specific Therapies:
A key driver is the growing demand for therapies that address multiple IBS symptoms such as abdominal pain, constipation, and diarrhea. Patients prefer treatments that deliver long-term relief while minimizing side effects. It encourages pharmaceutical companies to develop advanced drug formulations, probiotics, and nutritional supplements tailored to diverse patient needs. The availability of these targeted solutions boosts adoption and drives innovation in the irritable bowel syndrome IBS treatment market.
- For instance, AbbVie and Ironwood Pharmaceuticals' Linzess (linaclotide) achieved FDA approval in December 2023 as the first prescription treatment for functional constipation in pediatric patients aged 6-17 years, with a 72 mcg dosage demonstrating significant improvement in weekly spontaneous bowel movements.
Expansion of Healthcare Infrastructure and Access to Diagnosis:
Improved healthcare infrastructure and access to advanced diagnostic tools also drive market growth. Many countries are investing in better healthcare delivery systems, enabling early and accurate diagnosis of IBS. It helps patients receive timely treatment, reducing disease burden and improving quality of life. Expanded access in developing regions is expected to play a central role in driving demand for IBS therapies.
Pharmaceutical Innovation and Growing R&D Investments:
The development of new drugs and biologics remains a critical growth driver. Major pharmaceutical companies are investing heavily in research and development to bring innovative treatment options to market. It strengthens competitive intensity while providing patients with safer and more effective therapeutic choices. Continuous innovation and clinical advancements are expected to sustain momentum in the irritable bowel syndrome IBS treatment market.
 Market Trends:
Adoption of Personalized Medicine and Probiotic-Based Therapies:
One of the most significant trends in the irritable bowel syndrome (IBS) treatment market is the adoption of personalized medicine tailored to individual patient needs. Physicians are focusing on therapies based on patient history, symptom severity, and gut microbiota composition. Probiotic-based therapies are gaining traction due to their ability to restore gut balance and reduce dependency on synthetic drugs. It is further supported by rising consumer preference for natural and holistic treatments. Increased clinical trials investigating microbiome-focused interventions highlight the shift toward innovative therapeutic approaches. This trend enhances treatment outcomes while expanding choices available to patients.
- For instance, Thorne HealthTech developed a microbiome-guided personalized prebiotic and probiotic algorithm that achieved a significant reduction in IBS severity scores by 38.0 points in clinical trials involving 120 patients, with particularly strong results showing 44.5-point reductions in IBS-D patients and 51.2-point reductions in IBS-C patients.
Integration of Digital Health Solutions and Non-Pharmacological Approaches:
The integration of digital health technologies and non-drug-based therapies is reshaping the IBS treatment landscape. Mobile health apps and remote monitoring tools are helping patients track symptoms and improve disease management. It supports better adherence to dietary changes, stress management, and lifestyle modifications. Non-pharmacological interventions such as cognitive behavioral therapy, hypnotherapy, and dietary plans are also being integrated into care models. Pharmaceutical players are collaborating with digital health providers to enhance treatment ecosystems. This trend strengthens the irritable bowel syndrome IBS treatment market by combining medical innovation with lifestyle-oriented solutions.
- For instance, Mahana Therapeutics' Mahana IBS app recorded 843 physician-prescribed users between August 2021 and August 2023, with those completing the full 10-session cognitive behavioral therapy program achieving a reduction of 104 points in the IBS Symptom Severity Score (IBS-SSS), from a moderate severity baseline of 270.
Market Challenges Analysis:
High Treatment Costs and Limited Reimbursement Support:
One of the major challenges in the irritable bowel syndrome (IBS) treatment market is the high cost of advanced therapies and limited insurance coverage in several regions. Many patients struggle to afford long-term medications, probiotics, and alternative therapies required for symptom management. It creates a barrier to access, especially in low- and middle-income countries where healthcare budgets remain constrained. Reimbursement gaps for IBS treatments further restrict adoption, slowing market penetration of new products. The financial burden on patients reduces adherence and limits consistent treatment outcomes. This cost challenge continues to affect both patients and healthcare providers.
Complex Diagnosis and Variability in Treatment Outcomes:
Another challenge is the complexity of diagnosing IBS, which often overlaps with other gastrointestinal disorders. Lack of clear biomarkers makes diagnosis heavily reliant on symptom assessment and exclusion processes. It increases the risk of delayed treatment or misdiagnosis, reducing patient trust in available therapies. Treatment outcomes also vary significantly among patients due to differences in physiology, lifestyle, and gut microbiome. The absence of a universal treatment approach complicates therapy selection for physicians and patients. This variability remains a hurdle for the irritable bowel syndrome IBS treatment market in achieving consistent clinical success.
Market Opportunities:
Expansion of Novel Therapeutics and Microbiome-Based Solutions:
The irritable bowel syndrome (IBS) treatment market presents strong opportunities through the development of innovative therapeutics and microbiome-based interventions. Pharmaceutical companies are investing in next-generation drugs, probiotics, and biologics that target root causes rather than just symptoms. It creates pathways for more effective and personalized care, which increases patient adoption. Growing research into gut-brain interactions and microbiota modulation opens new treatment avenues. Partnerships between biotech firms and research institutes further accelerate product pipelines. This opportunity strengthens market growth by aligning with the rising demand for advanced and holistic solutions.
Growth Potential in Emerging Economies and Digital Health Integration:
Expanding healthcare infrastructure and growing awareness in emerging markets create untapped potential for IBS treatments. Rising disposable incomes and government focus on digestive health enhance access to therapies in these regions. It also benefits from the integration of digital health tools such as symptom-tracking apps and telemedicine platforms. These technologies improve disease management and broaden patient engagement. Pharmaceutical companies exploring localized products and affordable options can capture significant demand. This opportunity positions the irritable bowel syndrome IBS treatment market for broader geographic expansion and stronger patient-centric approaches.
Market Segmentation Analysis:
By Type:
The irritable bowel syndrome (IBS) treatment market is segmented into IBS with constipation (IBS-C), IBS with diarrhea (IBS-D), mixed IBS (IBS-M), and unsubtyped IBS. IBS-C and IBS-D dominate due to their high prevalence and availability of targeted therapies. It is supported by the introduction of advanced drugs addressing specific symptoms. Mixed IBS is gaining attention as patients present overlapping symptoms requiring combination therapies. Unsubtyped IBS shows slower growth due to limited diagnostic clarity but remains relevant in broader treatment adoption.
- For Instance, Ardelyx received FDA approval for IBSRELA (tenapanor) in September 2019, following pivotal Phase 3 trials that included a study with 620 adult IBS-C patients.
By Drug:
The market includes antispasmodics, laxatives, anti-diarrheal agents, antidepressants, probiotics, and others. Antispasmodics and laxatives hold a significant share due to frequent prescriptions for symptom relief. It is influenced by increasing demand for probiotics, which offer natural gut balance and fewer side effects. Anti-diarrheal drugs remain essential for IBS-D, while antidepressants are used for cases linked to psychological stress. Growing R&D in biologics and microbiome-based therapies expands opportunities in this segment.
- For Instance, in August 2020, Seres Therapeutics announced positive topline results from its Phase III ECOSPOR III study of the microbiome therapeutic SER-109 in 182 patients with recurrent C.
By Distribution Channel:
Distribution channels include hospital pharmacies, retail pharmacies, and online pharmacies. Hospital pharmacies lead due to strong patient reliance on prescribed medications and direct specialist access. Retail pharmacies remain vital with wide drug availability and consumer preference for convenience. It is supported by the rapid rise of online pharmacies, offering doorstep delivery and wider drug choices. E-commerce adoption in healthcare is strengthening this channel’s growth, especially in emerging economies.
Segmentations:
By Type:
- IBS with Constipation (IBS-C)
- IBS with Diarrhea (IBS-D)
- Mixed IBS (IBS-M)
- Unsubtyped IBS
By Drug:
- Antispasmodics
- Laxatives
- Anti-Diarrheal Agents
- Antidepressants
- Probiotics
- Others
By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America holds 42% market share in the irritable bowel syndrome (IBS) treatment market, supported by advanced healthcare systems and high awareness levels. The region benefits from strong adoption of innovative therapies, favorable regulatory approvals, and robust pharmaceutical presence. It is driven by early diagnosis, access to specialized gastroenterologists, and widespread insurance coverage. The U.S. dominates the regional market, while Canada shows steady uptake of advanced treatment methods. Lifestyle changes and stress-related conditions further contribute to rising IBS cases, increasing demand for treatment. Research collaborations and patient support programs continue to strengthen the regional outlook.
Europe:
Europe accounts for 29% market share in the irritable bowel syndrome IBS treatment market, supported by extensive research activities and favorable reimbursement frameworks. Strong healthcare infrastructure and government focus on gastrointestinal health contribute to consistent demand. It is driven by clinical studies, patient awareness campaigns, and availability of advanced diagnostic tools. The U.K., Germany, and France remain key contributors, with high adoption of both pharmaceutical and non-pharmacological therapies. Growing focus on microbiome research in European institutes supports innovation. The region also benefits from strong collaboration between healthcare providers and research organizations to advance treatment solutions.
Asia-Pacific:
Asia-Pacific holds 21% market share in the irritable bowel syndrome IBS treatment market, driven by rising healthcare access and increasing diagnosis rates. Countries such as China, India, and Japan play a central role in regional growth. It is supported by government healthcare initiatives, expanding pharmaceutical industry presence, and growing disposable incomes. Changing dietary habits, urban stress, and higher awareness of gastrointestinal disorders fuel patient demand. Multinational companies are expanding their presence in the region, supported by local partnerships. The regional market is expected to experience strong momentum as investments in healthcare infrastructure continue to increase.
Key Player Analysis:
- Ironwood Pharmaceuticals, Inc.
- Astellas Pharma, Inc.
- Allergan
- Takeda Pharmaceutical Company Limited
- Sanofi S.A.
- AstraZeneca
- Sebela Pharmaceuticals Inc.
- Synthetic Biologics, Inc.
- Bausch Health
- Ardelyx
Competitive Analysis:
The irritable bowel syndrome (IBS) treatment market is highly competitive, with pharmaceutical companies focusing on innovative product development and expansion strategies. Key players include Ironwood Pharmaceuticals, Inc., Astellas Pharma, Inc., Allergan, Takeda Pharmaceutical Company Limited, Sanofi S.A., AstraZeneca, Sebela Pharmaceuticals Inc., and Synthetic Biologics, Inc. These companies invest heavily in research and development to introduce novel therapies targeting specific IBS subtypes. It is shaped by strategic collaborations, licensing agreements, and acquisitions that strengthen portfolios and expand global reach. Companies are also diversifying product lines by integrating probiotics, biologics, and non-pharmacological solutions to meet growing patient demand. Strong emphasis on clinical trials and regulatory approvals ensures consistent pipeline progress. Competitive intensity is expected to remain strong, driven by innovation, regional expansion, and partnerships across healthcare ecosystems.
Recent Developments:
- In August 2025, Ironwood Pharmaceuticals reported second quarter results showing LINZESS U.S. net sales of $248 million and announced plans to align with the FDA on the confirmatory Phase 3 trial design for apraglutide in the fourth quarter.
- In September 2025, Astellas Pharma will officially establish a joint venture with YASKAWA Electric Corporation for cell therapy manufacturing, with a launch capital of $30 million.
- In September 2025, Allergan Aesthetics, an AbbVie company, introduced a new chapter for BOTOX Cosmetic titled "The One. Only. Campaign" showcasing real consumer stories.
Report Coverage:
The research report offers an in-depth analysis based on Type, Drug, Distribution Channel and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The irritable bowel syndrome (IBS) treatment market will witness stronger adoption of personalized medicine tailored to patient profiles.
- Pharmaceutical companies will expand pipelines with novel drugs, probiotics, and biologics targeting root causes.
- Digital health platforms will play a growing role in symptom tracking and patient engagement.
- Healthcare providers will integrate dietary management and psychological therapies with pharmacological approaches.
- Emerging economies will see wider access to IBS treatments due to rising healthcare investments.
- Research into the gut-brain axis and microbiome will drive innovative therapeutic development.
- Reimbursement frameworks are expected to improve, enhancing patient access to advanced treatments.
- Strategic collaborations between biotech firms and research institutes will accelerate clinical trials.
- Non-pharmacological interventions such as cognitive behavioral therapy will gain broader recognition.
- The irritable bowel syndrome IBS treatment market will strengthen its focus on patient-centric solutions and holistic care.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of IBS and Lifestyle-Related Disorders
Increasing global incidence of IBS, driven by lifestyle changes, poor dietary habits, and higher stress levels, is leading to greater diagnosis rates and a larger patient pool requiring ongoing treatment.
Growing Demand for Targeted and Symptom-Specific Therapies
Patients and healthcare providers are seeking therapies that address multiple IBS symptoms such as abdominal pain, constipation, and diarrhea, prompting pharmaceutical innovation and the introduction of advanced drugs, probiotics, and supplements.
Expansion of Healthcare Infrastructure and Access to Diagnosis
Improved healthcare systems and greater availability of advanced diagnostic tools in both developed and emerging markets are enabling earlier and more accurate IBS diagnosis, increasing the number of patients receiving timely and effective treatment.
Pharmaceutical Innovation and R&D Investments
Major pharmaceutical companies are investing heavily in research and development to create novel drugs, biologics, and microbiome-based therapies, expanding the range of effective treatment options and driving market growth.
Integration of Digital Health and Non-Pharmacological Approaches
The adoption of digital health solutions, such as symptom-tracking apps and telemedicine, along with non-drug therapies like cognitive behavioral therapy, is enhancing disease management and broadening patient engagement, supporting overall market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Irritable Bowel Syndrome (IBS) Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Irritable Bowel Syndrome (IBS) Treatment Market projected to grow between 2024 and 2032?
Which Irritable Bowel Syndrome (IBS) Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Irritable Bowel Syndrome (IBS) Treatment Market?
Who are the leading companies in the Irritable Bowel Syndrome (IBS) Treatment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug
- 1.2.1 Antispasmodics
- 1.2.2 Laxatives
- 1.2.3 Anti-Diarrheal Agents
- 1.2.4 Antidepressants
- 1.2.5 Probiotics
- 1.2.6 Others
- 1.3 By Type
- 1.3.1 IBS with Constipation (IBS-C)
- 1.3.2 IBS with Diarrhea (IBS-D)
- 1.3.3 Mixed IBS (IBS-M)
- 1.3.4 Unsubtyped IBS
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.79 billion → 2032: USD 7.33 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Irritable Bowel Syndrome Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Irritable Bowel Syndrome Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Irritable Bowel Syndrome Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Irritable Bowel Syndrome Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Irritable Bowel Syndrome Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Irritable Bowel Syndrome Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Irritable Bowel Syndrome Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Irritable Bowel Syndrome Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.79 billion → 2032: USD 7.33 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Irritable Bowel Syndrome Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Antispasmodics
- 12.3.7.2 Laxatives
- 12.3.7.3 Anti-Diarrheal Agents
- 12.3.7.4 Antidepressants
- 12.3.7.5 Probiotics
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 IBS with Constipation (IBS-C)
- 12.4.7.2 IBS with Diarrhea (IBS-D)
- 12.4.7.3 Mixed IBS (IBS-M)
- 12.4.7.4 Unsubtyped IBS
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Irritable Bowel Syndrome Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Irritable Bowel Syndrome Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Irritable Bowel Syndrome Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Ironwood Pharmaceuticals, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Astellas Pharma, Inc.
- 17.4 Allergan
- 17.5 Takeda Pharmaceutical Company Limited
- 17.6 Sanofi S.A.
- 17.7 AstraZeneca
- 17.8 Sebela Pharmaceuticals Inc.
- 17.9 Synthetic Biologics, Inc.
- 17.10 Bausch Health
- 17.11 Ardelyx
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

