
Market Overview:
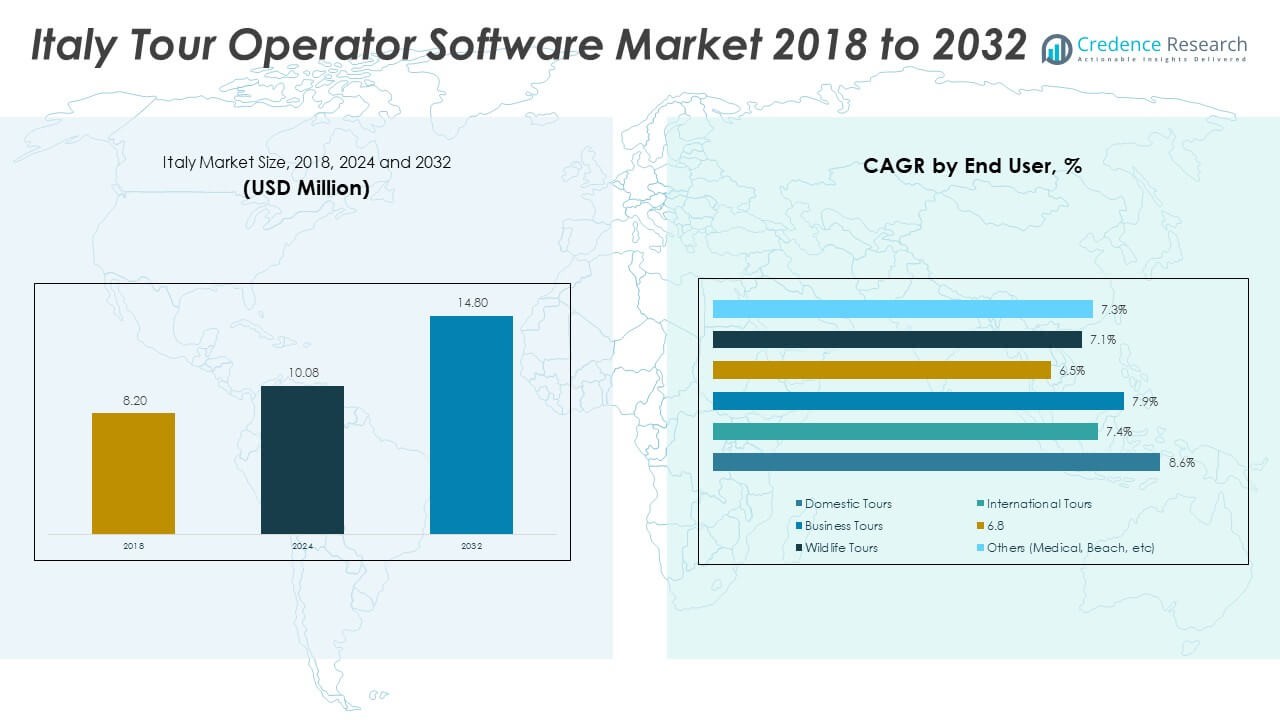
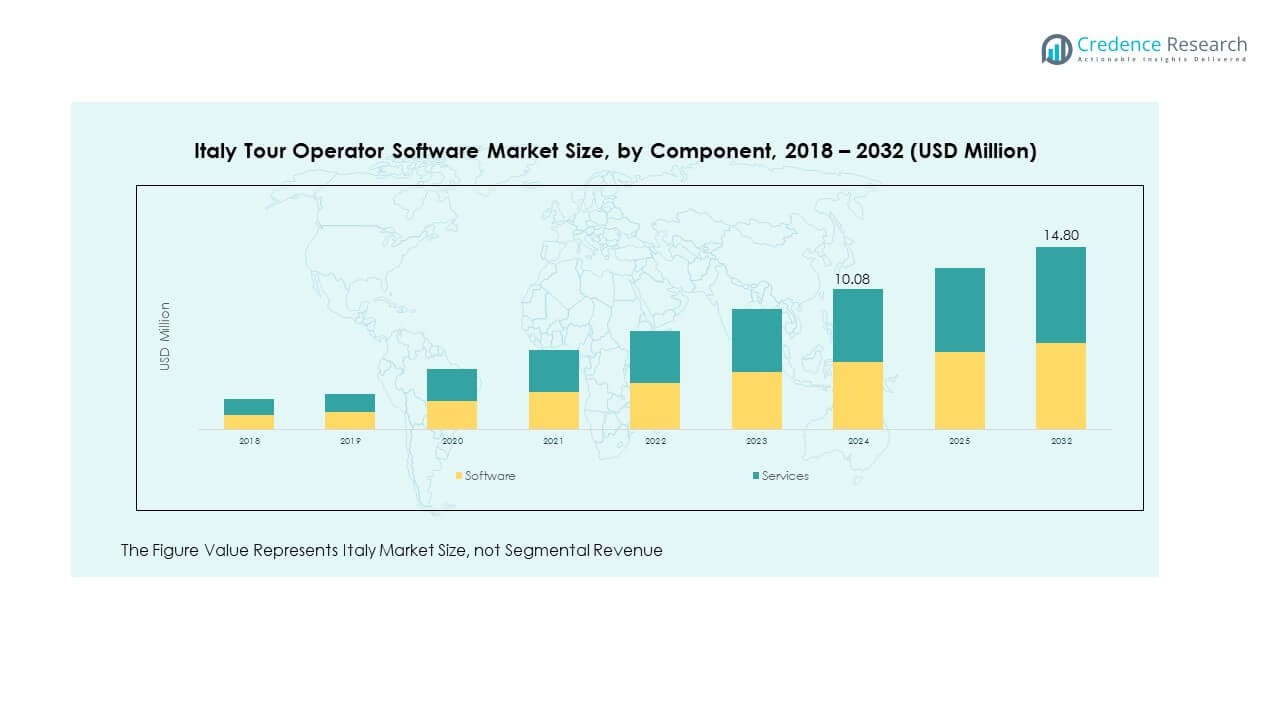
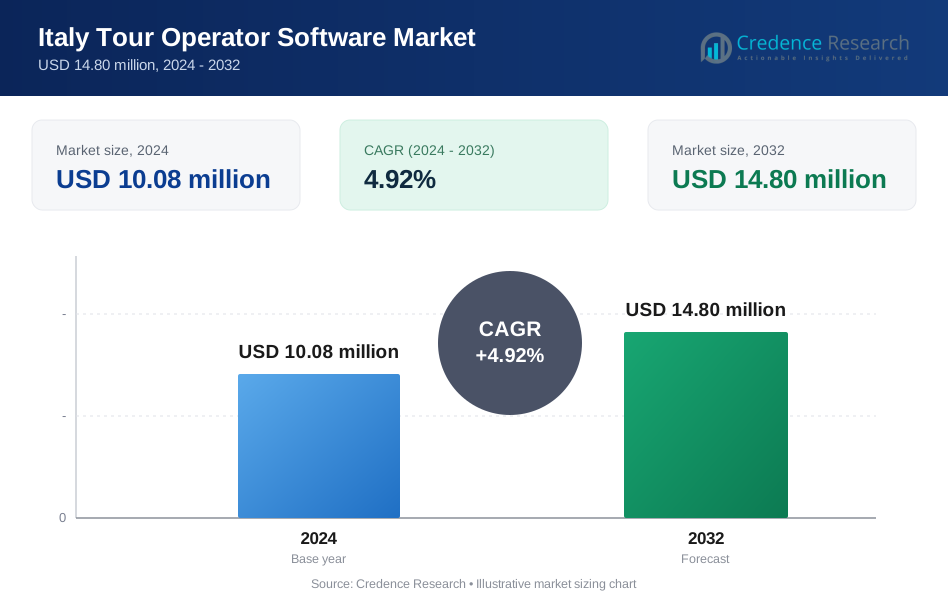
The Italy Tour Operator Software Market size was valued at USD 8.20 million in 2018 to USD 10.08 million in 2024 and is anticipated to reach USD 14.80 million by 2032, at a CAGR of 4.92% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Italy Tour Operator Software Market Size 2024 | USD 10.08 Million |
| Italy Tour Operator Software Market, CAGR | 4.92% |
| Italy Tour Operator Software Market Size 2032 | USD 14.80 Million |
The market is driven by Italy’s strong tourism industry, where both domestic and international operators demand tools for itinerary planning, booking, and payment integration. Companies are investing in digital solutions to increase efficiency, reduce operational costs, and deliver customized travel packages. Demand for real-time data, mobile accessibility, and AI-based personalization is rising as tour operators strive to attract tech-savvy customers and strengthen competitiveness in a crowded landscape.
Geographically, the market shows stronger adoption in Italy’s northern and central regions, where tourism infrastructure and inbound visitor traffic remain high. Southern Italy and islands such as Sicily and Sardinia are emerging growth areas due to rising international arrivals and efforts to digitalize smaller tour companies. While Europe leads in technology adoption, Asia-Pacific is fast catching up with digital tourism innovations that can inspire future strategies for Italian operators.
Market Insights:
- The Italy Tour Operator Software Market was valued at USD 8.20 million in 2018, reached USD 10.08 million in 2024, and is expected to hit USD 14.80 million by 2032, registering a CAGR of 4.92%.
- Europe (38%), North America (27%), and Asia Pacific (22%) held the top three regional shares in 2024, supported by advanced tourism infrastructure, digital adoption, and strong inbound traffic.
- Asia Pacific (22%) is the fastest-growing region, driven by rising tourism flows, increasing digital penetration, and growing cross-border travel demand.
- In 2024, software accounted for 63% of the Italy Tour Operator Software Market, driven by automation, personalization, and cloud adoption.
- Services contributed 37% of the market share, supported by integration, training, and support needs among small and mid-sized operators.
Market Drivers:
Rising Tourism Demand and Focus on Digital Transformation:
The Italy Tour Operator Software Market benefits from strong tourism demand that compels companies to adopt advanced software. Operators need platforms that simplify bookings, payments, and resource allocation while enhancing customer experience. It is pushing firms to embrace automation, mobile compatibility, and AI-driven personalization to stay competitive. Tour operators now rely on cloud solutions for improved scalability and integration with other systems. This demand strengthens adoption rates and helps businesses cater to diverse customer needs. Growing dependence on digital ecosystems further drives innovation and adoption.
- For instance, More than 33,000 tourism enterprises have joined the Tourism Digital Hub (TDH), a cloud-based ecosystem launched under Italy’s National Recovery and Resilience Plan, facilitating seamless system integration and scalability. This digital adoption supports diverse customer needs and pushes innovation across the sector, fostered by government-backed digital infrastructure projects like "Wi-Fi by Italia.it".
Need for Operational Efficiency and Cost Optimization:
Operational efficiency remains a core driver for adoption of tour operator software across Italy. Companies seek tools that streamline workflows, reduce manual errors, and improve profitability. It provides real-time insights into bookings, cancellations, and payments, helping businesses manage resources effectively. Tour operators face pressure to deliver cost-effective services without compromising quality, creating a strong need for automation. The integration of CRM modules enhances client retention and upselling opportunities. Firms leverage data analytics for smarter decision-making, boosting competitiveness in a dynamic market. Efficiency-driven strategies are propelling software demand.
- For instance, real-time dashboards for bookings, cancellations, and payments are widely used, helping operators allocate resources effectively. Similarly, CRM integrations are commonly used to enhance upselling and customer retention.
Growing Consumer Expectations for Personalized Travel Services:
Customers increasingly expect customized itineraries, flexible bookings, and real-time support when planning tours. The Italy Tour Operator Software Market addresses this by integrating AI tools that recommend packages and optimize schedules. It enhances engagement through personalized experiences that build loyalty. Software platforms now feature chatbots, automated assistance, and dynamic pricing tools to meet evolving needs. Operators also benefit from social media integration, which influences buying decisions. This push for personalization is reshaping competitive strategies among players. Firms that embrace customization achieve higher customer satisfaction and repeat bookings.
Impact of Rising Online Travel Distribution Channels:
Online platforms and OTAs are reshaping tour distribution across Italy. Operators require software that integrates seamlessly with multiple distribution channels. The Italy Tour Operator Software Market is responding by enabling connectivity with global travel platforms. It helps operators expand reach, manage inventory in real time, and capture wider customer segments. Online bookings dominate consumer behavior, driving operators to rely on software with advanced channel management. The rise of multi-device bookings further strengthens the adoption of mobile-compatible solutions. Software-enabled distribution boosts efficiency and ensures stronger visibility for tour providers.
Market Trends:
Integration of Artificial Intelligence and Automation in Tourism Operations:
AI and automation are reshaping the Italy Tour Operator Software Market by improving predictive analytics, itinerary planning, and customer support. It enables operators to process large datasets, identify travel preferences, and deliver tailored recommendations. Automation minimizes human errors in reservations, payments, and compliance tasks. Companies that adopt AI-powered solutions improve efficiency and customer satisfaction. The focus on seamless, intelligent platforms highlights the shift towards smart tourism management. This trend ensures greater scalability and data-driven strategies. Operators increasingly view AI as a critical enabler of competitiveness.
- For instance, Operators recognize AI as critical to maintaining competitiveness, with targeted use cases including machine learning for customer preferences, chatbot communications, and compliance monitoring.
Adoption of Cloud-Based Solutions for Scalability and Mobility:
Cloud-based software is driving flexibility and scalability for tour operators across Italy. The Italy Tour Operator Software Market reflects this by offering platforms accessible from any location or device. It allows operators to manage operations remotely, enhance collaboration, and reduce infrastructure costs. Cloud systems integrate smoothly with third-party applications, ensuring better connectivity and functionality. This trend enables faster upgrades, improved data security, and real-time analytics for decision-making. Operators using cloud platforms gain competitive advantages by being agile and customer-focused. Cloud adoption continues to rise across small and large enterprises.
- For instance, Italy’s Tourism Digital Hub serves as a cloud infrastructure backbone, with over 33,000 enterprises integrated by mid-2025. Such platforms allow remote management, third-party app integration, and real-time analytics, increasing operator agility and customer responsiveness.
Rising Use of Mobile Applications for Traveler Engagement:
Mobile solutions are increasingly central to customer engagement in tourism. The Italy Tour Operator Software Market shows a surge in applications enabling real-time updates, digital itineraries, and mobile payments. It provides operators with a direct communication channel to enhance customer satisfaction. Mobile-first strategies help capture younger demographics that prefer convenience and flexibility. Features such as instant notifications, map integration, and digital tickets add value for travelers. The growing smartphone penetration in Italy strengthens this trend. Operators leveraging mobile solutions stand out in a competitive environment.
Growing Focus on Data Security and Regulatory Compliance:
Data protection has become a crucial priority for operators adopting digital platforms. The Italy Tour Operator Software Market emphasizes compliance with GDPR and other local regulations. It requires secure handling of customer data, payments, and travel information. Operators demand software with strong encryption, fraud detection, and secure cloud storage. The rising threat of cyberattacks accelerates investments in robust security solutions. Vendors are focusing on certifications and compliance frameworks to build trust. Security-enabled software enhances credibility among both corporate and retail clients. Compliance focus is shaping future product strategies across vendors.
Market Challenges Analysis:
High Implementation Costs and Limited Digital Readiness of Small Operators:
The Italy Tour Operator Software Market faces challenges from high upfront costs for software implementation. Small and mid-sized operators often lack resources to invest in advanced platforms. It slows digital adoption despite growing demand. Training requirements, integration complexities, and maintenance expenses add to the burden. Limited awareness of long-term cost benefits also hinders acceptance. Vendors face pressure to provide affordable, modular solutions. High entry costs create a divide between larger established operators and smaller players. This financial barrier restricts market expansion in cost-sensitive segments.
Competition from Global OTAs and Fragmented Local Market:
Global online travel agencies dominate the market with extensive digital ecosystems. The Italy Tour Operator Software Market competes against such platforms, which often overshadow local operators. It creates pressure for differentiation, making it difficult for smaller players to sustain growth. Fragmentation in the local industry further complicates scalability. Many operators still rely on traditional methods, reducing digital readiness. Strong competition limits pricing flexibility and impacts margins. Local vendors must focus on specialized features to retain competitiveness. This challenge continues to shape strategic approaches in the Italian market.
Market Opportunities:
Expansion of Niche Travel Segments and Custom Packages:
The Italy Tour Operator Software Market has opportunities in niche travel categories such as cultural, eco, and adventure tours. Operators can use software to create customized itineraries that appeal to specialized customer groups. It supports tailored experiences, attracting younger and experience-driven travelers. Integration of virtual reality and AI further strengthens personalization. Vendors providing solutions for niche markets can gain competitive advantages. Operators that embrace unique travel experiences will see higher margins. The opportunity lies in adapting platforms to deliver curated offerings for growing demand segments.
Rising International Tourism and Cross-Border Integration:
International arrivals in Italy present a significant growth avenue for software providers. The Italy Tour Operator Software Market benefits from cross-border collaborations that enhance multi-language, multi-currency, and tax-compliant features. It supports operators catering to global customers while ensuring compliance with international standards. Vendors can expand footprints by offering integrated booking and payment solutions. The growth of multi-destination packages boosts the demand for advanced platforms. International connectivity increases opportunities for innovation in tour design. This expansion reinforces Italy’s role as a global tourism hub, enhancing prospects for technology adoption.
Market Segmentation Analysis:
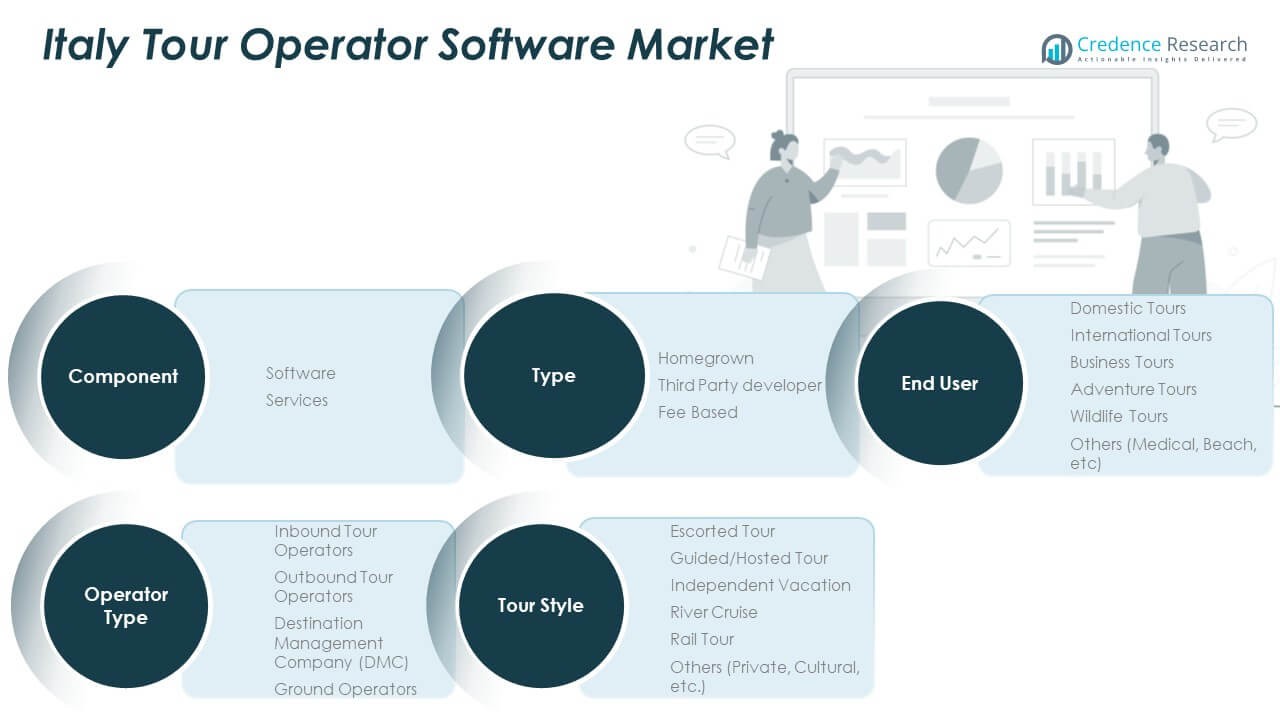
By Type
The Italy Tour Operator Software Market is segmented into homegrown, third-party developer, and fee-based solutions. Homegrown platforms serve localized operators with tailored features, while third-party developers provide advanced tools and scalability. Fee-based models gain traction among mid and large operators seeking continuous support and upgrades. It reflects varied adoption patterns across operator sizes and budgets.
- For instance, homegrown platforms for tailored local needs, third-party solutions for scalability and broad features, and fee-based subscription models favored by mid-to-large operators balancing support and cost predictability.
By Component
By component, the market divides into software and services. Software dominates due to its role in automating bookings, payments, and customer management. Services support integration, training, and technical assistance, which are crucial for small and mid-sized operators. It ensures long-term adoption and smooth system performance.
- For instance, Services, including integration assistance, training, and ongoing tech support, underpin smooth adoption, particularly for small and mid-sized operators lacking internal IT staff. This ecosystem approach ensures sustained performance and user satisfaction.
By Operator Type
The market includes inbound tour operators, outbound tour operators, destination management companies (DMCs), and ground operators. Inbound operators lead growth with Italy’s strong tourist inflows. Outbound operators expand global reach, while DMCs manage complex, multi-service itineraries. Ground operators focus on local transport and logistics. It highlights the software’s role across diverse business models.
By Tour Style
Tour styles include escorted tours, guided or hosted tours, independent vacations, river cruises, rail tours, and others such as cultural or private tours. Escorted and guided tours dominate due to heritage tourism demand. Independent vacations and rail tours attract younger travelers seeking flexibility. It diversifies market opportunities.
By End User
End-user categories include domestic tours, international tours, business tours, adventure tours, wildlife tours, and others. Domestic and international tours lead adoption, supported by steady inbound and outbound traffic. Business travel software gains demand from corporates, while adventure and wildlife tours grow among niche customers. It ensures a balanced market structure across applications.
Segmentation:
By Type
- Homegrown
- Third Party Developer
- Fee Based
By Component
- Software
- Services
By Operator Type
- Inbound Tour Operators
- Outbound Tour Operators
- Destination Management Company (DMC)
- Ground Operators
By Tour Style
- Escorted Tour
- Guided/Hosted Tour
- Independent Vacation
- River Cruise
- Rail Tour
- Others (Private, Cultural, etc.)
By End User
- Domestic Tours
- International Tours
- Business Tours
- Adventure Tours
- Wildlife Tours
- Others
Regional Analysis:
Northern Italy – 38% Share
Northern Italy holds the largest 38% share of the Italy Tour Operator Software Market, supported by advanced infrastructure, strong cultural hubs, and business travel centers. Regions such as Lombardy, Veneto, and Emilia-Romagna lead adoption, driven by high inbound and domestic tourist volumes. It benefits from larger operators investing in cloud platforms, automation, and AI-driven personalization. Cross-border traffic with neighboring countries also boosts demand for multi-language and multi-currency features. Northern Italy shows strong digital maturity, making it the most advanced regional market.
Central Italy – 35% Share
Central Italy accounts for 35% of the Italy Tour Operator Software Market, with Tuscany, Lazio, and Umbria driving growth. Rome and Florence act as international gateways, attracting large volumes of inbound visitors. It demonstrates steady demand for escorted and cultural tours, requiring advanced itinerary and booking tools. Operators focus on mobile-first adoption and compliance with data protection regulations. The region benefits from strong European and North American arrivals, encouraging robust investments in automation. Central Italy remains a crucial market with consistent adoption trends.
Southern Italy and Islands – 27% Share
Southern Italy and the islands hold 27% of the Italy Tour Operator Software Market, emerging as a fast-developing segment. Sicily, Sardinia, and Campania are seeing rising digital adoption among smaller operators. Growth is fueled by international arrivals and demand for niche offerings such as adventure, cultural, and wildlife tours. Independent and guided travel styles dominate, supported by rising demand for authentic experiences. Operators here favor modular and affordable solutions to overcome budget constraints. This region reflects strong potential as it aligns with digital transformation efforts.
Key Player Analysis:
- AppyPilgrim SRL
- ai
- Travelomatix
- Tourism Innovation Lab S.r.l.
- Raro Discovery S.r.l. Società Benefit
- TripMe
- Cityfy
- La Creature
Competitive Analysis:
The Italy Tour Operator Software Market features competition among local innovators and global providers. Players compete on product customization, integration, pricing models, and customer support. It shows strong activity from companies offering AI-driven personalization, mobile-first platforms, and cloud-based systems. Local firms leverage cultural understanding and niche targeting, while international developers introduce scalable solutions with global compatibility. Competition intensifies as operators demand secure, efficient, and flexible tools to manage bookings and customer engagement. Strategic collaborations, partnerships, and product upgrades shape the competitive edge. Vendors that combine affordability, functionality, and compliance remain well-positioned.
Recent Developments:
- In May 2024, AppyPilgrim SRL announced the launch of its full-stack AI and Web3-powered platform dedicated to spiritual and sustainable travel. Established in Rome in 2024, the company aims to unify the often fragmented experience of organizing spiritual journeys by enabling personalized pilgrimages, seamless bookings, and donations through a single digital ecosystem.
- In July 2025, Hubcore.ai entered a notable strategic partnership with Italcares and Destination Italia, officially unveiled during a major medical and wellness tourism event at Sapienza University of Rome. This collaboration resulted in the launch of the Italcares online booking platform, developed using Hubcore.ai's advanced AI technology. The partnership positions Italy as a leader in medical and wellness tourism, offering a transparent, multilingual digital ecosystem connecting travelers with healthcare and wellness providers.
- As of July 2025, Tourism Innovation Lab S.r.l. continues to develop mobile-first software solutions for the tourism market, emphasizing direct connections between tourists, accommodation providers, and territories. The company, founded by Green Consulting, takes a strong 'disintermediation' approach-helping smaller tourism players build value without the need for large intermediaries, and supporting digital transformation efforts for hotels and destinations across Italy.
- Founded in 2023 and based in Milan, Raro Discovery S.r.l. operates both as a licensed luxury travel agency and an innovator in travel NFTs. In 2024, the company advanced its development of NFT-based digital identities for the tour operator sector, significantly enhancing the personalization, authenticity, and potential for resale or transfer of travel experiences.
Report Coverage:
The research report offers an in-depth analysis based on type, component, operator type, tour style, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for AI-driven personalization will expand across Italian tour operators.
- Cloud-based adoption will rise due to scalability and cost efficiency.
- Inbound operators will continue to dominate software usage.
- Independent vacations and rail tours will gain momentum among younger travelers.
- Data security and compliance will remain a central focus for vendors.
- Domestic and international tours will drive software adoption steadily.
- Small operators will increasingly adopt modular and affordable platforms.
- Mobile-first applications will define customer engagement strategies.
- Niche segments like cultural and adventure tours will create new revenue streams.
-
Partnerships with global OTAs and local agencies will shape competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation in Tourism
Italy’s tour operators are rapidly adopting digital platforms to streamline bookings, payments, and itinerary management, driven by the need for efficiency and enhanced customer experience. Government-backed initiatives like the Tourism Digital Hub are accelerating this shift, enabling seamless integration and scalability.
Rising Demand for Personalization and AI Integration
Operators are leveraging AI-driven tools to offer personalized travel packages, dynamic pricing, and real-time support, meeting the expectations of tech-savvy travelers. This trend is boosting software adoption as companies seek to differentiate through tailored experiences and improved customer engagement.
Operational Efficiency and Cost Optimization
Tour operator software automates workflows, reduces manual errors, and provides real-time analytics, helping businesses optimize resources and control costs. The need for profitability and streamlined operations is a key motivator for both large and small operators to invest in advanced solutions.
Growth of Online and Mobile Distribution Channels
The dominance of online travel agencies and the rise of mobile-first consumer behavior are pushing operators to adopt software that integrates with multiple digital channels. This expands market reach, supports multi-device bookings, and ensures operators remain competitive in a rapidly evolving landscape.
Expansion of Niche and International Travel Segments
Increasing international arrivals and the popularity of niche travel experiences such as cultural, adventure, and wellness tours are creating new opportunities for software providers. Platforms that support multi-language, multi-currency, and compliance features are in high demand to cater to diverse and global customer bases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Italy Tour Operator Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Italy Tour Operator Software Market projected to grow between 2024 and 2032?
Which Italy Tour Operator Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Italy Tour Operator Software Market?
Who are the leading companies in the Italy Tour Operator Software Market?
Which region commanded the largest share of the Italy Tour Operator Software Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Homegrown
- 1.2.2 Third Party Developer
- 1.2.3 Fee Based
- 1.3 By Component
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Tour Style
- 1.4.1 Escorted Tour
- 1.4.2 Guided/Hosted Tour
- 1.4.3 Independent Vacation
- 1.4.4 River Cruise
- 1.4.5 Rail Tour
- 1.4.6 Others (Private, Cultural, etc.)
- 1.5 By Operator Type
- 1.5.1 Inbound Tour Operators
- 1.5.2 Outbound Tour Operators
- 1.5.3 Destination Management Company (DMC)
- 1.5.4 Ground Operators
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10.08 million → 2032: USD 14.80 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Italy Tour Operator Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Italy Tour Operator Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Italy Tour Operator Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Italy Tour Operator Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Italy Tour Operator Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Italy Tour Operator Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Italy Tour Operator Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Italy Tour Operator Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10.08 million → 2032: USD 14.80 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Italy Tour Operator Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Homegrown
- 12.3.6.2 Third Party Developer
- 12.3.6.3 Fee Based
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software
- 12.4.6.2 Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Tour Style - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Escorted Tour
- 12.5.6.2 Guided/Hosted Tour
- 12.5.6.3 Independent Vacation
- 12.5.6.4 River Cruise
- 12.5.6.5 Rail Tour
- 12.5.6.6 Others (Private, Cultural, etc.)
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Operator Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Inbound Tour Operators
- 12.6.6.2 Outbound Tour Operators
- 12.6.6.3 Destination Management Company (DMC)
- 12.6.6.4 Ground Operators
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Italy Tour Operator Software Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Italy Tour Operator Software Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Italy Tour Operator Software Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 AppyPilgrim SRL
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Travelomatix
- 17.4 Tourism Innovation Lab S.r.l.
- 17.5 Raro Discovery S.r.l. Società Benefit
- 17.6 TripMe
- 17.7 Cityfy
- 17.8 La Creature
- 17.9 Hubcore.ai
- 17.10 Tourplan
- 17.11 Softrip
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

