
Market Overview:
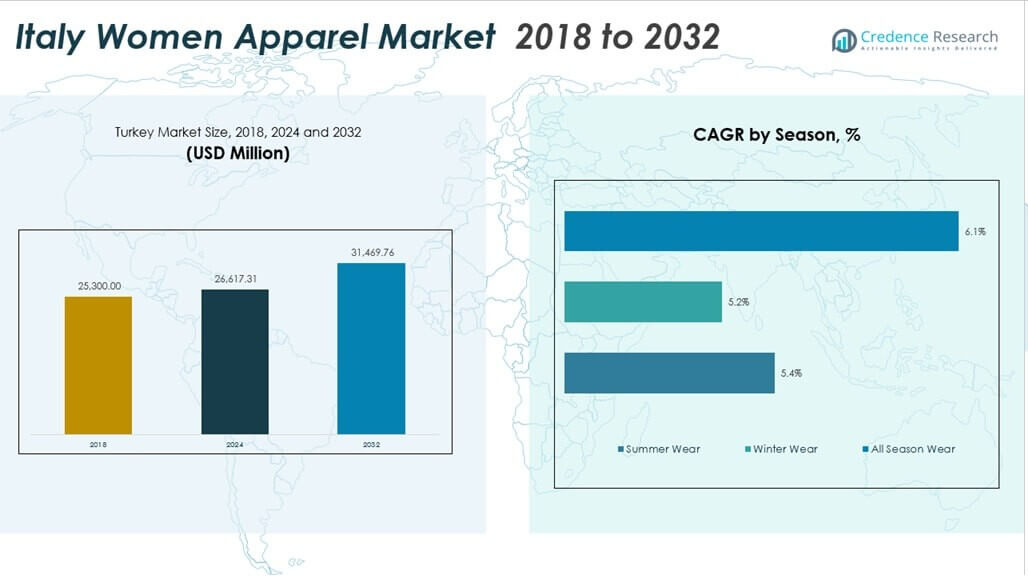
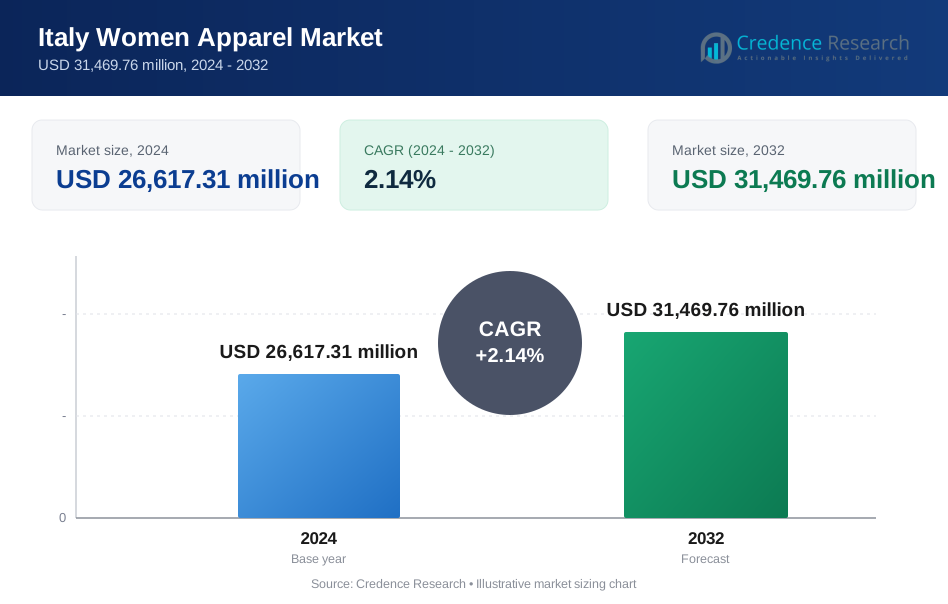
The Italy Women Apparel Market size was valued at USD 25,300.00 million in 2018 to USD 26,617.31 million in 2024 and is anticipated to reach USD 31,469.76 million by 2032, at a CAGR of 2.14% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Italy Women Apparel Market Size 2024 | USD 26,617.31 million |
| Italy Women Apparel Market, CAGR | 2.14% |
| Italy Women Apparel Market Size 2032 | USD 31,469.76 million |
Market Insights:
- The Italy Women Apparel Market was valued at USD 25,300.00 million in 2018, reached USD 26,617.31 million in 2024, and is projected to hit USD 31,469.76 million by 2032, expanding at a CAGR of 2.14%.
- Northern Italy leads with about 45% share due to Milan’s fashion hub role, Central Italy follows with nearly 30% supported by tourism-led demand, while Southern Italy and islands hold close to 25% driven by mass apparel consumption.
- Southern Italy and the islands emerge as the fastest-growing region with around 25% share, supported by urbanization, younger demographics, and rising online apparel adoption.
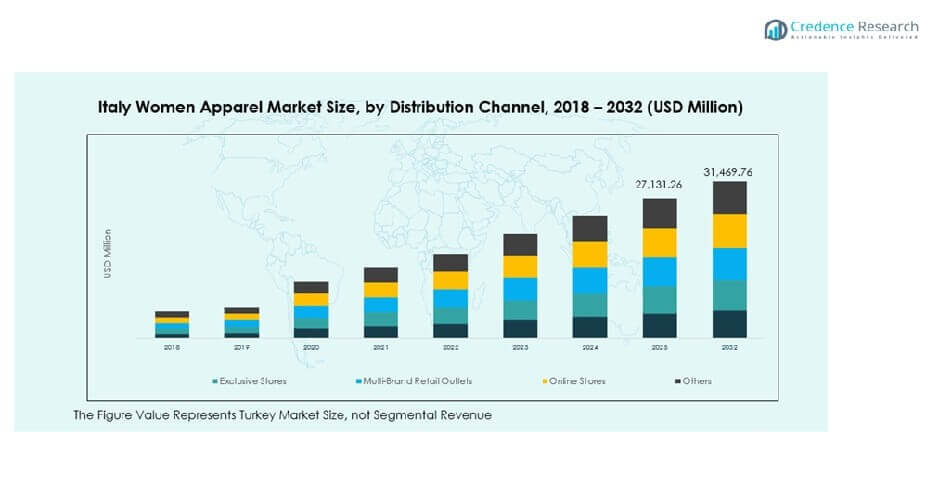
- By distribution channel, exclusive stores account for roughly 35% share, supported by brand control and premium positioning, while multi-brand retail outlets contribute about 30% through variety and price comparison.
- Online stores hold close to 25% share due to convenience and wider access, while other channels represent the remaining 10%, serving localized and niche demand.
Market Drivers:
Strong Consumer Preference For Quality, Fit, And Italian Craftsmanship
The Italy Women Apparel Market benefits from strong demand for quality apparel. Italian consumers value fabric durability and precise tailoring. Brand heritage influences purchase confidence across age groups. Premium craftsmanship supports repeat buying behavior. Local brands retain trust through consistent product standards. Retailers focus on fit-led collections for diverse body profiles. Seasonal launches maintain customer interest year-round. Fashion education shapes informed consumer choices.- For instance, Max Mara operates over 2,300 single-brand stores worldwide, with Italian-made coats remaining a core driver of repeat domestic sales due to long garment lifecycles.
Urban Lifestyle Expansion And Professional Workforce Participation
The Italy Women Apparel Market gains momentum from urban lifestyle growth. Working women seek versatile and polished clothing options. Office wear demand supports structured and formal designs. Hybrid work culture supports smart casual apparel sales. City retail hubs offer wide brand exposure. Time-conscious shoppers prefer reliable fashion labels. Apparel brands respond with capsule wardrobes. Product consistency supports long-term brand loyalty.- For instance, Armani Group reports that its women’s ready-to-wear lines serve professional segments across more than 300 directly operated stores, reinforcing demand for adaptable workwear.
Retail Network Strength And Multi-Channel Accessibility
The Italy Women Apparel Market grows through strong retail coverage. Department stores anchor national apparel distribution. High-street outlets ensure daily consumer visibility. Shopping centers support impulse and planned purchases. E-commerce platforms expand product accessibility nationwide. Digital storefronts support style discovery and size options. Omnichannel strategies improve buying convenience. Integrated logistics strengthen delivery reliability.Cultural Fashion Awareness And Style Consciousness
The Italy Women Apparel Market benefits from deep fashion awareness. Italian culture values personal style and presentation. Media exposure reinforces trend sensitivity among consumers. Fashion weeks influence mainstream apparel adoption. Style-conscious buyers follow designer-led inspirations. Apparel brands translate runway ideas into wearable formats. This behavior sustains consistent wardrobe renewal. Style pride supports steady domestic demand.Market Trends:
Rising Preference For Sustainable And Responsible Apparel Choices
The Italy Women Apparel Market shows a shift toward responsible fashion. Consumers assess material sourcing and production ethics. Natural fabrics gain preference over synthetic blends. Transparency in supply chains builds brand credibility. Labels promote recyclable and low-impact textiles. Ethical branding strengthens emotional buyer connections. Sustainable lines expand across price categories. Conscious fashion shapes long-term market direction.- For instance, Prada Group reports that nylon collections now use regenerated ECONYL® fiber, produced from recycled fishing nets and textile waste. Labels promote recyclable and low-impact textiles.
Growth Of Digital-First Fashion Discovery And Social Commerce
The Italy Women Apparel Market reflects stronger digital engagement. Social platforms shape style awareness and brand visibility. Influencers guide outfit pairing and seasonal trends. Live shopping formats support real-time purchase decisions. Mobile-first browsing drives impulse fashion sales. Brands invest in visual storytelling for engagement. Data tools refine product recommendations. Digital discovery reshapes consumer journeys.- For instance, Gucci’s strategic focus on digital immersion is evident through its pivot to micro-influencer partnerships, which achieved engagement rates of over 7% in 2024, far outpacing traditional celebrity campaigns. This digital-first approach is reinforced by investments in Augmented Reality (AR) storytelling and virtual try-ons to capture a mobile-first audience. While Gucci’s overall revenue saw a 23% decline during its 2024 'brand reset,' its online operations remain a critical pillar, generating over $600 million in annual sales by leveraging social commerce and livestream events to drive impulse luxury purchases.
Expansion Of Casual And Comfort-Oriented Apparel Segments
The Italy Women Apparel Market sees rising demand for comfort-led styles. Relaxed silhouettes gain acceptance in daily wear. Stretch fabrics support movement and flexibility. Consumers favor adaptable clothing for mixed routines. Casual fashion aligns with lifestyle shifts. Brands balance comfort with refined aesthetics. Versatile designs extend usage occasions. This trend supports broader wardrobe integration.Customization And Limited-Edition Capsule Collections Growth
The Italy Women Apparel Market adopts focused product drops. Limited collections create urgency among buyers. Custom sizing options improve fit satisfaction. Personalization strengthens brand differentiation. Small-batch releases reduce excess inventory. Designers test trends through capsules. Consumer feedback guides rapid adjustments. This approach supports agile product strategies.Market Challenges Analysis:
Rising Cost Pressures Across Production And Supply Chains
The Italy Women Apparel Market faces cost management challenges. Raw material prices affect margin stability. Skilled labor costs remain structurally high. Compliance standards raise operational expenses. Smaller brands face pricing pressure from global competitors. Supply disruptions affect seasonal planning cycles. Retailers balance quality with affordability expectations. Cost discipline remains critical for profitability.Intense Competition And Fast-Changing Consumer Preferences
The Italy Women Apparel Market operates within high competition. Global brands increase local market presence. Fast fashion accelerates trend turnover rates. Consumers expect frequent new designs. Brand loyalty weakens under constant choice expansion. Inventory risks rise with demand volatility. Accurate trend forecasting becomes complex. Competitive pressure tests long-term brand positioning.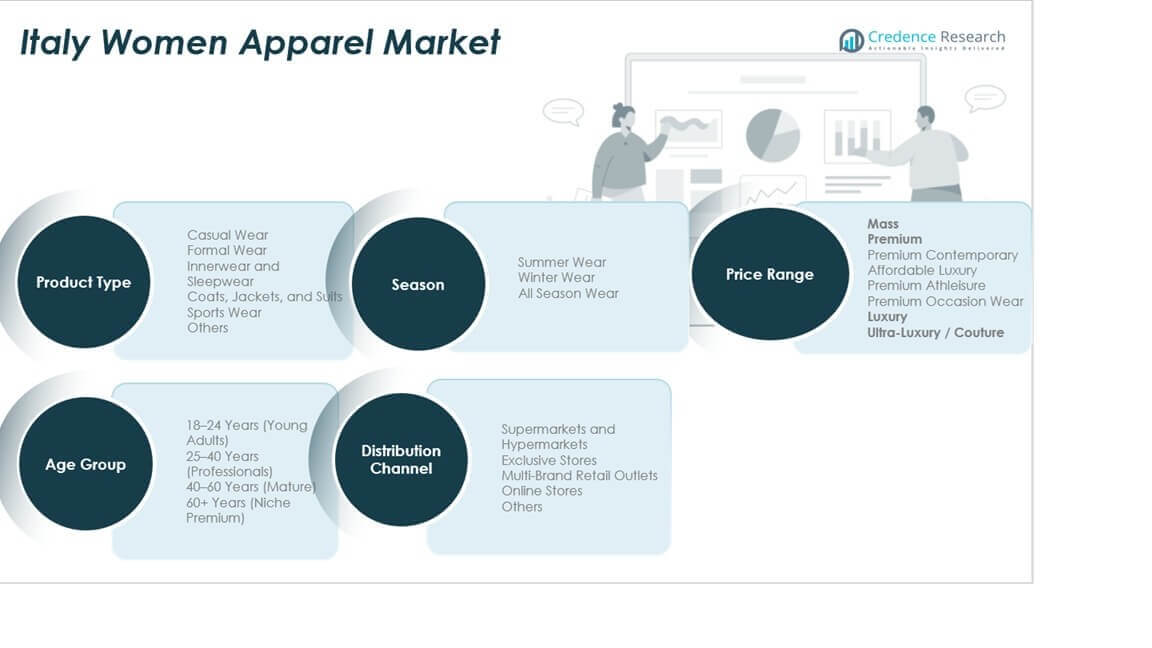
Market Opportunities:
Premiumization And Heritage Brand Storytelling Expansion
The Italy Women Apparel Market holds premium growth potential. Heritage brands leverage Italian design legacy. Story-driven collections attract global consumers. Craft-focused narratives justify premium pricing. Tourists support luxury and artisanal segments. Brand authenticity strengthens international appeal. Export demand supports revenue diversification. Premium focus improves margin resilience.E-Commerce Penetration And Regional Market Expansion
The Italy Women Apparel Market benefits from digital reach growth. Online platforms access smaller regional cities. Digital sizing tools improve buyer confidence. Cross-border sales expand brand exposure. Logistics investments improve delivery speed. Emerging regions gain access to wider assortments. Digital retail supports scalable growth. Online channels unlock new consumer segments.Market Segmentation Analysis:
By Product Type The Italy Women Apparel Market shows balanced demand across core product categories. Casual wear leads daily consumption due to lifestyle versatility. Formal wear supports professional and occasion-based needs. Innerwear and sleepwear maintain stable replacement demand. Coats, jackets, and suits gain relevance during seasonal transitions. Sports wear benefits from fitness awareness and athleisure adoption. Other niche products support fashion-led experimentation and trend testing.- For instance, Calzedonia Group operates more than 5,000 stores globally, with innerwear and hosiery forming a high-frequency purchase segment in Italy. Coats, jackets, and suits gain relevance during seasonal transitions.
- For instance, Moncler generates a significant share of its women’s apparel demand from Asia, primarily through insulated outerwear designed for alpine and urban winter use, supported by specialized thermal material engineering.
Segmentation:
- By Product Type
- Casual Wear
- Formal Wear
- Innerwear and Sleepwear
- Coats, Jackets, and Suits
- Sports Wear
- Others
- By Season
- Summer Wear
- Winter Wear
- All Season Wear
- By Application
- Mass
- Premium
- Premium Contemporary
- Affordable Luxury
- Premium Athleisure
- Premium Occasion Wear
- Luxury
- Ultra-Luxury / Couture
- By Age Group
- 18–24 Years (Young Adults)
- 25–40 Years (Professionals)
- 40–60 Years (Mature)
- 60+ Years (Niche Premium)
- By Distribution Channel
- Supermarkets and Hypermarkets
- Exclusive Stores
- Multi-Brand Retail Outlets
- Online Stores
- Others
Regional Analysis:
Northern Italy Northern Italy holds the largest share of the Italy Women Apparel Market at nearly 45%. Milan anchors fashion design, wholesale trade, and premium retail activity. High disposable income supports strong spending on premium and luxury apparel. Dense urban centers drive frequent fashion purchases. International tourism supports designer and occasion wear demand. Strong retail infrastructure improves brand visibility. This region leads trend adoption and brand launches. Central Italy Central Italy accounts for around 30% of the Italy Women Apparel Market. Rome supports demand through tourism and lifestyle consumption. Consumers favor premium contemporary and occasion wear. Cultural events sustain demand for formal and elegant apparel. Mixed retail formats improve product accessibility. Heritage brands gain steady traction in this region. Balanced demand supports stable sales performance. Southern Italy And Islands Southern Italy and the islands represent close to 25% of the Italy Women Apparel Market. Price sensitivity shapes purchasing behavior across cities. Mass and mid-range apparel dominate volume sales. Urbanization supports gradual fashion adoption. Younger consumers drive casual and trend-focused demand. Online retail improves access to wider assortments. This region shows steady long-term growth potential.Key Player Analysis:
Competitive Analysis:
The Italy Women Apparel Market features intense competition across luxury, premium, and mass segments. Global fashion houses coexist with strong domestic brands. Leading players rely on design leadership, brand heritage, and retail depth. Product differentiation centers on fabric quality, fit, and seasonal relevance. Exclusive stores strengthen brand control and customer loyalty. Multi-brand outlets expand reach across price tiers. Online platforms improve visibility and customer data use. Marketing focuses on lifestyle positioning and emotional appeal. This structure keeps competition dynamic and brand-driven.Recent Developments:
- In December 2025, Brunello Cucinelli announced exceptional growth with expected revenue increases of 11-12% at constant exchange rates, surpassing earlier expectations. The company completed its 2024-2026 plan for strengthening Made in Italy manufacturing one year ahead of schedule, including the doubling of its Solomeo plant and opening of new outerwear factories in Penne and Gubbio. Notably, the brand took over 26 main window displays at Harrods in London, signaling strong retail expansion. Additionally, Brunello Cucinelli launched an AI-powered e-commerce website in mid-January 2026, utilizing Solomei AI's Callimacus platform to deliver personalized shopping experiences. The company maintains a growth target of approximately 10% for 2026.
- On December 2, 2025, Prada completed its landmark acquisition of Versace from Capri Holdings for approximately €1.3 billion (around $1.51 billion). This deal, originally announced in April 2025, represents Prada's largest acquisition in over a century. Following regulatory clearance in December 2025, Prada now controls 100% of the iconic Italian brand. Lorenzo Bertelli, the heir to Prada's proprietors and head of corporate social responsibility, has assumed the role of executive chairman at Versace to drive integration. The acquisition strategically connects two of Italy's most culturally significant brands and positions Prada to accelerate Versace's long-term sustainable revenue growth.
- In October 2025, Gucci secured a transformative 50-year exclusive licensing agreement for fragrance and beauty products with L'Oréal. This partnership, announced on October 19, 2025, marks a strategic shift in how Gucci manages its beauty division. Following the expiration of its current license with Coty, Gucci will have L'Oréal develop, create, and distribute all of its fragrance and beauty offerings globally. The agreement is part of a €4 billion binding transaction valued between Kering (Gucci's parent company) and L'Oréal, which represents a significant evolution in Gucci's strategy to strengthen its position in the luxury beauty segment.
- In September 2025, following Giorgio Armani's passing, his will revealed plans for a gradual sale of his fashion empire, naming L'Oréal, LVMH, and EssilorLuxottica as preferred potential buyers. In early December 2025, L'Oréal's CFO Christophe Babule confirmed that the company is actively pursuing acquisition opportunities, stating the deal will be examined "very soon." The Armani group, valued at over £10 billion, includes prestigious brands such as Emporio Armani, A|X Armani Exchange, and Armani Privé. This represents one of the most significant potential acquisitions in luxury fashion, with L'Oréal demonstrating strong interest in expanding its luxury portfolio.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Season, By Application, By Age Group, and By Distribution Channel segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook:
- Brands will focus on timeless design with modern updates to retain loyalty.
- Premium and affordable luxury segments will gain stronger consumer interest.
- Casual and comfort-led apparel will integrate into everyday wardrobes.
- Digital channels will shape discovery, engagement, and conversion paths.
- Sustainability narratives will influence material and sourcing strategies.
- Exclusive stores will remain vital for brand storytelling and experience.
- Capsule collections will support faster response to fashion cycles.
- Younger consumers will drive trend velocity across categories.
- Regional cities will see higher apparel accessibility through e-commerce.
- Heritage positioning will strengthen global and domestic brand appeal.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strong Consumer Preference for Quality, Fit, and Italian Craftsmanship
Italian consumers highly value quality fabrics, precise tailoring, and the heritage of domestic brands, driving repeat purchases and brand loyalty across age groups. This focus on craftsmanship and fit sustains premium and mid-range segment growth.
Urban Lifestyle Expansion and Professional Workforce Participation
Increasing urbanization and a growing professional female workforce in Italy fuel demand for versatile, polished, and work-appropriate apparel. City retail hubs and capsule wardrobes cater to time-conscious, style-driven shoppers.
Retail Network Strength and Multi-Channel Accessibility
A robust mix of exclusive stores, multi-brand outlets, and expanding e-commerce platforms ensures broad product accessibility and convenience, supporting both impulse and planned purchases across regions.
Cultural Fashion Awareness and Style Consciousness
Deep-rooted Italian fashion culture and high style consciousness, amplified by media and fashion events, drive frequent wardrobe updates and trend adoption, supporting steady market growth.
Rising Preference for Sustainable and Responsible Apparel Choices
Growing consumer awareness of sustainability and ethical sourcing is pushing brands to adopt natural fabrics, transparent supply chains, and eco-friendly collections, which strengthens brand credibility and attracts conscious buyers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Italy Women Apparel Market in 2023 and 2032?
At what Compound Annual Growth Rate is the Italy Women Apparel Market projected to grow between 2024 and 2032?
What are the key drivers of the Italy Women Apparel Market?
How does e-commerce impact the Italy Women Apparel Market?
Who are the major players in the Italy Women Apparel Market?
Which region commanded the largest share of the Italy Women Apparel Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age Group
- 1.2.1 18–24 Years (Young Adults)
- 1.2.2 25–40 Years (Professionals)
- 1.2.3 40–60 Years (Mature)
- 1.2.4 60+ Years (Niche Premium)
- 1.3 By Application
- 1.3.1 Mass
- 1.3.2 Premium
- 1.3.3 Premium Contemporary
- 1.3.4 Affordable Luxury
- 1.3.5 Premium Athleisure
- 1.3.6 Premium Occasion Wear
- 1.3.7 Luxury
- 1.3.8 Ultra-Luxury / Couture
- 1.4 By Product Type
- 1.4.1 Casual Wear
- 1.4.2 Formal Wear
- 1.4.3 Innerwear and Sleepwear
- 1.4.4 Coats, Jackets, and Suits
- 1.4.5 Sports Wear
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 26,617.31 million → 2032: USD 31,469.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Italy Women Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Italy Women Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Italy Women Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Italy Women Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Italy Women Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Italy Women Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Italy Women Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Italy Women Apparel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 26,617.31 million → 2032: USD 31,469.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Italy Women Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age Group - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 18–24 Years (Young Adults)
- 12.3.7.2 25–40 Years (Professionals)
- 12.3.7.3 40–60 Years (Mature)
- 12.3.7.4 60+ Years (Niche Premium)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mass
- 12.4.7.2 Premium
- 12.4.7.3 Premium Contemporary
- 12.4.7.4 Affordable Luxury
- 12.4.7.5 Premium Athleisure
- 12.4.7.6 Premium Occasion Wear
- 12.4.7.7 Luxury
- 12.4.7.8 Ultra-Luxury / Couture
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Casual Wear
- 12.5.7.2 Formal Wear
- 12.5.7.3 Innerwear and Sleepwear
- 12.5.7.4 Coats, Jackets, and Suits
- 12.5.7.5 Sports Wear
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Italy Women Apparel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Italy Women Apparel Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Italy Women Apparel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Italy Women Apparel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gucci
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Prada
- 18.4 Armani
- 18.5 Dolce & Gabbana
- 18.6 Max Mara
- 18.7 Moncler
- 18.8 Brunello Cucinelli
- 18.9 Calzedonia Group
- 18.10 Salvatore Ferragamo
- 18.11 Versace
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

