
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
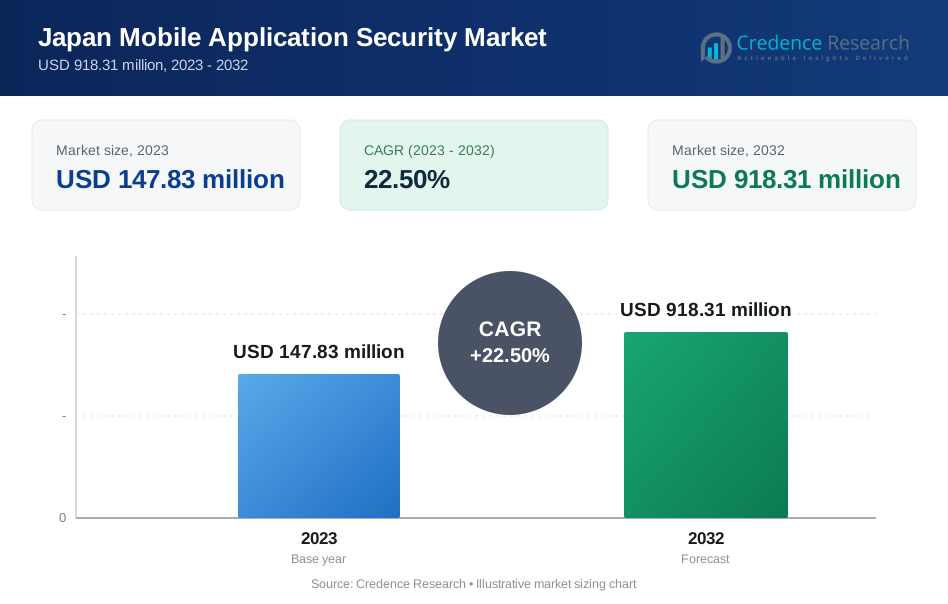
| Japan Mobile Application Security Market Size 2023 | USD 147.83 million |
| Japan mobile application security Market, CAGR | 22.50% |
| Japan mobile application security Market Size 2032 | USD 918.31 million |
Market Overview
The Japan mobile application security market is projected to grow from USD 147.83 million in 2023 to an estimated USD 918.31 million by 2032, with a compound annual growth rate (CAGR) of 22.50% from 2024 to 2032. This substantial growth underscores the escalating demand for robust mobile security solutions amidst rising mobile penetration and increasing mobile commerce activities.
Several key drivers are propelling the growth of the mobile application security market in Japan. These include the heightened awareness of cybersecurity threats among companies, the stringent regulatory requirements for data protection, and the rising incidence of mobile-based cyberattacks. Additionally, the increasing adoption of IoT devices and the surge in remote work trends necessitate robust security solutions, further bolstering the market’s expansion.
Geographically, the Tokyo metropolitan area holds a significant share of the market, attributed to its high concentration of tech companies and startups, which are key consumers of mobile application security solutions. Key players in the Japan market include IBM Japan, Ltd., Symantec Japan, Inc., and Trend Micro Incorporated, each contributing to the market’s development through innovative security products tailored to address the unique cybersecurity challenges faced by Japanese enterprises. These companies are pivotal in shaping the competitive landscape and driving technological advancements in the region.
Market Drivers
Increasing Prevalence of Chronic Respiratory Diseases
Japan is facing a rising incidence of chronic respiratory conditions like COPD and asthma, particularly among its aging population. For instance, government health surveys have shown a steady increase in COPD diagnoses over the past decade, with a notable surge in cases among individuals over 65 years old. This trend has led to greater demand for medical suction devices in both hospital and home care settings. Healthcare facilities are expanding their inventory of suction equipment to manage these conditions effectively. Additionally, there has been a marked increase in prescriptions for portable suction devices for home use, allowing patients to manage their symptoms independently. The Japanese government has responded by allocating more resources to respiratory care programs and subsidizing the cost of medical suction devices for eligible patients.
Technological Advancements in Device Design
Innovations in medical suction device technology have been a major driver of market growth in Japan. Leading medical device manufacturers have introduced new product lines featuring improved portability, battery life, and suction power. For example, a prominent Japanese medical equipment company recently launched a compact suction device weighing less than 2 kg, specifically designed for emergency responders and home care use. These advancements have expanded the application of suction devices beyond traditional hospital settings. Market research indicates a growing preference among Japanese healthcare providers for multifunctional devices that can be easily transported between different care environments. The integration of smart features, such as remote monitoring capabilities and automated cleaning systems, has further enhanced the appeal of newer models, driving replacement of older equipment in many healthcare facilities across the country.
Technological Advancements and Integration of IoT Devices:
The integration of Internet of Things (IoT) devices in everyday life and business operations has expanded the scope of mobile applications. IoT devices often rely on mobile applications for control and data exchange, creating new vulnerabilities and security challenges. The proliferation of these devices in homes, vehicles, and workplaces increases the points of entry for cyber-attacks, necessitating more robust and versatile mobile application security solutions. Furthermore, advancements in technology, such as the development of artificial intelligence and machine learning, are being leveraged to enhance the effectiveness of security applications. These technologies enable more sophisticated threat detection and response mechanisms, significantly improving the security posture of mobile applications.
Market Trends
Growing Demand for Portable and Compact Devices
The Japan medical suction device market is seeing increased demand for portable and compact suction devices, especially for home care and emergency use. This trend is driven by Japan's rapidly aging population and the shift towards home-based care. According to data from the Ministry of Health, Labour and Welfare, the number of elderly people receiving home medical care in Japan has been steadily rising. For instance, a survey conducted by the ministry found that the number of home care patients using medical devices, including suction equipment, increased by over 20% in the past five years. Manufacturers are responding by developing lightweight, battery-powered suction devices that are easy to use and transport. Major medical device companies have reported growing sales of portable suction units in Japan, with some firms noting double-digit growth in this segment. The Japan Medical Devices Manufacturers Association has also highlighted the importance of portable medical equipment in supporting the country's home care initiatives.
Technological Advancements in Medical Suction Devices
Technological innovations are driving advancements in medical suction devices in the Japanese market. There is a growing focus on developing smart, connected devices with improved efficiency and safety features. For instance, a leading Japanese medical equipment manufacturer recently introduced a new line of suction devices with integrated IoT capabilities, allowing for remote monitoring and data collection. This innovation has been well-received by healthcare facilities, with several major hospitals in Tokyo and Osaka reporting improved patient outcomes after adopting these advanced systems. Additionally, government data shows an increase in R&D investments in medical device technology, with suction devices being a key area of focus. The Japan Agency for Medical Research and Development has funded multiple projects aimed at enhancing suction device technology, particularly for critical care applications. Industry surveys indicate that healthcare professionals in Japan are increasingly preferring suction devices with advanced features such as adjustable suction power, noise reduction technology, and antimicrobial properties.
Market Restraints and Challenges
High Regulatory Barriers and Approval Processes
One of the major challenges facing the Japan Medical Suction Device Market is the stringent regulatory environment and lengthy approval processes. Japan's Pharmaceutical and Medical Device Agency (PMDA) is known for having some of the most rigorous medical device regulations globally. For instance, a survey by the Japan Medical Devices Manufacturers Association found that it takes an average of 3-5 years for new medical devices to gain regulatory approval in Japan, compared to 6-18 months in other major markets. This extended timeline can significantly delay product launches and market entry for both domestic and international manufacturers. Additionally, all documentation must be submitted in Japanese, creating language barriers for foreign companies. The Japan External Trade Organization (JETRO) reported that over 60% of foreign medical device manufacturers cited regulatory hurdles as their top challenge in entering the Japanese market. These strict requirements, while ensuring product safety and efficacy, can deter innovation and limit the availability of new suction device technologies for Japanese healthcare providers and patients.
Market Saturation and Price Pressures
Another key challenge is market saturation and increasing price pressures in Japan's medical suction device sector. With an aging population driving demand, the market has become highly competitive. A study by the Ministry of Health, Labour and Welfare found that over 80% of hospitals in Japan already have multiple suction devices installed. This high penetration rate makes it difficult for new entrants to gain market share. Furthermore, government initiatives to reduce healthcare costs have put downward pressure on medical device prices. For example, the biennial price revision system implemented by the Japanese government has led to an average 7-9% reduction in reimbursement prices for medical devices every two years. The Japan Federation of Medical Devices Associations reported that profit margins for medical device manufacturers have been steadily declining, with some companies seeing margins drop by 15-20% over the past decade. These pricing pressures force companies to continually innovate and improve efficiency to remain competitive, which can be challenging, especially for smaller manufacturers with limited resources.
Market Segmentation Analysis
By offering
The Japan mobile application security market is segmented into solutions and services, with solutions dominating the market. Organizations are increasingly investing in robust security tools to protect against rising cyber threats. For instance, a survey by the Japan Network Security Association found that over 70% of Japanese companies have implemented mobile application security solutions. The solutions segment includes application shielding, encryption, mobile threat defense, and app reputation services. The services segment, comprising professional and managed services, also plays a critical role. Professional services like consulting and integration are essential for effective implementation. For example, a study by the Japan Information Security Audit Association revealed that 65% of companies utilize professional services for mobile security. Managed services are gaining popularity as businesses outsource security management. A report by the Japan Information-Technology Promotion Agency indicated that managed security services adoption has grown significantly in recent years, with many organizations citing cost-effectiveness and access to specialized expertise as key drivers.
By OS
In the Japan mobile application security market, iOS holds a significant segment due to the widespread use of Apple devices. A consumer survey by the Ministry of Internal Affairs and Communications found that iOS devices account for a substantial portion of smartphone usage in Japan. The closed ecosystem of iOS offers inherent security advantages, but businesses still invest in additional security measures. For example, a study by the Japan Smartphone Security Forum showed that many enterprises implement extra layers of protection for iOS devices to ensure data security and regulatory compliance. Android also commands a substantial market share, driven by its large user base. However, its open-source nature increases security risks. A report by the National center of Incident readiness and Strategy for Cybersecurity (NISC) highlighted the growing number of Android-specific malware threats in Japan, driving demand for tailored security solutions. Other operating systems, while smaller in market share, still require robust security measures, particularly in niche industries. For instance, a survey by the Japan IoT Promotion Consortium found that specialized industries often use custom operating systems that require unique security approaches.
Segments
Based on Offering
- Solutions
- Services
- Professional Services
- Managed Services
Based on OS
- iOS
- Android
- Other OS
Based on Deployment
- Cloud
- On-Premises
Based on Organization Size
- Large Enterprises
- SMEs
Based on Vertical
- IT & Telecom
- BFSI (Banking, Financial Services, and Insurance)
- Healthcare & Life Sciences
- Government & Defense
- Others
Based on Region
- Urban
- Rural
Key players
- IBM Corporation
- HCL Technologies Ltd. (HCL Enterprises)
- Open Text Corporation
- Qualys, Inc.
- Oracle Corporation
- Cisco Systems Inc.
- VMware, Inc. (Broadcom Inc.)
- GitLab Inc.
- Google LLC (Alphabet Inc.)
- Data Theorem, Inc.
Competitive Analysis
The Japan mobile application security market is highly competitive, with key players such as IBM Corporation, HCL Technologies Ltd., and Oracle Corporation leading the charge through comprehensive security solutions that cater to a broad range of industries. These companies leverage their extensive experience and global presence to offer advanced security measures tailored to the unique needs of the Japanese market. Cisco Systems Inc. and VMware Inc. (Broadcom Inc.) are also prominent, offering integrated security solutions that align with the growing demand for cloud and on-premises deployment models. Companies like GitLab Inc. and Data Theorem, Inc. focus on niche aspects of mobile security, such as continuous integration and application vulnerability management, positioning themselves as crucial players for businesses seeking specialized security services. This diverse competitive landscape ensures a robust offering of solutions, driving innovation and ensuring comprehensive protection against evolving cyber threats.
Recent Developments
- In June 2024, IBM announced the launch of a Cybersecurity Center of Excellence in Tokyo, focusing on enhancing Japan's cybersecurity defenses and digital resilience. This center aims to strengthen mobile application security capabilities for Japanese enterprises.
- In May 2024, Qualys launched CyberSecurity Asset Management 3.0 in Japan, expanding its Enterprise TruRisk Platform. This update integrates vulnerability assessment capabilities into its External Attack Surface Management (EASM) solution, which can help improve mobile application security for Japanese organizations.
- In February 2024, Cisco unveiled new developments across its Software-Defined Edge portfolio at Mobile World Congress, including enhancements to its SASE and Edge Compute offerings. These innovations can potentially benefit mobile application security for Japanese customers.
- In February 2024, VMware (now part of Broadcom) announced significant developments in its Software-Defined Edge portfolio at Mobile World Congress, including a new single-vendor SASE solution with Symantec. This could improve mobile application security for Japanese enterprises.
- In March 2024, GitLab acquired Oxeye, a cloud-native application security testing solution provider. This acquisition aims to enhance GitLab's Static Application Security Testing (SAST) capabilities, which could benefit mobile application security efforts in Japan.
- In January 2024, Data Theorem's Cloud Secure solution was named the Best CNAPP (Cloud-Native Application Protection Platform) Solution of 2023. This recognition highlights the company's capabilities in securing cloud-native applications, which is relevant to mobile application security in Japan.
Market Concentration and Characteristics
The Japan mobile application security market is characterized by a moderate to high level of market concentration, with a few key players such as IBM Corporation, Oracle Corporation, and Cisco Systems Inc. holding significant market shares. These established companies dominate the market due to their extensive product portfolios, strong brand presence, and ability to provide comprehensive, integrated security solutions tailored to various industry needs. However, the market also features several niche players and innovative startups, particularly in areas like AI-driven threat detection and vulnerability management, which contribute to a dynamic and competitive environment. The market's focus on advanced technologies and compliance with stringent regulatory standards further shapes its distinctive characteristics, emphasizing the need for robust and adaptable security solutions.
Report Coverage
The research report offers an in-depth analysis based on Offering, OS, Deployment, Organization Size, Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan mobile application security market is expected to experience accelerated growth, driven by increasing mobile penetration and the rising incidence of cyber threats.
- The integration of artificial intelligence (AI) and machine learning in security solutions will enhance threat detection and response capabilities, making security measures more proactive and adaptive.
- The shift towards cloud-based deployments will continue to rise, with organizations favoring the scalability and flexibility of cloud solutions to secure mobile applications.
- Stricter data protection regulations will drive businesses to invest heavily in mobile security solutions to ensure compliance and protect sensitive information.
- Small and medium-sized enterprises (SMEs) will increasingly adopt mobile application security solutions, recognizing the need to protect their digital assets amidst growing cybersecurity risks.
- As the Internet of Things (IoT) expands, mobile application security will become more complex, necessitating solutions that address the unique vulnerabilities of interconnected devices.
- Managed security services will see higher demand as organizations look to outsource their mobile security needs to experts, ensuring continuous protection without straining internal resources.
- The market will witness the entry of innovative startups and niche players, particularly those offering specialized solutions like real-time threat intelligence and mobile application testing.
- There will be a growing focus on balancing robust security measures with seamless user experiences, ensuring that security does not hinder app performance or usability.
- While Tokyo will remain the dominant region, other areas like Kansai and Chubu will see increased adoption of mobile application security solutions, driven by digital transformation efforts across Japan.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan mobile application security market?
What are the main drivers of the Japan mobile application security market?
Which region dominates the Japan mobile application security market?
Who are the key players in the Japan mobile application security market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Mobile Application Security Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Mobile Application Security Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 147.83 million → 2032: USD 918.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Mobile Application Security Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Mobile Application Security Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Mobile Application Security Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Mobile Application Security Market Drivers
- 3.3 Japan Mobile Application Security Market Restraints & Challenges
- 3.4 Japan Mobile Application Security Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Mobile Application Security Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Mobile Application Security Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Mobile Application Security category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Mobile Application Security Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Mobile Application Security Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Mobile Application Security market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Mobile Application Security Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Mobile Application Security Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Mobile Application Security Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Mobile Application Security (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Mobile Application Security Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Mobile Application Security Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Mobile Application Security Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Mobile Application Security Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Mobile Application Security Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Mobile Application Security Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Mobile Application Security Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Mobile Application Security Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Mobile Application Security Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
