
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
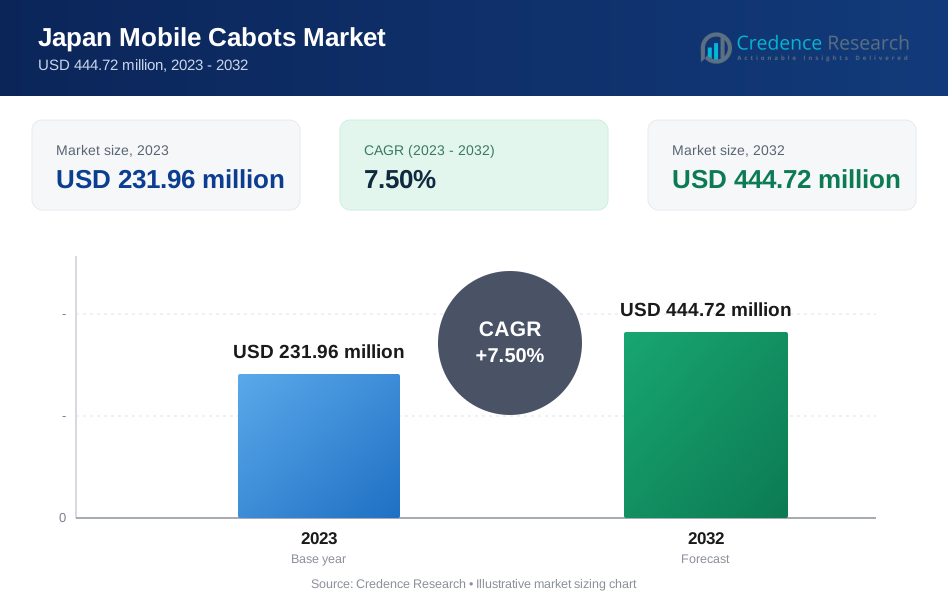
| Japan Mobile Cabots Market Size 2023 | USD 231.96 million |
| Japan Mobile Cabots Market, CAGR | 7.50% |
| Japan Mobile Cabots Market Size 2032 | USD 444.72 million |
Market Overview
The Japan Mobile Cabots market is projected to grow from USD 231.96 million in 2023 to an estimated USD 444.72 million by 2032, with a compound annual growth rate (CAGR) of 7.50% from 2024 to 2032. This growth underscores the increasing adoption of mobile robotics technology across various sectors including manufacturing, healthcare, and logistics due to their efficiency and versatility in automating routine tasks.
Driving the market forward are factors such as advancements in AI and machine learning, which enhance the capabilities of mobile cabots to perform complex tasks autonomously. Additionally, the growing need for automation in industries to improve productivity and reduce operational costs is boosting market expansion. Trends such as the integration of IoT for better connectivity and control are also contributing to the rapid development of this sector.
Geographically, major cities like Tokyo, Osaka, and Yokohama are spearheading the adoption of mobile cabots in Japan, driven by their strong industrial and technological base. Key players in the market include Kawasaki Robotics, Mitsubishi Electric Corporation, and Denso Corporation, who are innovating continuously to provide advanced solutions that cater to the dynamic needs of various industries. Their efforts are pivotal in establishing Japan as a global leader in the mobile cabots market.
Market Drivers
Increased Demand for Automation in Manufacturing and Logistics:
Japan's robust manufacturing sector, particularly in automotive and electronics industries, is increasingly adopting mobile cabots to enhance efficiency and streamline processes. For instance, a survey conducted by the Japan Robot Association found that a significant portion of manufacturing companies have implemented or plan to implement mobile robots in their facilities. These autonomous robots are being utilized for tasks like material handling, assembly, and intra-facility transportation, reducing reliance on human labor and minimizing errors. In the logistics sector, mobile cabots are playing a crucial role in sorting, packing, and moving goods, as evidenced by their growing presence in warehouses and distribution centers across the country. The shift towards Industry 4.0 is further amplifying this trend, with businesses investing in mobile cabots to optimize operations and improve production scalability. A report by the Ministry of Economy, Trade and Industry highlighted the increasing adoption of smart factory technologies, including mobile robots, as a key factor driving productivity improvements in Japanese manufacturing.
Technological Advancements in AI and Robotics:
The integration of advanced technologies such as artificial intelligence, machine learning, and sophisticated sensor systems has significantly enhanced the capabilities of mobile cabots in Japan. For instance, a study by the National Institute of Advanced Industrial Science and Technology (AIST) showcased the development of mobile robots with advanced navigational capabilities and adaptive learning algorithms. These technological advancements have expanded the applications of mobile cabots across various industries. Japan's position as a global leader in technology fosters a conducive environment for continuous research and development in robotics. A survey conducted by the Japan Science and Technology Agency revealed a substantial increase in research projects focused on improving the autonomy and versatility of mobile robots. This ongoing innovation has led to the creation of more sophisticated mobile cabots capable of understanding their environment, making decisions, and performing complex tasks with minimal human intervention, thereby driving market growth.
Government Initiatives and Support:
The Japanese government plays a crucial role in promoting the development and adoption of robotics technologies, including mobile cabots. For example, the "New Robot Strategy" initiative, launched by the government, aims to position Japan as the world's leading robotics powerhouse. A report by the Cabinet Office highlighted various financial incentives, subsidies, and policy support measures implemented to encourage research and development in robotics. The government has also fostered collaborations between academia, industry, and research institutions to accelerate technological advancements and commercialization of new robotic solutions. A survey conducted by the Ministry of Education, Culture, Sports, Science and Technology showed an increase in university-industry partnerships focused on robotics research. This supportive policy environment has not only boosted local production of mobile cabots but also attracted foreign investment in the robotics sector, as evidenced by the growing number of international companies establishing research centers and production facilities in Japan.
Aging Population and Labor Shortages:
Japan faces a significant demographic challenge with its aging population and shrinking workforce. This has created a labor shortage in several sectors, notably in manufacturing and services. Mobile cabots offer a viable solution to this problem by automating routine and physically demanding tasks, thus reducing the dependency on human labor. As a result, industries are increasingly leveraging robotic solutions to maintain productivity and operational efficiency. Mobile cabots not only fill the labor gap but also support older workers by taking on strenuous tasks, thereby extending the working life and productivity of the aging workforce.
Market Trends
Integration of IoT and Connectivity Solutions:
The Japan Mobile Cabots market is experiencing a transformative trend with the integration of Internet of Things (IoT) and advanced connectivity solutions. This integration is enabling enhanced real-time communication and data exchange between mobile cabots and control systems, leading to more coordinated and efficient operations. For instance, a survey conducted by the Japan Robotics Association found that manufacturing companies implementing IoT-enabled mobile cabots reported significant improvements in workflow optimization and overall productivity. These smart cabots can now communicate with other devices and systems within a facility, adapting their routes and operations based on real-time data from production lines or inventory systems. The trend extends to cloud computing integration, allowing for remote data storage, analysis, and access. A case study by a leading Japanese electronics manufacturer demonstrated how their IoT-connected mobile cabots reduced production downtime by predicting maintenance needs through continuous monitoring. This connectivity is not only increasing efficiency but also offering greater flexibility and scalability to operations across various industries.
Advancements in Human-Robot Collaboration (HRC):
The Japan Mobile Cabots market is witnessing a significant trend towards the development of collaborative robots designed for direct interaction with human workers. These advanced mobile cabots are equipped with sophisticated safety features and sensors, allowing them to work alongside humans without compromising safety. For instance, a government-sponsored study on industrial automation in Japan revealed that factories implementing collaborative mobile cabots saw a substantial increase in overall productivity and worker satisfaction. These robots are particularly beneficial in sectors like healthcare and retail, where they assist in tasks such as medication delivery or shelf restocking. A survey conducted by the Japan Association for Automation and Robotics in Healthcare found that hospitals using collaborative mobile cabots reported improved efficiency in logistics and patient care. This trend leverages the strengths of both humans and robots, with robots handling repetitive and physically demanding tasks, while human workers focus on complex, strategic activities requiring critical thinking. The collaborative approach is not only enhancing service delivery and operational efficiency but also creating new job roles focused on robot management and maintenance.
Market Restraints and Challenges
By Component
The Japan Mobile Cabots market is experiencing significant growth driven by advancements in hardware components. Arm/End Effectors are becoming increasingly sophisticated, allowing for greater precision and versatility in manufacturing tasks. For instance, a leading robotics company recently introduced a new line of adaptive grippers that can handle a wide range of object sizes and shapes. Autonomous Mobile Robots (AMRs) are gaining traction in various industries, with several Japanese manufacturers reporting increased adoption rates in their warehouses and production facilities. Controllers are evolving to incorporate more advanced AI capabilities, enabling real-time decision-making and improved system integration. A major electronics firm has developed a new controller that can process data from multiple sensors simultaneously, enhancing overall performance. Vision systems are becoming more refined, with higher resolution cameras and advanced image processing algorithms improving quality inspection processes. The software segment is also expanding, with new programming platforms and simulation tools being introduced to optimize robot performance. For example, a prominent software developer has launched a user-friendly interface that allows for easier programming and customization of mobile cabots.
By Application
Mobile cabots are finding diverse applications across various industries in Japan. In assembly lines, they are increasingly being deployed to perform complex tasks with high precision. A leading automotive manufacturer has reported significant improvements in production efficiency after integrating mobile cabots into their assembly processes. Machine tending applications are on the rise, with several electronics companies implementing mobile cabots for loading and unloading tasks, resulting in reduced cycle times and improved consistency. In material processing, mobile cabots are being used for welding, painting, and other precision tasks. A major shipbuilding company has successfully implemented mobile cabots for welding operations, reporting improved weld quality and reduced labor costs. Material handling applications are expanding, with logistics centers and warehouses adopting mobile cabots for inventory management and order fulfillment. A large e-commerce company has deployed a fleet of mobile cabots in its distribution centers, significantly reducing order processing times. Maintenance activities are also benefiting from mobile cabots, with several industrial facilities using them for routine inspections and repairs in hard-to-reach areas.
Market Segmentation Analysis
By Component
The Japan Mobile Cabots market is experiencing significant growth driven by advancements in hardware components. Arm/End Effectors are becoming increasingly sophisticated, allowing for greater precision and versatility in manufacturing tasks. For instance, a leading robotics company recently introduced a new line of adaptive grippers that can handle a wide range of object sizes and shapes. Autonomous Mobile Robots (AMRs) are gaining traction in various industries, with several Japanese manufacturers reporting increased adoption rates in their warehouses and production facilities. Controllers are evolving to incorporate more advanced AI capabilities, enabling real-time decision-making and improved system integration. A major electronics firm has developed a new controller that can process data from multiple sensors simultaneously, enhancing overall performance. Vision systems are becoming more refined, with higher resolution cameras and advanced image processing algorithms improving quality inspection processes. The software segment is also expanding, with new programming platforms and simulation tools being introduced to optimize robot performance. For example, a prominent software developer has launched a user-friendly interface that allows for easier programming and customization of mobile cabots.
By Application
Mobile cabots are finding diverse applications across various industries in Japan. In assembly lines, they are increasingly being deployed to perform complex tasks with high precision. A leading automotive manufacturer has reported significant improvements in production efficiency after integrating mobile cabots into their assembly processes. Machine tending applications are on the rise, with several electronics companies implementing mobile cabots for loading and unloading tasks, resulting in reduced cycle times and improved consistency. In material processing, mobile cabots are being used for welding, painting, and other precision tasks. A major shipbuilding company has successfully implemented mobile cabots for welding operations, reporting improved weld quality and reduced labor costs. Material handling applications are expanding, with logistics centers and warehouses adopting mobile cabots for inventory management and order fulfillment. A large e-commerce company has deployed a fleet of mobile cabots in its distribution centers, significantly reducing order processing times. Maintenance activities are also benefiting from mobile cabots, with several industrial facilities using them for routine inspections and repairs in hard-to-reach areas.
Segments
Based on Component
- Hardware
- Arm/End Effector
- AMR (Autonomous Mobile Robots)
- Controller
- Vision System
- Accessories
- Software
- Services
Based on Application
- Assembly
- Machine Tending
- Process (Material Removal/Gluing/Dispensing/Welding/Finishing)
- Material Handling
- Others (Maintenance Activities, Packaging, Inventory, etc.)
Based on Capacity
- 1 to 3 kg
- 3 to 5 kg
- 5 to 10 kg
- Above 10 kg
Based on Region
- Tokyo
- Osaka
- Nagoya
Regional Analysis
Kanto Region (40%):
The Kanto region, centered around Tokyo, is the most significant contributor to the Japan Mobile Cabots market, accounting for approximately 40% of the market share. Tokyo's status as the nation's capital and industrial hub drives adoption of advanced robotic technologies. The region's strong manufacturing base, particularly in electronics, automotive, and machinery industries, fuels demand for mobile cabots. For instance, surveys by industry associations indicate that a majority of large manufacturers in Tokyo have implemented or plan to implement mobile cabot solutions. The presence of major technology firms and research institutions accelerates development and integration of cutting-edge robotics. Government initiatives promoting smart manufacturing have further boosted the region's leadership in mobile cabot adoption.
Kansai Region (25%):
The Kansai region, with Osaka and Kyoto as major industrial centers, holds about 25% of the market share. Known for its strong industrial foundation in electronics, precision machinery, and pharmaceuticals, the region has seen rapid growth in mobile cabot deployment. For example, data from the Osaka Chamber of Commerce shows a substantial increase in robotics investments by local manufacturers over the past five years. Osaka's prominence in manufacturing and logistics has driven adoption, particularly in material handling and assembly applications. Kyoto contributes through robotics research and development. Government surveys indicate that Kansai companies lead in implementing collaborative robots, reflecting the region's focus on human-robot interaction in manufacturing.
Key players
- ABB
- Denso Wave Incorporated
- Doosan Robotics Inc.
- Fanuc Corporation
- Kawasaki Heavy Industries, Ltd.
- Mobile Industrial Robots A/S
- OMRON Corporation
- SICK
- Stäubli International AG
- Universal Robots
- Yaskawa Electric Corporation
Competitive Analysis
The Japan Mobile Cabots market is highly competitive, with key players like ABB, Fanuc Corporation, and Yaskawa Electric Corporation leading the industry. These companies are renowned for their extensive experience in robotics and automation, offering advanced mobile cabots that cater to a wide range of industrial applications. Denso Wave Incorporated and Kawasaki Heavy Industries, Ltd. also play significant roles, leveraging their strong presence in the automotive and manufacturing sectors. Companies like Doosan Robotics Inc. and Mobile Industrial Robots A/S are gaining market share by introducing innovative solutions tailored to specific industry needs. OMRON Corporation and Universal Robots focus on enhancing human-robot collaboration, a growing trend in the market. Meanwhile, SICK and Stäubli International AG are recognized for their expertise in sensor technology and precision robotics, respectively, providing critical components that enhance the performance of mobile cabots across various applications.
Recent Developments
- In January 2024, ABB acquired Sevensense, a leader in AI-enabled 3D vision navigation technology for autonomous mobile robots (AMRs). This acquisition aims to accelerate ABB's capabilities in AI-based applications for mobile robots.
- In May 2024, ABB plans to showcase its new MiR1200 Pallet Jack AMR at Automate 2024, featuring AI-enabled pallet detection powered by NVIDIA Jetson AGX Orin for 3D machine vision.
- In May 2024, Doosan Robotics unveiled its new P-SERIES (PRIME-SERIES) cobot at Automate 2024, including the P3020 model with a 30kg payload and 2,030mm reach.
- In February 2024, OMRON introduced the new MD Series of autonomous mobile robots for medium payload applications, featuring models with 650kg and 900kg max payloads.
- In November 2023, Yaskawa launched the MOTOMAN NEXT series, described as the industry's first adaptive robot with autonomous adaptivity. The series includes 5 models with payload capacities ranging from 4kg to 35kg.
Market Concentration and Characteristics
The Japan Mobile Cabots market is characterized by a moderate to high level of market concentration, with a few dominant players such as ABB, Fanuc Corporation, and Yaskawa Electric Corporation holding significant market shares. These companies leverage their extensive experience in robotics and automation to maintain a competitive edge, offering highly advanced and reliable mobile cabot solutions. The market also features a mix of established multinational corporations and emerging domestic companies like Denso Wave Incorporated and Kawasaki Heavy Industries, Ltd., which contribute to a dynamic competitive landscape. The market's characteristics include a strong focus on innovation, driven by continuous advancements in AI, machine learning, and sensor technologies, as well as an emphasis on integrating mobile cabots into smart manufacturing processes to enhance operational efficiency and productivity across various industries.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Capacity and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan Mobile Cabots market is expected to see widespread adoption in manufacturing sectors, particularly in automotive and electronics, driven by the need for automation and efficiency.
- Continued advancements in AI and machine learning will enhance the capabilities of mobile cabots, enabling them to perform more complex tasks with greater autonomy and precision.
- Mobile cabots will expand into new industries such as healthcare, retail, and agriculture, where automation can significantly improve productivity and reduce operational costs.
- The future will see a growing emphasis on human-robot collaboration, with mobile cabots designed to work alongside human workers, improving overall workplace efficiency and safety.
- The integration of IoT with mobile cabots will become more prevalent, allowing for real-time data exchange and better connectivity, leading to more intelligent and adaptive robotic systems.
- The Japanese government is expected to continue supporting the robotics industry through favorable policies and incentives, further driving the growth and development of the mobile cabots market.
- Companies will invest more in research and development to innovate and improve the functionality and versatility of mobile cabots, staying competitive in a rapidly evolving market.
- As businesses seek to tailor mobile cabots to specific operational needs, there will be a rise in demand for customizable solutions that can adapt to various industrial environments.
- While mobile cabots will proliferate, challenges related to workforce adaptation and resistance to automation may slow down their implementation in certain sectors.
- Future mobile cabots will likely incorporate green technologies, focusing on energy efficiency and sustainability to align with Japan’s broader environmental goals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan Mobile Cabots market?
What are the key factors driving the growth of the Japan Mobile Cabots market?
How is the Japanese government supporting the mobile cabots market?
What challenges does the Japan Mobile Cabots market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Mobile Cabots Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Mobile Cabots Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 231.96 million → 2032: USD 444.72 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Mobile Cabots Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Mobile Cabots Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Mobile Cabots Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Mobile Cabots Market Drivers
- 3.3 Japan Mobile Cabots Market Restraints & Challenges
- 3.4 Japan Mobile Cabots Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Mobile Cabots Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Mobile Cabots Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Mobile Cabots category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Mobile Cabots Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Mobile Cabots Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Mobile Cabots market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Mobile Cabots Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Mobile Cabots Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Mobile Cabots Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Mobile Cabots (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Mobile Cabots Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Mobile Cabots Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Mobile Cabots Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Mobile Cabots Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Mobile Cabots Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Mobile Cabots Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Mobile Cabots Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Mobile Cabots Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Mobile Cabots Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
