
Market Overview:
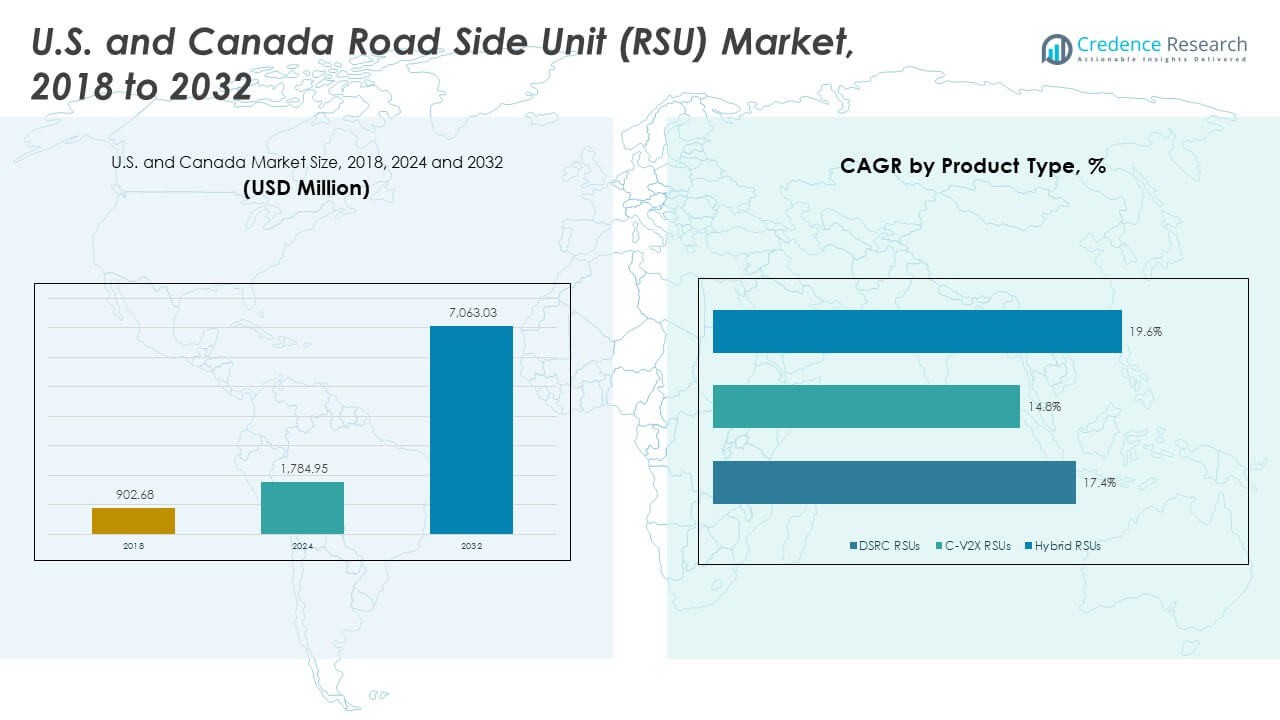
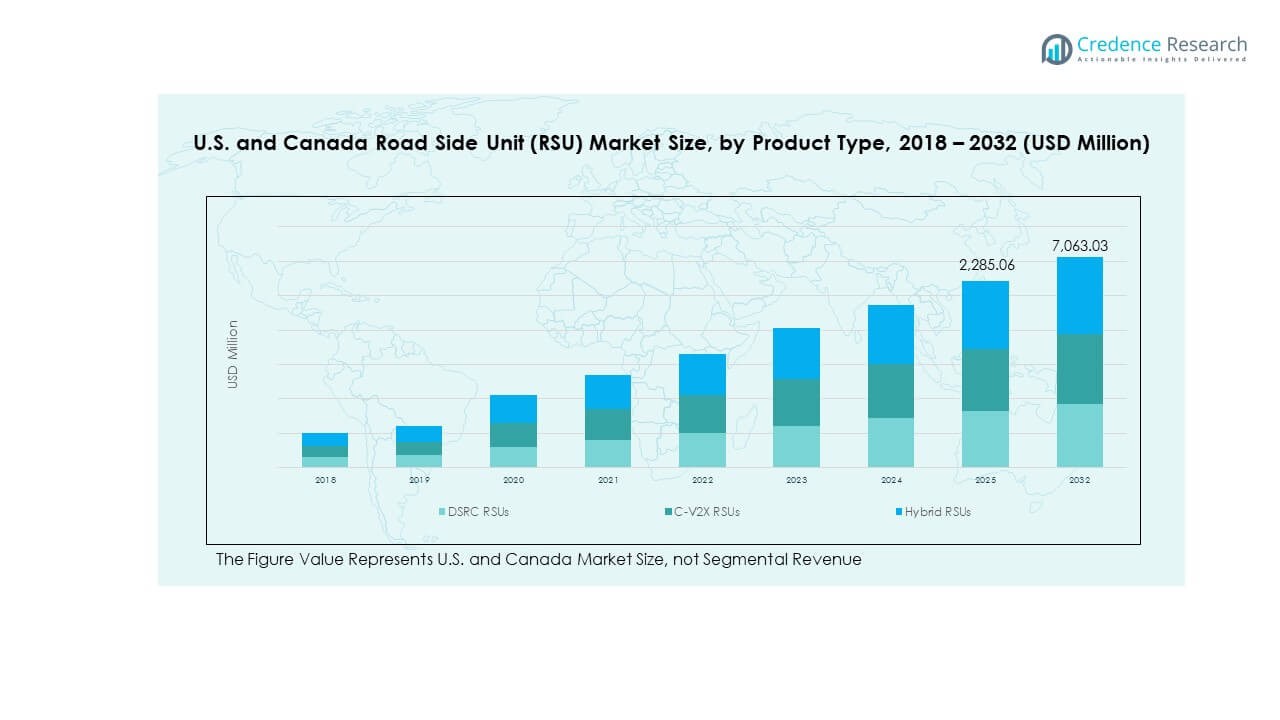
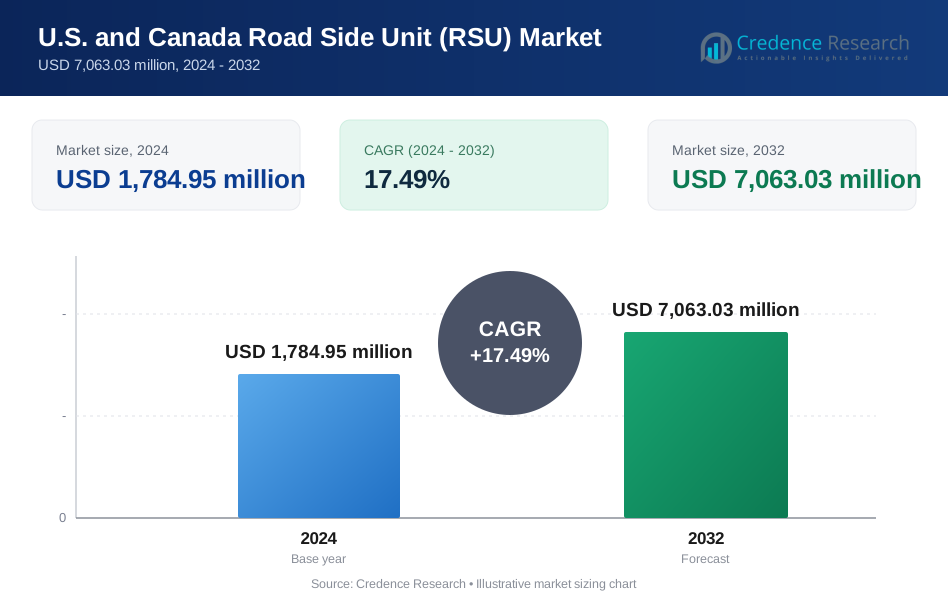
The U.S. and Canada Road Side Unit (RSU) Market size was valued at USD 902.68 million in 2018 to USD 1,784.95 million in 2024 and is anticipated to reach USD 7,063.03 million by 2032, at a CAGR of 17.49% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. and Canada Road Side Unit (RSU) Market Size 2024 | USD 1,784.95 Million |
| U.S. and Canada Road Side Unit (RSU) Market, CAGR | 17.49% |
| U.S. and Canada Road Side Unit (RSU) Market Size 2032 | USD 7,063.03 Million |
The market expands rapidly due to growing adoption of connected vehicle infrastructure and strong investment in smart transportation networks. Federal programs promoting vehicle-to-everything (V2X) communication strengthen RSU deployment across urban corridors and highways. Demand grows with rising use of 5G networks, autonomous vehicles, and real-time traffic management systems. Public–private partnerships drive interoperability testing and infrastructure modernization. Industry players develop multi-protocol RSUs to ensure low-latency, secure communication, supporting nationwide mobility integration.
The United States dominates this regional market due to extensive investment in intelligent transportation systems and early adoption of connected corridor projects. Canada follows with strong momentum driven by smart city initiatives and 5G testbeds across major provinces. Urban zones lead in RSU implementation for congestion control and safety optimization, while rural routes gain attention for logistics and cross-border connectivity. Collaborative efforts between telecom providers, automakers, and state agencies create scalable frameworks that strengthen market maturity across North America.
Market Insights
- The U.S. and Canada Road Side Unit (RSU) Market was valued at USD 902.68 million in 2018, reached USD 1,784.95 million in 2024, and is projected to hit USD 7,063.03 million by 2032, expanding at a CAGR of 17.49%.
- The United States leads with around 75% share, driven by large-scale V2X projects and federal smart transportation funding, followed by Canada with nearly 25% share, supported by growing 5G testbeds and smart city initiatives.
- Emerging rural and cross-border corridors show the fastest growth, accounting for nearly 15% of future expansion, powered by logistics connectivity and new RSU infrastructure integration.
- In product distribution, C-V2X RSUs represent about 45% of total market share in 2024, supported by rapid 5G adoption and OEM partnerships.
- Hybrid RSUs account for nearly 35%, gaining traction due to dual-mode interoperability that supports both DSRC and C-V2X communication systems.
Market Drivers
Expansion of Intelligent Transportation Infrastructure
The U.S. and Canada Road Side Unit (RSU) Market grows due to large-scale smart infrastructure programs. Governments invest heavily in vehicle-to-everything (V2X) communication networks to improve road safety and traffic efficiency. Transportation departments deploy RSUs at intersections, highways, and urban corridors for seamless connectivity. Federal funding programs and regional pilot projects speed up adoption across key states and provinces. Cities integrate RSUs with traffic lights and surveillance systems for synchronized control. It supports better data collection and incident management. OEMs and telecom operators collaborate to align RSUs with 5G infrastructure. The integration strengthens both communication reliability and transport efficiency.
Rising Focus on Connected and Autonomous Vehicles
Connected and autonomous vehicles depend on roadside communication nodes for safe operation. The demand for RSUs increases due to growing investments in self-driving technologies. Vehicle manufacturers adopt V2X-enabled modules that require real-time coordination with infrastructure units. The U.S. leads with pilot projects linking RSUs to autonomous fleets. Canada follows with testbeds supporting connected mobility corridors. It promotes safety through data exchange on traffic flow, hazards, and signal timing. Growing collaboration between automakers, network providers, and municipal planners boosts deployment. The ecosystem fosters nationwide RSU penetration to enable smart mobility goals.
- For example, the Ann Arbor Connected Vehicle Test Environment (AACVTE), managed by the University of Michigan Transportation Research Institute (UMTRI), features over 25 roadside units (RSUs) and 2,500 onboard units (OBUs). It serves as one of the largest real-world connected vehicle testbeds in North America, enabling advanced research on V2X communication and autonomous driving safety systems.
Government Mandates and Policy Initiatives
Federal and regional transportation agencies enforce regulations encouraging smart traffic management. Policies emphasize the role of connected systems in reducing accidents and emissions. Public-private partnerships strengthen RSU rollout through shared infrastructure frameworks. The U.S. Department of Transportation and Transport Canada fund large-scale pilot programs. These efforts align with national strategies for intelligent mobility and sustainable transit. It enhances interoperability between different network operators and municipal systems. Consistent policy backing ensures stable long-term investment. The continuous support creates a strong foundation for expanding RSU coverage.
Technological Advancements and 5G Integration
Emerging wireless technologies accelerate the efficiency of connected infrastructure. Integration of 5G enables faster data transmission and lower latency in V2X systems. RSUs equipped with edge computing capabilities enhance real-time decision-making. Manufacturers develop units supporting dual communication protocols like DSRC and C-V2X. It allows flexible adoption across various transportation frameworks. Advancements in cybersecurity improve protection against data breaches and interference. Telecom firms collaborate with transport authorities to synchronize spectrum use. The rapid evolution of connectivity tools supports scalable and future-ready RSU deployments.
- For example, Qualcomm has demonstrated that its C-V2X technology can deliver latency performance around 2–3 milliseconds under optimal network conditions, supporting advanced vehicle-to-everything (V2X) safety systems. This capability is widely cited in industry trials across North America and forms a key benchmark for connected and autonomous vehicle communication reliability.
Market Trends
Adoption of Hybrid Communication Models
The U.S. and Canada Road Side Unit (RSU) Market witnesses a shift toward hybrid communication frameworks. Manufacturers integrate both Dedicated Short-Range Communication (DSRC) and Cellular V2X (C-V2X) standards. This approach provides flexibility to adapt to diverse regional regulations and technologies. It helps municipalities future-proof their systems for evolving connectivity needs. Telecom operators promote hybrid architectures for smoother transition to 5G networks. Automotive OEMs prefer multi-standard RSUs to ensure broad compatibility. The hybrid trend ensures long-term interoperability across vehicles and infrastructure. It drives standard alignment between agencies, automakers, and network providers.
- For instance, the Tampa Hillsborough Expressway Authority (THEA) Connected Vehicle Pilot (2016–2022), sponsored by USDOT, deployed dual-mode Road Side Units supporting both DSRC and LTE-C-V2X. It involved over 1,000 vehicles and tested hybrid communication protocols to ensure reliable V2V and V2I connectivity across downtown Tampa.
Integration with Smart City Ecosystems
Smart city projects rely on intelligent transport systems to enhance mobility and safety. RSUs form the backbone of real-time traffic analytics and environmental monitoring. The market benefits from urban digitization programs and infrastructure modernization. City planners adopt RSUs to support adaptive signal control and emergency response. It links transportation grids with sensors, cameras, and data platforms. Public infrastructure managers use RSU data to optimize traffic flow and reduce emissions. Integration into wider smart city networks improves public safety and resource planning. The growing linkage accelerates coordinated investments in connected mobility corridors.
Expansion of Public-Private Collaborations
Public-private partnerships increase RSU implementation speed across North America. Transportation authorities collaborate with telecom operators and equipment manufacturers. Shared funding and deployment models reduce infrastructure costs for cities. The market sees joint ventures between regional agencies and automotive leaders. It supports standardized frameworks for interoperability and maintenance. Partnerships encourage the development of national guidelines for connected systems. Continuous cooperation strengthens cross-border integration between U.S. and Canadian networks. The collective approach enhances nationwide readiness for autonomous transport infrastructure.
- For instance, the THEA pilot exemplifies public-private collaboration with USDOT funding, local government participation, telecom providers, and automotive OEMs cooperating to deploy connected vehicle infrastructure. The pilot included OEM device interoperability tests and spectrum interference support, backed by a $20-million investment program. This cooperative model enabled standardized deployment frameworks and cross-sector integration critical for RSU network expansion.
Rise of Data Analytics and Cloud-Based Management
Data-driven management shapes the evolution of connected transport networks. RSUs gather massive volumes of data on traffic, weather, and vehicle behavior. The use of cloud-based platforms supports predictive analytics and system optimization. Transportation departments use real-time insights to manage congestion and road incidents. It improves public transit efficiency and safety across urban regions. The integration of AI tools enhances decision-making for signal and route management. Vendors develop advanced dashboards to visualize RSU performance metrics. The growing focus on analytics supports long-term scalability in network planning.
Market Challenges Analysis
High Deployment Costs and Infrastructure Complexity
The U.S. and Canada Road Side Unit (RSU) Market faces high costs linked to hardware, connectivity, and installation. Municipalities often struggle to allocate budgets for large-scale rollouts. Integrating RSUs into existing road systems requires major structural upgrades. The lack of uniform standards across regions complicates implementation. Rural and low-traffic areas experience slower adoption due to limited funding. It raises the cost per unit and limits economies of scale. Coordination among federal, regional, and local bodies remains inconsistent. The combined effect slows deployment speed across North America.
Cybersecurity Threats and Data Privacy Concerns
Connected transportation networks face increasing risks of cyber intrusion. RSUs exchange sensitive vehicle and traffic data, making them potential attack targets. Weak encryption and outdated firmware increase vulnerabilities. It forces authorities to invest heavily in secure software frameworks. Frequent security audits and regulatory compliance create additional operational pressure. The growing reliance on cloud systems demands stronger encryption protocols. Limited awareness among smaller municipalities hinders consistent protection. Continuous monitoring and international cooperation are required to maintain network resilience.
Market Opportunities
Expansion of Connected Mobility Corridors
The U.S. and Canada Road Side Unit (RSU) Market gains opportunities from the expansion of connected highway projects. Governments plan dedicated corridors linking cities with advanced V2X infrastructure. Telecom players deploy high-bandwidth networks to support real-time communication. It enables smoother data transfer between vehicles and roadside units. Logistics and public transport sectors integrate RSUs for fleet optimization. Rising demand for safety and automation strengthens investment pipelines. The corridor-based model supports cross-border data continuity and regional traffic intelligence. Broader infrastructure integration boosts the market outlook across both nations.
Integration with Autonomous Vehicle Ecosystem
Rapid growth in autonomous vehicle testing increases RSU relevance. Automakers collaborate with cities to develop vehicle-infrastructure communication standards. RSUs play a vital role in situational awareness and hazard detection. It supports sensor fusion by providing environmental data to autonomous systems. Technology vendors design low-latency solutions compatible with evolving mobility platforms. Collaboration between transport agencies and AI developers accelerates innovation cycles. The synergy between automation and infrastructure transforms long-term mobility planning. These partnerships open new revenue streams for technology and network providers.
 Market Segmentation Analysis
By Product Type
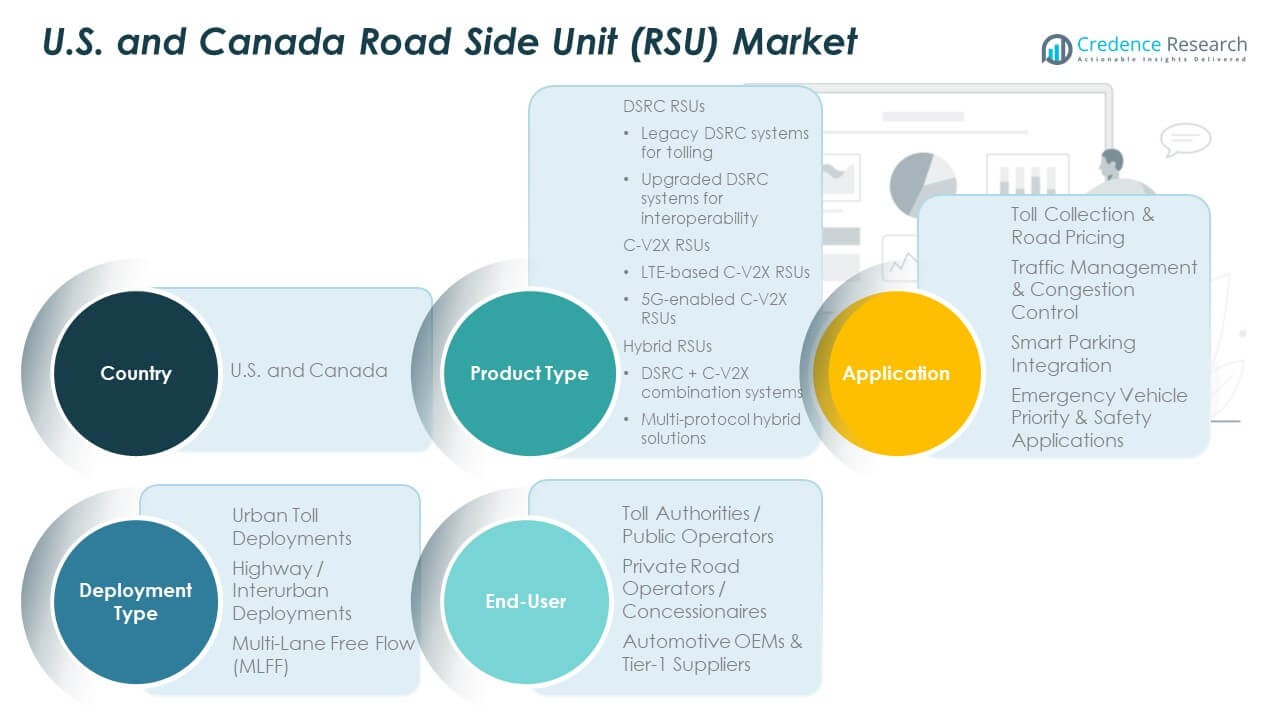
The U.S. and Canada Road Side Unit (RSU) Market is segmented into DSRC RSUs, C-V2X RSUs, and hybrid RSUs. DSRC units dominate legacy tolling systems and upgraded versions improve interoperability across networks. C-V2X RSUs, both LTE-based and 5G-enabled, witness strong adoption due to low latency and reliable data exchange. Hybrid RSUs combining DSRC and C-V2X support smooth transition between technologies. It benefits from government-led trials and private deployments promoting multi-protocol compatibility. Manufacturers prioritize scalable, future-ready systems to align with regional mobility goals. Continuous development ensures high performance for next-generation communication environments.
By Application
The market covers toll collection and road pricing, traffic management and congestion control, smart parking integration, and emergency vehicle priority applications. Toll collection holds strong demand from urban and highway corridors requiring automation. Traffic management applications expand with connected signals and congestion analytics. Smart parking projects integrate RSUs with IoT platforms for efficient space use. Emergency vehicle prioritization gains traction through city-level pilot programs. It supports faster and safer mobility while strengthening intelligent transport infrastructure.
By Deployment Type
Urban toll deployments lead adoption due to growing metropolitan infrastructure upgrades. Highway and interurban installations support high-speed communication and freight movement. Multi-lane free flow (MLFF) systems grow steadily with electronic toll collection programs. It enhances operational efficiency by reducing manual intervention. Large-scale deployment across major routes ensures improved real-time monitoring. Integration with 5G networks supports scalability for long-term transport modernization.
- For exampale, Kapsch TrafficCom collaborated with the Colorado Department of Transportation (CDOT) on connected vehicle deployments along the I-70 Mountain Corridor, using C-V2X-enabled roadside units to support V2X communication. The project represents one of the largest connected vehicle infrastructure initiatives in the United States, aimed at improving road safety and traffic management through real-time data exchange.
By End-User
Key end-users include toll authorities, public operators, private concessionaires, and automotive OEMs with Tier-1 suppliers. Public operators dominate early installations under smart city initiatives. Private operators focus on revenue optimization and maintenance efficiency. Automotive OEMs adopt RSUs to support autonomous and connected vehicle ecosystems. It fosters strong collaboration between infrastructure developers and technology vendors. Growing alignment among stakeholders supports nationwide adoption of advanced RSU networks.
- For instance, the Colorado Department of Transportation leveraging Kapsch RSUs has established a connected vehicle corridor on I-70, operated in partnership with Qualcomm and Panasonic. Public agencies benefit from scalable RSU infrastructure that supports automated tolling and traffic safety.
Segmentation
By Product Type
- DSRC RSUs
- Legacy DSRC systems for tolling
- Upgraded DSRC systems for interoperability
- C-V2X RSUs
- LTE-based C-V2X RSUs
- 5G-enabled C-V2X RSUs
- Hybrid RSUs
- DSRC + C-V2X combination systems
- Multi-protocol hybrid solutions
By Application
- Toll Collection & Road Pricing
- Traffic Management & Congestion Control
- Smart Parking Integration
- Emergency Vehicle Priority & Safety Applications
By Deployment Type
- Urban Toll Deployments
- Highway / Interurban Deployments
- Multi-Lane Free Flow (MLFF)
By End-User
- Toll Authorities / Public Operators
- Private Road Operators / Concessionaires
- Automotive OEMs & Tier-1 Suppliers
Regional Analysis
United States Leads with Strong Infrastructure Investments
The U.S. and Canada Road Side Unit (RSU) Market is dominated by the United States, holding around 75% share of the regional revenue. The dominance is driven by large-scale smart transportation projects, 5G-enabled vehicle-to-everything (V2X) trials, and federal programs supporting connected vehicle deployment. States such as California, Texas, and Michigan lead installations across urban and highway corridors. The U.S. Department of Transportation and state agencies invest in nationwide interoperability frameworks. It benefits from a mature ecosystem of telecom operators and automotive OEMs collaborating on C-V2X and hybrid RSUs. Growing emphasis on congestion control and emergency response integration further accelerates market growth.
Canada Exhibits Steady Growth Through Public Initiatives
Canada holds nearly 25% share of the North American RSU market, with momentum supported by its expanding smart mobility framework. The federal and provincial governments promote connected road infrastructure to enhance public safety and reduce emissions. Key cities like Toronto, Vancouver, and Montreal are testing RSU-based solutions in coordination with telematics and IoT providers. It gains traction from the development of hybrid DSRC and C-V2X systems tailored for regional climates. Public-private partnerships strengthen technology transfer and local manufacturing capacity. Gradual policy evolution and harmonization with U.S. standards support seamless cross-border communication. Continued investments in 5G corridors and smart intersections sustain the country’s rising adoption rate.
Cross-Border Integration Strengthens Market Expansion
Cross-border freight and logistics drive a growing need for connected infrastructure between the U.S. and Canada. Both governments align communication standards to enhance road safety and trade efficiency. It promotes joint pilot programs for V2X data sharing and real-time mobility management. Interoperable RSUs support vehicle tracking, tolling, and hazard alerts along major trade routes. The coordinated policy approach fosters investment from automotive and telecom sectors. Technology convergence ensures data security and latency control across network boundaries. The shared digital infrastructure strengthens the overall competitiveness of the North American RSU ecosystem.
Key Player Analysis
- Kapsch TrafficCom
- Savari / Harman
- Yunex Traffic
- Q-Free (C-ITS)
- Commsignia
Competitive Analysis
The U.S. and Canada Road Side Unit (RSU) Market features a moderately consolidated landscape dominated by global and regional technology providers. Leading players include Kapsch TrafficCom, Siemens Mobility, Cohda Wireless, Qualcomm Technologies, Savari Inc., Commsignia, and Yunex Traffic, all of which actively expand through product innovation and partnerships. Companies focus on hybrid RSU platforms supporting both DSRC and C-V2X standards to serve evolving transportation demands. It experiences high competition in government procurement and public-private partnerships for smart corridor development. Major firms emphasize integration with 5G networks and AI-driven analytics to improve data management and latency. Collaborations between OEMs and telecom operators strengthen real-world deployment and system validation. Vendors such as Kapsch TrafficCom and Siemens lead in tolling and congestion management, while Commsignia and Cohda Wireless focus on V2X communication modules. Canadian companies explore localized manufacturing for public infrastructure contracts, enhancing supply resilience. Continuous R&D investment in security, interoperability, and scalability ensures product differentiation. Strategic alliances and regional pilot programs remain the core growth enablers shaping market competitiveness.
Recent Developments
- In August 2025, Kapsch TrafficCom announced an advanced V2X tolling solution tailored for North America, incorporating back-office operational integration to facilitate commercial deployment. This system enables interoperability with traditional RFID tolling, offering drivers real-time toll alerts, accurate pricing, and seamless payment options directly through their vehicles.
- In August 2025, INTEGRITY Security Services™ (ISS) formed a strategic partnership with Danlaw and Cohda Wireless to advance V2X innovations. The collaboration enables Danlaw’s RouteLink RSUs to include ISS’s TrafficAuth-SCMS client libraries, enhancing secure, interoperable communication between vehicles, roadside units and mobile infrastructure
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Deployment Type and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. and Canada Road Side Unit (RSU) Market will expand with stronger V2X infrastructure integration across urban and intercity routes.
- Government investments in intelligent transportation networks will accelerate deployment of connected vehicle corridors.
- 5G and edge computing integration will enhance real-time communication and enable next-generation mobility applications.
- Hybrid RSUs combining DSRC and C-V2X protocols will become the preferred standard for interoperability.
- Cross-border cooperation between the U.S. and Canada will create unified regulatory frameworks for smart transportation.
- Rising adoption of autonomous and electric vehicles will boost demand for low-latency roadside communication systems.
- Partnerships between telecom operators, OEMs, and infrastructure agencies will shape technology innovation and deployment pace.
- Cybersecurity and data privacy advancements will remain key priorities for government and private operators.
- Cloud-based analytics and AI-driven insights will improve traffic management and system scalability.
- Continuous public-private collaboration will ensure sustainable expansion of smart transport infrastructure across North America.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the U.S. and Canada Road Side Unit (RSU) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. and Canada Road Side Unit (RSU) Market projected to grow between 2024 and 2032?
Which U.S. and Canada Road Side Unit (RSU) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. and Canada Road Side Unit (RSU) Market?
Who are the leading companies in the U.S. and Canada Road Side Unit (RSU) Market?
Which region commanded the largest share of the U.S. and Canada Road Side Unit (RSU) Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,784.95 million → 2032: USD 7,063.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. and Canada Road Side Unit (RSU) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. and Canada Road Side Unit (RSU) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. and Canada Road Side Unit (RSU) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. and Canada Road Side Unit (RSU) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. and Canada Road Side Unit (RSU) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. and Canada Road Side Unit (RSU) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. and Canada Road Side Unit (RSU) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. and Canada Road Side Unit (RSU) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,784.95 million → 2032: USD 7,063.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. and Canada Road Side Unit (RSU) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. and Canada Road Side Unit (RSU) Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. and Canada Road Side Unit (RSU) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. and Canada Road Side Unit (RSU) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
