
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan Testing, Inspection and Certification Market Size 2023 | USD 12,050.96 Million |
| Japan Testing, Inspection and Certification Market, CAGR | 4.76% |
| Japan Testing, Inspection and Certification Market Size 2032 | USD 18,313.91 Million |
Market Overview
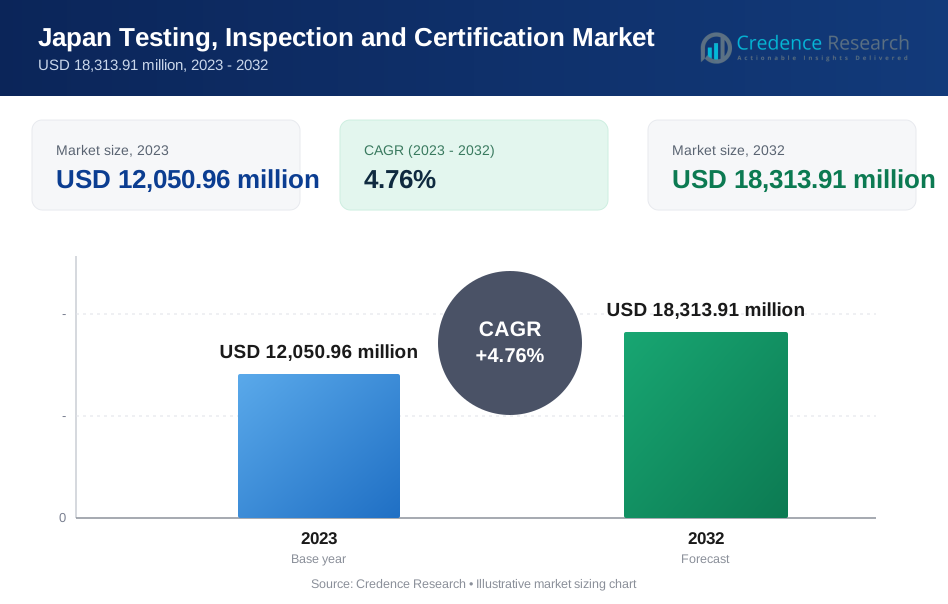
The Japan Testing, Inspection, and Certification market is projected to grow from USD 12,050.96 million in 2023 to USD 18,313.91 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.76%.
The Japan Testing, Inspection, and Certification market is driven by stringent regulatory standards, increasing demand for quality assurance, and the growing complexity of manufacturing processes. Technological advancements, particularly in automation and digitalization, are enhancing the efficiency and accuracy of testing and inspection services. Additionally, the rise in international trade and the need for compliance with global standards are fueling market growth. Emerging trends include the integration of AI and IoT in inspection processes, and the shift towards sustainability and environmental compliance, which are becoming critical focal points for industry stakeholders.
The Japan Testing, Inspection, and Certification market sees significant activity in major industrial regions such as Tokyo, Osaka, and Nagoya, where manufacturing and technological industries are concentrated. These regions drive market demand due to their high production volumes and stringent quality standards. Key players in the market include SGS SA, Bureau Veritas, TÜV SÜD, Intertek Group, and Japan Quality Assurance Organization (JQA), all of which provide comprehensive services across various sectors. These companies are leveraging advanced technologies and expanding their service portfolios to maintain competitive advantages and meet the evolving needs of Japanese industries.
Market Drivers
Increasing Focus on Product Safety and Quality
Japan has a well-deserved reputation for producing high-quality goods, supported by stringent regulations and standards to ensure product safety. For instance, in the automotive sector, adherence to the voluntary Japan Industrial Standards (JIS) is crucial, with over 10,773 standards as of March 2019. These standards are administered by the Ministry of Economy, Trade and Industry (METI) and cover nearly 743 different industrial product categories. In the electronics sector, the Electrical Appliances and Materials Safety Act regulates 457 products, ensuring that electrical appliances meet rigorous safety criteria. Similarly, the food and beverages sector is governed by the Japan Agricultural Standards (JAS), which are established by the Ministry of Agriculture, Forestry and Fisheries (MAFF) and cover a wide range of products.
Globalization and International Trade
As Japan continues to engage in international trade agreements, the need for TIC services to ensure products meet the quality and safety standards of different countries is rising. For instance, Japan’s trade openness ratio has reached record highs as market liberalization measures take effect, reflecting the country’s increasing engagement in international trade agreements. In 2023, Japan managed to downsize the deficit in goods and service trade on its balance of international payments (BoP), bolstered by its growing export position for physical goods. Major commodities exported from Japan include electrical and general machinery, as well as transport equipment, which benefit from Japan’s favorable reputation in the global market. TIC services are essential in this context, as they ensure that Japanese products adhere to the quality and safety standards required by different countries. For example, Japan’s ratification of the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) and the Regional Comprehensive Economic Partnership (RCEP) signifies deepening relationships with ASEAN and South American regions, necessitating robust TIC services to maintain compliance with a wide array of regulatory standards.
Technological Advancements
Technological advancements, particularly in the Internet of Things (IoT) and Artificial Intelligence (AI), are transforming the TIC landscape. IoT devices create new testing requirements to ensure data security and product functionality, while AI enhances the efficiency and accuracy of inspections by automating repetitive tasks. In terms of AI, it’s estimated that the use of AI can reduce the time spent on inspections by up to 50%, enhancing efficiency and potentially saving millions in operational costs. Moreover, AI-driven analytics can predict equipment failures with an accuracy of over 80%, allowing for proactive maintenance and reducing downtime. These technological advancements not only meet the current needs of industries but also set a new benchmark for quality and safety, ensuring that TIC providers remain at the forefront of innovation. These advancements enable TIC providers to offer more sophisticated and comprehensive testing solutions, meeting the evolving needs of industries and ensuring high standards of quality and safety.
Sustainability and Environmental Concerns
Growing concerns about sustainability and environmental impact are also influencing the TIC market. Stricter regulations and the demand for environmentally friendly products are compelling businesses to seek TIC services to ensure compliance with these standards. By helping businesses verify their products' sustainability credentials, TIC services are playing a vital role in supporting environmental initiatives and promoting sustainable practices across industries.
Market Trends
Shift Towards Digitalization and Automation
The Testing, Inspection, and Certification (TIC) industry is increasingly embracing digital technologies to enhance efficiency and accuracy. For instance, the TIC industry’s digital transformation is well underway, with almost 90 percent of organizations worldwide having implemented cloud technologies as of 2022. This adoption rate is the highest among all emerging technologies, reflecting the industry’s commitment to enhancing data management and accessibility. In terms of automation, the integration of robotics into testing processes is becoming more prevalent. For example, the use of robotics has led to a significant reduction in human error and a notable increase in the speed of procedures, although specific numbers vary by company and application. Artificial Intelligence (AI) is another area where the TIC industry is making strides. AI algorithms are capable of processing large datasets rapidly, identifying patterns and anomalies that might otherwise be overlooked. While adoption rates of AI technology vary across industries, sectors such as technology and telecommunications are leading the way, utilizing AI in product and service development to drive intelligent decision-making and enhance customer service.
Focus on Emerging Technologies and Market Dynamics
As cutting-edge technologies like AI, IoT, and autonomous vehicles gain traction, the TIC industry is adapting its services to meet the specific challenges and regulatory requirements these technologies present. In the realm of autonomous vehicles, the integration of artificial intelligence (AI) is propelling vehicles into unprecedented levels of autonomy. The current industry landscape shows that in 2024, there are some 54 million cars with at least some level of automation in operation worldwide. This number is a significant increase from the 31 million in 2019, reflecting the rapid adoption of autonomous technology. For instance, IoT devices necessitate rigorous testing for data security and operational reliability, while autonomous vehicles require comprehensive certification to ensure safety and functionality. TIC companies are continuously evolving to provide specialized testing and certification services that address these emerging needs.
Market Challenges Analysis
Low Adoption Rate of Innovative Technologies and Skilled Labor Shortage
Despite Japan's reputation for high-quality production, some sectors within the Testing, Inspection, and Certification (TIC) market have been slow to fully embrace innovative technologies such as automation and AI. This reluctance can hinder efficiency and accuracy in testing and inspection processes, preventing companies from realizing the full benefits of technological advancements. The integration of these technologies can significantly enhance operational capabilities, yet the pace of adoption remains uneven across the industry. Compounding this issue is the skilled labor shortage within the TIC sector. The industry relies heavily on a workforce with specialized expertise in various testing methodologies and regulatory standards. However, Japan's aging population and the widening skills gap present significant challenges in recruiting and retaining qualified personnel. The shortage of skilled labor not only affects the quality and reliability of TIC services but also limits the industry's capacity to innovate and expand. Addressing this shortage through targeted training programs and attracting younger talent is crucial for the sustained growth and competitiveness of the TIC market in Japan.
Complex Regulatory Landscape and Increasing Competition
The TIC market in Japan also faces the challenge of navigating a complex and frequently updated regulatory landscape. The country’s stringent regulations, while ensuring high standards of quality and safety, can be difficult to keep pace with for both TIC providers and businesses. Frequent updates and the intricate nature of these regulations often lead to compliance challenges, resulting in delays and increased operational costs. TIC providers must continuously adapt to these changes to maintain compliance and offer reliable services, which requires significant investment in regulatory expertise and agile processes. Furthermore, the Japanese TIC market is becoming increasingly competitive with the influx of international players vying for market share. This intensifies the pressure on domestic providers to offer competitive pricing and high-quality services to retain and attract clients. International competition brings additional challenges in standardizing TIC practices across global markets. As international trade expands, ensuring that products meet the diverse quality and safety standards of different countries becomes more complex. TIC providers must navigate this complexity to effectively serve their clients and maintain their competitive edge in the global market.
Market Segmentation Analysis:
By Service Type:
The Japan Testing, Inspection, and Certification (TIC) market is segmented by service type into testing, inspection, and certification. The testing segment holds a significant share due to the stringent regulatory requirements across various industries such as automotive, electronics, and food and beverages. Comprehensive testing services ensure that products meet safety and quality standards, which is crucial for maintaining consumer trust and regulatory compliance. The inspection segment is also robust, driven by the need for thorough evaluations of manufacturing processes and product quality. Regular inspections help in identifying potential issues early, thereby reducing the risk of product recalls and enhancing overall quality control. The certification segment is essential for verifying that products and processes meet specific standards and regulations, which is particularly important for companies aiming to expand their market presence domestically and internationally. Certification not only enhances product credibility but also facilitates smoother market entry in global markets by demonstrating compliance with international standards.
By Sourcing Type:
Based on sourcing type, the TIC market in Japan is divided into outsourced and in-house services. Outsourced TIC services are increasingly popular as companies seek to leverage specialized expertise and advanced technologies that external TIC providers offer. Outsourcing helps businesses reduce costs associated with maintaining in-house testing and inspection facilities, and it allows access to a broader range of services and capabilities. This trend is particularly strong among small and medium-sized enterprises that may lack the resources to develop comprehensive in-house TIC capabilities. In contrast, larger corporations with substantial resources often prefer in-house TIC services to maintain tighter control over their quality assurance processes. In-house services enable these companies to integrate TIC functions seamlessly into their operations, ensuring a consistent application of standards and quicker turnaround times. Both sourcing types play crucial roles in the TIC market, catering to different needs based on company size, industry requirements, and strategic priorities.
Segments:
Based on Service Type
- Testing
- Inspection
- Certification
Based on Sourcing Type
- Outsourced Source
- In-House
Based on End-User
- Consumer Goods and Retail
- Food and Agriculture
- Oil and Gas
- Construction and Engineering
- Energy and Chemicals
- Manufacturing of Industrial Goods
- Transportation (Rail and Aerospace)
- Industrial and Automotive
- Other End-user Verticals
Based on the Geography:
- Kanto region
- Chubu region
- Kansai region
- Kyushu region
- Tohoku
- Chugoku
- Shikoku
Regional Analysis
Kanto region
The Kanto region, including Tokyo and its surrounding prefectures, currently holds the largest market share, accounting for approximately 35% of the national revenue. This dominance can be attributed to the region's well-established manufacturing sectors, stringent quality standards, and the presence of major TIC service providers. Tokyo, being the economic hub of Japan, significantly contributes to the market's growth through its diverse industries, including automotive, electronics, and consumer goods.
Chubu region
The Chubu region, comprising prefectures like Aichi and Shizuoka, follows closely, capturing a market share of around 25%. The region's thriving automotive and electronics manufacturing sectors, coupled with the emphasis on quality assurance, have fueled the demand for TIC services. Cities like Nagoya and Toyota City are major contributors to the market's growth, driven by their robust industrial bases and the need for compliance with domestic and international standards.
Key Player Analysis
- SGS SA
- American Bureau of Shipping
- AmSpec LLC
- Apave Group
- Applus Services S.A
- AsureQuality Ltd
- Bureau Veritas SA
- Cotecna Inspection SA
- DEKRA SE
- DNV Group AS
- Element Materials Technology Group Ltd
- Eurofins Scientific SE
- Helmsman Quality and Technology Services Co. Ltd.
- Intertek Group Plc
- Japan Inspection Co. Ltd
- L and T Technology Services Ltd
- TUV NORD Group
- TUV Rheinland AG
- TUV SUD AG
- UL Solutions Inc.
Competitive Analysis
The Japan Testing, Inspection, and Certification (TIC) market is highly competitive, with major players such as SGS SA, Bureau Veritas SA, and Intertek Group Plc leading the industry. These companies offer comprehensive TIC services across various sectors, leveraging their global presence and extensive expertise. SGS SA and Bureau Veritas SA are particularly strong in automotive, electronics, and food safety, providing robust testing and certification services that meet stringent Japanese and international standards. Intertek Group Plc is noted for its advanced technological capabilities and extensive laboratory network, enhancing its competitive edge in the market. Japanese firms like Japan Inspection Co. Ltd and Helmsman Quality and Technology Services Co. Ltd. also play significant roles, benefiting from their deep understanding of local regulatory requirements and strong industry relationships. TUV NORD Group, TUV Rheinland AG, and TUV SUD AG are prominent for their technical excellence and innovation, particularly in the automotive and industrial sectors.
Recent Developments
In December 2023, UL LLC and Hyundai Mobis North America signed a memorandum of understanding (MOU) to enhance the safety and performance of electric vehicle batteries. Through leveraging the UL LLC North America Advanced Battery Laboratory in Michigan, this partnership seeks to facilitate the safe and widespread deployment of electric vehicle battery technology amid the increasing global adoption of electric vehicles.
In November 2023, Intertek Group plc partnered with Emitech Group to broaden its European electrical testing capabilities. Emitech Group is an independent testing and engineering expert accredited with EN 17025 and EN 17065.
In October 2023, TÜV Rheinland acquired Burotec, a Spanish business group offering comprehensive inspection, engineering, and security services. This acquisition enhances TÜV Rheinland’s voluntary services activities and expands its service portfolio in Spain.
In September 2023, DNV GL introduced its newest service specification, DNV-SE-0656, which is designed to verify Power-to-X (PtX) facilities. This updated specification encompasses PtX and process facilities, offering a comprehensive framework for independent risk-based verification or certification. PtX involves the conversion of electricity into various fuels, including hydrogen, methane, ammonia, kerosene, and methanol. Typically, this process utilizes renewable electricity and biogenic carbon dioxide (CO2) to minimize greenhouse gas (GHG) emissions during fuel production and utilization.
In July 2023, SGS SA provided verification and assessment services for infrastructure and energy subsystems in railways. These accreditations, along with the company’s existing accreditations for rolling stock and control, command, and signaling subsystems, enabled the completion of the full Technical Specifications for Interoperability (TSI) certification process for railway subsystems.
Market Concentration & Characteristics
The Japan Testing, Inspection, and Certification (TIC) market is characterized by a moderate to high level of market concentration, with a few dominant players such as SGS SA, Bureau Veritas SA, and Intertek Group Plc holding substantial market shares. These companies benefit from extensive global networks, advanced technological capabilities, and comprehensive service portfolios, which provide them with significant competitive advantages. The market is marked by stringent regulatory standards and a high demand for quality assurance across industries like automotive, electronics, and food and beverages. Local players, such as Japan Inspection Co. Ltd, also maintain strong positions by leveraging their deep understanding of domestic regulations and robust client relationships. The market's competitive landscape is further shaped by ongoing technological advancements and the increasing integration of AI and IoT in TIC processes, driving efficiency and accuracy. This dynamic environment necessitates continuous innovation and adaptation by TIC providers to meet the evolving needs of their clients and maintain their market positions.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Sourcing Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continuous Growth: The Japan Testing, Inspection, and Certification (TIC) Market are expected to experience continuous growth driven by regulatory requirements and quality assurance standards across various industries.
- Regulatory Compliance: Stringent regulations and compliance requirements in sectors such as manufacturing, healthcare, and automotive will drive demand for testing, inspection, and certification services.
- Technological Advancements: Advancements in technology, such as IoT, AI, and blockchain, will shape the future of TIC services, enabling more efficient and accurate testing and inspection processes.
- Industry Diversification: The TIC market will witness diversification across industries, including electronics, food and beverages, construction, and energy, as companies prioritize quality and safety standards.
- Focus on Sustainability: With growing environmental concerns, there will be an increased emphasis on sustainability testing and certification services, driving demand for eco-friendly products and practices.
- Globalization: The globalization of trade will necessitate adherence to international standards and certifications, leading to a surge in cross-border TIC activities.
- Digital Transformation: Digitalization of TIC processes, including online certification platforms and remote inspection technologies, will enhance efficiency and accessibility of services.
- Risk Management: Businesses will increasingly rely on TIC services for risk management and mitigation, ensuring product quality, safety, and compliance with regulatory requirements.
- Emerging Technologies: The emergence of new technologies and industries, such as autonomous vehicles, renewable energy, and medical devices, will create new opportunities for TIC services.
- Collaboration and Partnerships: Collaboration between TIC companies, industry stakeholders, and regulatory bodies will drive innovation and standardization in testing and certification practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Testing, Inspection and Certification Market?
What factors are driving the growth of the Japan Testing, Inspection and Certification Market?
What are the key segments within the Japan Testing, Inspection and Certification Market?
What are some challenges faced by the Japan Testing, Inspection and Certification Market?
Who are the major players in the Japan Testing, Inspection and Certification Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Testing, Inspection and Certification Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Testing, Inspection and Certification Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 12,050.96 million → 2032: USD 18,313.91 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Testing, Inspection and Certification Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Testing, Inspection and Certification Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Testing, Inspection and Certification Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Testing, Inspection and Certification Market Drivers
- 3.3 Japan Testing, Inspection and Certification Market Restraints & Challenges
- 3.4 Japan Testing, Inspection and Certification Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Testing, Inspection and Certification Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Testing, Inspection and Certification Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Testing, Inspection and Certification category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Testing, Inspection and Certification Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Testing, Inspection and Certification Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Testing, Inspection and Certification market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Testing, Inspection and Certification Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Testing, Inspection and Certification Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Testing, Inspection and Certification Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Testing, Inspection and Certification (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Testing, Inspection and Certification Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Testing, Inspection and Certification Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Testing, Inspection and Certification Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Testing, Inspection and Certification Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Testing, Inspection and Certification Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Testing, Inspection and Certification Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Testing, Inspection and Certification Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Testing, Inspection and Certification Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Testing, Inspection and Certification Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
